Where It All Began
The origins of the formula to calculate net worth of a company trace back to the 18th century, when double-entry bookkeeping became the backbone of financial transparency. Early merchants and industrialists needed a way to track assets, liabilities, and equity—what we now call the balance sheet. But these early frameworks were crude by modern standards. They focused almost exclusively on tangible assets: land, machinery, inventory. The idea that a company’s worth could extend beyond its physical holdings was foreign. The first cracks in this rigid model appeared in the late 19th century, as corporations began to recognize intangible assets like trademarks and goodwill. Railroads, for instance, would pay premiums to acquire competitors not just for their tracks but for their established routes and customer bases. Accountants scrambled to adapt, introducing concepts like "purchased goodwill" to reflect these invisible values. Yet even then, the calculation of net worth remained tied to hard assets. The intangible was an afterthought, not a cornerstone.The Early Signs
The real shift didn’t come until the 20th century, when corporations grew large enough that their value could no longer be measured by a simple subtraction of liabilities from assets. The rise of conglomerates like General Electric and IBM forced analysts to consider non-financial drivers of value, such as research and development pipelines or brand recognition. By the 1960s, economists like Franco Modigliani and Merton Miller were formalizing the idea that a company’s worth was tied to its future cash flows, not just its current assets. This was the birth of modern valuation theory. Suddenly, the formula to calculate net worth of a company wasn’t just about what it owned but what it could generate over time. Discounted cash flow (DCF) models emerged, allowing investors to project earnings decades into the future and assign them a present value. Yet even this innovation had limits. DCF relies on assumptions about growth rates and discount rates—both of which are subjective. The net worth of a company, in this view, became as much an art as a science.The Turning Point
The 1980s marked the turning point. Leveraged buyouts, hostile takeovers, and the rise of private equity redefined what a company was worth. Firms like Kohlberg Kravis Roberts (KKR) proved that a company’s value could exceed its book value by orders of magnitude if it had strong cash flows and a clear exit strategy. The traditional formula to calculate net worth—assets minus liabilities—was no longer sufficient. Investors began looking at enterprise value, which included debt and minority stakes, to get a fuller picture. This era also saw the birth of market-based valuation methods, such as price-to-earnings (P/E) ratios and enterprise value-to-EBITDA (EV/EBITDA) multiples. These metrics allowed for quick comparisons across industries, but they came with their own pitfalls. A high P/E ratio could signal growth potential—or overvaluation. The net worth of a company, in this new paradigm, was increasingly tied to its relative performance in the market, not just its balance sheet."The price you pay for a stock is what matters, not the book value. Book value is history; price is what you’re buying the future for." — Warren Buffett, 1992 Berkshire Hathaway Shareholder LetterThe turning point wasn’t just about new methods; it was about a fundamental shift in how value was perceived. Companies like Microsoft and Apple, which had little in the way of physical assets, proved that net worth could be built on code, design, and customer ecosystems—not just factories and cash.

The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1920s–1940s |
The Great Depression exposed flaws in balance-sheet-based valuation. Investors realized that liquidity and cash flow mattered more than assets alone. The concept of "working capital" emerged as a critical metric. |
| 1960s–1970s |
DCF models gained traction as economists formalized the idea that a company’s value is the sum of its future cash flows. The rise of multinationals forced accountants to grapple with currency risks and foreign asset valuation. |
| 1980s–1990s |
LBOs and private equity introduced enterprise value as a key metric. The dot-com bubble burst revealed the dangers of valuing companies based on hype rather than fundamentals, leading to a back-to-basics approach in the early 2000s. |
| 2010s–Present |
The rise of tech giants with minimal tangible assets forced a rethink of valuation. Metrics like "revenue multiples" and "user growth" became critical, while traditional net worth calculations struggled to account for AI, data, and digital ecosystems. |
Lessons From the Journey
- Book value is a starting point, not an endpoint. The basic formula to calculate net worth of a company (assets minus liabilities) ignores intangibles, which can dominate value in modern firms.
- Market sentiment distorts reality. A company’s stock price can spike or crash based on news cycles, not fundamentals—making net worth calculations highly volatile.
- Industry-specific metrics matter. A biotech firm’s worth isn’t measured like a utility company’s; its pipeline of drugs or patents often outweighs traditional assets.
- Debt isn’t always a liability. In some cases, leverage can amplify returns, making enterprise value a better proxy for true net worth than book value.
- Regulatory changes reshape valuation. New accounting rules (like IFRS or GAAP updates) can suddenly reclassify assets, altering perceived net worth overnight.
- The future isn’t guaranteed. Even the best formula to calculate net worth of a company fails if it assumes perpetual growth—recessions, disruptions, and black swan events can erase value instantly.
Where Things Stand Today
Today, the formula to calculate net worth of a company is a patchwork of methods, each with strengths and weaknesses. Public firms rely on a mix of book value, market capitalization, and DCF models, while private companies often use comparable company analysis or precedent transactions. Yet none of these capture the full picture. The rise of alternative assets—from cryptocurrency holdings to AI-trained models—has left traditional valuation frameworks struggling to keep up. The biggest challenge? Intangible assets now account for over 90% of the S&P 500’s market value, according to some estimates. Brands like Apple or Coca-Cola derive most of their worth from customer loyalty and intellectual property, not factories or inventory. Yet these assets are notoriously hard to quantify. Some firms now attempt to "capitalize" goodwill or R&D spend, but the results are often arbitrary. The net worth of a company, in this era, is as much about perception as it is about numbers.
Conclusion
The search for the perfect formula to calculate net worth of a company is a story of evolution, not perfection. What worked for 19th-century railroads fails for 21st-century tech giants. The lesson? There is no single answer. Instead, investors and analysts must combine balance sheets, cash flow projections, market multiples, and qualitative assessments to paint a full picture. The future will likely bring even more complexity. As companies like Tesla or Nvidia blur the lines between hardware, software, and data, the calculation of net worth will require new frameworks—perhaps even blockchain-based asset tracking or AI-driven predictive models. One thing is certain: the art of valuation will never be reduced to a simple equation.Comprehensive FAQs
Q: What’s the simplest formula to calculate net worth of a company?
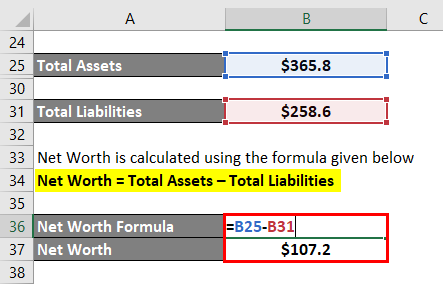
The most basic net worth calculation is total assets minus total liabilities, which gives you shareholders' equity. However, this ignores intangibles like brand value or future earnings potential, making it an incomplete picture for most modern firms.
Q: Why does market value often differ from book value?
Market value reflects investors’ expectations of future performance, while book value is a historical snapshot of assets and liabilities. A company like Amazon, for example, has a book value far below its market cap because investors bet on its long-term growth—something not captured in traditional net worth formulas.
Q: How do private companies calculate net worth without stock prices?
Private firms typically use comparable company analysis (valuing based on similar public companies) or discounted cash flow models to project future earnings. Private equity firms also rely on precedent transactions—what similar companies sold for in past deals—to estimate value.
Q: Can goodwill be part of a company’s net worth?
Yes, but it’s controversial. Goodwill—paid when acquiring another company—is recorded as an asset on the balance sheet. However, it’s not liquid and can be impaired (written down) if the acquired business underperforms. Some argue it’s a red herring in net worth calculations, while others treat it as a real (if volatile) component of value.
Q: What’s the difference between net worth and enterprise value?
Net worth (shareholders’ equity) measures what’s left after paying off liabilities. Enterprise value, however, includes debt and minority stakes, giving a fuller picture of a company’s total worth to all stakeholders. For example, a $100M company with $20M in debt has $100M net worth but $120M enterprise value.
Q: How do intangible assets affect net worth calculations?
Intangibles like patents, trademarks, and customer data can dominate a company’s value—sometimes accounting for 80% or more of market cap. Yet they’re rarely reflected in book value. Firms now attempt to "capitalize" these assets (e.g., amortizing R&D spend), but the methods are inconsistent and often arbitrary.
Q: What’s the biggest risk in relying on traditional net worth formulas?
The biggest risk is overlooking future value. A company like Google in 2004 had minimal tangible assets but was worth billions due to its search algorithm. Traditional net worth calculations would have undervalued it severely. The lesson? Static formulas fail in dynamic markets.
Q: Are there industries where book value is a good proxy for net worth?
Yes, in capital-intensive industries like manufacturing or utilities, where physical assets (plants, equipment) drive most value. For example, a steel mill’s net worth is closely tied to its machinery and inventory. In contrast, tech or media firms rely far more on intangibles.
