Where It All Began
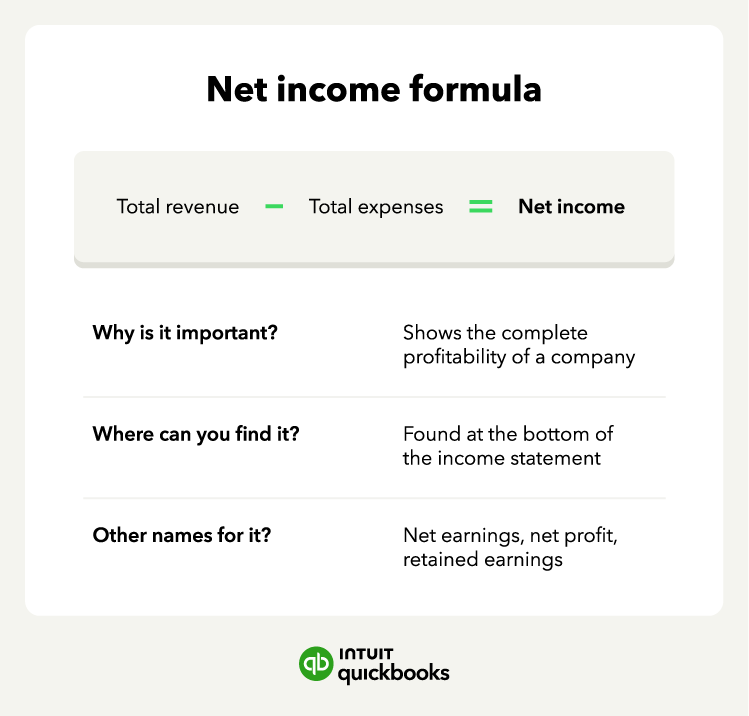
The origins of the formula of net worth ratio trace back to the late 19th century, when economists first attempted to quantify household solvency. Early attempts were crude: a farmer’s net worth might be tallied by counting cows and acres, while urban dwellers relied on property deeds and savings ledgers. The real breakthrough came in the 1930s, when the U.S. Bureau of Labor Statistics began tracking family financial security as part of its Depression-era surveys. Researchers noticed a pattern: households with a net worth ratio above 30% were far less likely to default on loans or rely on charity. The data suggested that wealth wasn’t just about having money—it was about structural resilience. By the 1950s, the ratio had seeped into corporate boardrooms. Banks started using simplified versions to assess loan applicants, and insurance underwriters adopted it to price policies. The formula itself was deceptively straightforward: (Total Assets – Total Liabilities) / Total Assets = Net Worth Ratio. But the devil was in the definitions. What counted as an asset? A primary residence? A vintage car? What about intangibles like education or social capital? The early iterations were messy, but they laid the groundwork for what would become a cornerstone of modern financial planning.The Early Signs
The first red flags appeared in the 1970s, when stagflation exposed the ratio’s dark side. Families with high ratios—often homeowners with mortgages—found themselves trapped as asset values stagnated while interest rates soared. The ratio wasn’t just a measure; it was a warning system. Economists at the time coined the term liquidity trap to describe how even solvent households could spiral into insolvency if their ratio dipped below a critical threshold. The real turning point came when behavioral economists realized the ratio wasn’t just mathematical—it was psychological. A 1985 study in the Journal of Consumer Research found that people with ratios above 50% felt financially secure, while those below 20% exhibited chronic stress. The ratio, in other words, wasn’t just a number. It was a feedback loop between perception and reality.The Turning Point
The 2008 financial crisis didn’t invent the net worth ratio, but it forced the world to reckon with its power. As housing prices collapsed, millions of Americans saw their ratios plummet overnight—some from 70% to negative territory. The ratio became a proxy for systemic risk, and policymakers scrambled to monitor it in real time. The Federal Reserve’s Survey of Consumer Finances began publishing ratio benchmarks by income bracket, revealing stark disparities: households headed by Black or Latino individuals had ratios averaging 10–15 percentage points lower than white households, even at similar income levels. What changed wasn’t the formula itself, but its purpose. It shifted from a personal tool to a macroeconomic indicator. Central banks used it to gauge household vulnerability, while fintech startups repurposed it as a risk-scoring algorithm. The ratio had gone from a back-office calculation to a cultural touchstone—evidence that wealth wasn’t just about dollars, but about leverage, timing, and systemic exposure."The net worth ratio isn’t a snapshot. It’s a movie reel of your financial life—fast-forward, rewind, and pause buttons all in one." — Robert Shiller, Yale Economist (2012)
The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 1990s | The rise of credit cards and home equity loans distorted the ratio for middle-class families. While assets grew, so did debt, creating a false sense of wealth. The average ratio for 35–44-year-olds dropped from 45% to 38%. |
| 2000–2007 | The housing bubble inflated ratios to unsustainable levels. Families with 80%+ ratios—often leveraged to the hilt—assumed their wealth was permanent. When the crash hit, ratios for this cohort fell by an average of 40 percentage points. |
| 2010–Present | Student debt and gig-economy income volatility reshaped the ratio’s composition. Millennials entered adulthood with ratios 20–25 points lower than their parents’, not due to spending habits, but to structural barriers in asset accumulation. |
Lessons From the Journey
- The ratio isn’t static. A 60% ratio in 2000 might mean very different things in 2024—assets today are more volatile (crypto, private equity) while liabilities include student loans and medical debt.
- Debt isn’t the enemy—misaligned debt is. A mortgage with a 30-year term can be a wealth-building tool if the ratio stays above 40%. A credit card balance? Not so much.
- Liquidity matters more than the headline number. A 70% ratio with illiquid assets (e.g., a rental property) is riskier than a 50% ratio with cash and stocks.
- Generational wealth gaps widen when ratios diverge. Families that inherit assets start with a higher ratio baseline; those who don’t must earn their way up.
- The ratio reveals hidden biases. Women, for example, tend to have lower ratios not because they earn less, but because they’re more likely to hold liquid assets (cash, bonds) rather than appreciating ones (real estate, stocks).
- Taxes and inflation are silent ratio killers. A 55% ratio in 2015 might shrink to 40% in 2023 if capital gains taxes or rising costs erode purchasing power.
Where Things Stand Today
Today, the formula of net worth ratio is both more sophisticated and more contested than ever. Fintech platforms like Mint and YNAB have democratized ratio tracking, but their algorithms often oversimplify the picture. Meanwhile, high-net-worth individuals use proprietary models to slice the ratio by asset class—distinguishing between working capital (liquid assets) and sleeping capital (illiquid holdings). The result? A bifurcated system where the ultra-wealthy optimize ratios for tax efficiency, while the middle class struggles with ratios that don’t account for non-financial assets like time or social networks. The biggest shift is in how ratios are used. No longer just a personal metric, it’s now a tool for activism. Wealth inequality advocates cite ratio disparities as proof of systemic failure, while policymakers debate whether to cap debt-to-asset ratios for certain loans. Even central banks are experimenting with ratio-based stress tests to predict economic downturns. The ratio has become a Rorschach test for society’s values—what we measure reveals what we prioritize.
Conclusion
The net worth ratio isn’t a relic of the past; it’s a living, breathing indicator of how wealth is created, destroyed, and redistributed. Its power lies in its simplicity—yet its implications are profound. It exposes the fragility of leverage, the cost of delayed savings, and the generational divide between those who own assets and those who service debt. But here’s the catch: the ratio only tells part of the story. A 65% ratio might look strong on paper, but if the assets are concentrated in a single stock or a volatile market, it’s a house of cards. Conversely, a 40% ratio with diversified, liquid assets could be far more resilient. The future of the ratio depends on how we wield it. Will it remain a passive metric, or will we use it to design systems that reduce inequality? Will we treat it as a personal scorecard, or a collective warning sign? One thing is certain: ignoring it is no longer an option. In an era of algorithmic trading, AI-driven lending, and climate-induced asset volatility, the formula of net worth ratio isn’t just a number. It’s the first domino in a very long chain.Comprehensive FAQs
Q: How often should I calculate my net worth ratio?
Ideally, quarterly—but the frequency depends on your life stage. High-earners in volatile markets (tech, crypto) may track it monthly, while retirees can stretch it to biannually. The key is consistency: sudden drops (e.g., a 15-point decline in 3 months) warrant immediate review.
Q: Does the ratio differ by country? For example, is a 50% ratio "good" in the U.S. but "bad" in Germany?
Yes. Cultural norms and economic structures shape what’s considered healthy. In Germany, where homeownership is rare and pensions are robust, a 30–40% ratio might be typical for retirees. In the U.S., where real estate is a primary wealth driver, ratios above 50% are common—but only if debt is managed. Always compare against local benchmarks, not global averages.
Q: Can a high ratio hide financial trouble?
Absolutely. A 70% ratio with all assets tied to a single business or illiquid property (e.g., a vineyard) is risky. The ratio doesn’t account for concentration risk or liquidity risk. Always cross-check with cash-flow projections and stress-test scenarios (e.g., "What if this asset loses 30% of its value tomorrow?").
Q: How do student loans affect the ratio compared to a mortgage?
Student loans are a ratio killer because they’re non-deductible (in most cases), carry higher interest rates, and don’t appreciate in value. A $50,000 mortgage on a $300,000 home might improve your ratio over time as equity builds. The same $50,000 in student debt? It’s a pure liability that drags down the ratio until repaid. The difference isn’t just mathematical—it’s structural.
Q: Is there a "magic" ratio that guarantees financial security?
No, but ratios above 60% are historically associated with lower stress levels and greater resilience during downturns. The "magic" lies in the trend, not the static number. A ratio that’s steadily climbing (even if it’s 40%) is healthier than one that’s stagnant or declining. Security comes from momentum, not a single threshold.
Q: How do I improve my ratio if I’m stuck in a low-income bracket?
Focus on liability reduction and asset appreciation simultaneously. Pay down high-interest debt aggressively (credit cards, payday loans), then redirect funds to assets that grow faster than inflation (index funds, skills that increase earning potential). Side hustles can boost income, but ensure they contribute to net wealth—not just gross revenue. Community land trusts or co-op housing can also help bypass traditional barriers to asset accumulation.
