
The Complete Overview of Average Retiree Net Worth
The concept of average retiree net worth has evolved from a simple measure of savings to a multifaceted indicator of economic health, generational equity, and policy effectiveness. Historically, retirement wealth was tied to pensions and Social Security, but the shift to defined-contribution plans like 401(k)s has made individual savings the primary determinant. Today, the figure isn’t just about how much money retirees have—it’s about how they access it, protect it, and whether it lasts. For example, a retiree with a high net worth in a high-cost city like New York may face liquidity crises despite paper wealth, while a retiree in Alabama with half that sum might live comfortably on fixed income. The average retiree net worth also reflects broader economic trends. The 2008 financial crisis, for instance, wiped out trillions in household wealth, delaying retirement for many and forcing others into part-time work. Recovery since then has been uneven: those who owned homes or had diversified portfolios rebounded, while renters and low-wage workers lagged. Now, inflation and market volatility in 2022–2023 have introduced new variables. A retiree who retired in 2020 with a net worth of $1.5 million might see that figure drop to $1.2 million by 2024 due to portfolio losses, even if nominal balances haven’t changed. This volatility underscores why average retiree net worth is less a static benchmark and more a dynamic metric tied to macroeconomic conditions.Historical Background and Evolution
Before the 1980s, most retirees relied on two pillars: employer pensions and Social Security. Defined-benefit plans provided guaranteed income, while Social Security replaced about 40% of pre-retirement wages for average earners. This system created a more predictable retiree net worth, as wealth was less dependent on individual savings. By the 1990s, however, corporate America began phasing out pensions in favor of 401(k)s, shifting risk onto employees. The Tax Reform Act of 1986 further accelerated this shift by allowing tax-deferred contributions to IRAs and 401(k)s, making personal savings accounts the new standard. The consequences became clear in the 2010s. The average retiree net worth for boomers peaked around 2019 at $250,000 (median), but the mean ballooned due to stock market gains and home equity. For Gen Xers, however, the picture was grimmer. Many entered retirement with $100,000 or less in retirement accounts, compounded by the Great Recession’s impact on home values and job stability. The Pew Research Center found that 62% of Gen X retirees had no retirement savings at all in 2020, relying entirely on Social Security. This generational divide suggests that the average retiree net worth isn’t just a snapshot—it’s a legacy of policy choices that favored some cohorts over others.Core Mechanisms: How It Works
The average retiree net worth is calculated by aggregating liquid assets (cash, stocks, bonds), illiquid assets (home equity, business interests), and subtracting liabilities (mortgages, loans, medical debt). However, the methodology varies by source. The Federal Reserve’s Survey of Consumer Finances, for example, includes primary residences in net worth calculations, while other studies exclude them to focus on portable wealth. This discrepancy explains why some reports cite $1.2 million as the mean, while others settle on $280,000 as the median—home equity inflates the average, but most retirees can’t access it without selling. Another critical factor is the 4% rule, a guideline suggesting retirees can withdraw 4% of their portfolio annually without depleting funds over 30 years. This rule assumes a balanced portfolio and market returns, but retirees in low-return environments (like 2022) may need to adjust. For instance, a retiree with $1 million under the 4% rule could withdraw $40,000/year, but inflation and healthcare costs often erode this further. The average retiree net worth thus becomes a stress-test for this rule’s viability, especially as life expectancies rise. Those with lower net worths may need to withdraw 6–8% annually, risking depletion within 15–20 years.Key Benefits and Crucial Impact
Understanding the average retiree net worth isn’t just academic—it directly influences financial planning, public policy, and personal expectations. For individuals, it sets a benchmark for whether they’re on track or facing shortfalls. A retiree with $500,000 might breathe easier knowing they’re above the median, while someone with $100,000 may need to adjust spending or seek supplemental income. For policymakers, these figures justify Social Security adjustments, tax incentives for retirement savings, and debates over expanding Medicare eligibility. Even employers use retiree net worth data to design better 401(k) match programs or financial wellness initiatives. The impact extends to societal stability. Retirees with modest net worths who outlive their savings become a burden on public assistance programs, while those with substantial wealth may leave inheritances that perpetuate inequality. The average retiree net worth thus serves as a barometer for economic mobility. Studies show that retirees with $1 million or more are more likely to pass wealth to heirs, while those below $250,000 often see their assets dwindle in later years. This dynamic reinforces the idea that retirement isn’t just a personal milestone—it’s a reflection of systemic fairness."Retirement wealth isn’t a destination; it’s a process shaped by luck, discipline, and the policies of the day. The average retiree net worth tells us less about individuals and more about the rules of the game." — Economic Policy Institute, 2023
Major Advantages
- Financial security benchmark: Provides retirees with a reality check against national averages, helping them adjust budgets or savings strategies.
- Policy advocacy tool: Highlights disparities that justify reforms in Social Security, pension plans, or healthcare access for seniors.
- Investment guidance: Encourages retirees to diversify portfolios based on their net worth tier (e.g., high-net-worth retirees may allocate more to alternative assets).
- Generational planning: Helps younger workers gauge whether their savings trajectories align with future retiree net worth targets.
- Tax optimization: Retirees with higher net worths can leverage strategies like Roth conversions or charitable giving to minimize tax burdens.
- Longevity insurance: Those above the median may afford long-term care insurance, while others rely on Medicaid planning to protect assets.

Comparative Analysis
| Metric | U.S. Average (2024) |
|---|---|
| Median retiree net worth | $280,000 (Fed data) |
| Mean retiree net worth | $1.2 million (inflated by top 10%) |
| Bottom 20% net worth | Negative or <$50,000 |
| Top 10% net worth | $2.5 million+ |
| Home equity contribution | ~40% of total net worth |
Future Trends and Innovations
The average retiree net worth is poised for disruption from three fronts: technology, demographics, and policy. Robo-advisors and AI-driven financial planning tools are already democratizing retirement management, allowing retirees to optimize withdrawals in real time. Meanwhile, cryptocurrency and alternative assets are creeping into portfolios, though their volatility remains a wildcard. For Gen Z and younger millennials, the average retiree net worth may look starkly different—if they can afford to retire at all. Automation and gig work could extend working lifespans, while student debt may delay retirement entirely. Policy shifts will also reshape the landscape. Proposals to raise the Social Security eligibility age or means-test benefits could reduce reliance on personal savings, altering the retiree net worth calculus. Conversely, expanded access to annuities or government-backed retirement accounts might boost median figures. The biggest unknown remains healthcare: if premiums continue rising, even retirees with $1 million could face liquidity crises. The future of average retiree net worth thus hinges on whether society can balance individual responsibility with collective support—especially as the population ages and traditional safety nets strain.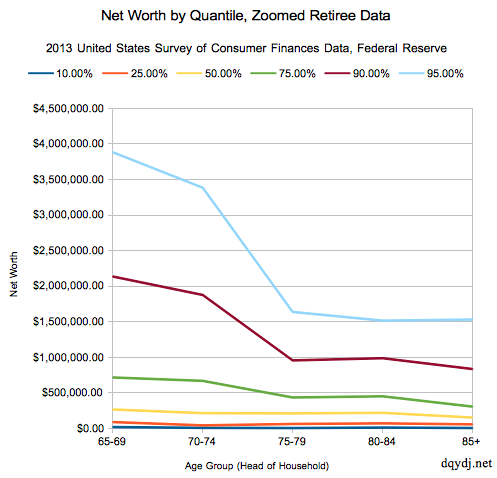
Conclusion
The average retiree net worth is more than a statistic—it’s a mirror reflecting the successes and failures of a lifetime of financial decisions. For those who’ve saved diligently, it’s a measure of security; for others, it’s a stark reminder of systemic barriers. The data reveals that retirement isn’t a uniform experience but a spectrum, where location, health, and timing play as critical a role as savings. As the economy evolves, so too must our understanding of what constitutes a "healthy" retiree net worth—one that accounts for longevity, inflation, and the unpredictable nature of markets. The conversation around retirement wealth must move beyond averages to address equity. If the average retiree net worth continues to favor the already wealthy, the system will perpetuate inequality. Solutions may lie in stronger Social Security guarantees, employer-sponsored retirement plans, or innovative products like longevity insurance. One thing is certain: ignoring the disparities in retiree net worth risks leaving future generations with fewer options—and a retirement that looks nothing like the one boomers enjoyed.Comprehensive FAQs
Q: How does home equity factor into the average retiree net worth?
A: Home equity accounts for roughly 40% of the average retiree net worth, but it’s often illiquid. While it inflates total net worth, retirees can’t easily access it without selling their homes. Policies like reverse mortgages or home equity lines of credit (HELOCs) provide workarounds, but they come with risks like high interest rates or inheritance complications.
Q: Why is the median retiree net worth lower than the mean?
A: The mean ($1.2 million) is skewed by a small percentage of ultra-wealthy retirees, while the median ($280,000) represents the typical retiree. This disparity highlights wealth concentration—most retirees fall below the mean, but a few hold disproportionate assets. The gap underscores why median figures are more reliable for planning.
Q: Can retirees with below-average net worth still retire comfortably?
A: Yes, but it requires careful planning. Retirees with $100,000–$250,000 often live on Social Security plus part-time income, minimal housing costs, or government assistance. Strategies like downsizing, relocating to low-cost areas, or delaying retirement can stretch savings. However, healthcare and unexpected expenses remain major risks.
Q: How does inflation affect the average retiree net worth?
A: Inflation erodes purchasing power, forcing retirees to withdraw more from portfolios to maintain their standard of living. A $500,000 net worth in 2010 might equate to $400,000 in 2024 due to rising costs. Retirees with fixed incomes (e.g., pensions) are hit hardest, while those with diversified portfolios can adjust withdrawals. Long-term care inflation is particularly brutal, often outpacing general price increases.
Q: Are there regional differences in retiree net worth?
A: Dramatically. Retirees in high-cost states like California or New York often have higher net worths but face liquidity challenges due to expenses. In contrast, retirees in Florida, Alabama, or Mississippi may have lower net worths but live comfortably on fixed incomes. Tax policies, housing markets, and healthcare costs vary widely, making average retiree net worth a poor proxy for actual retirement security without location context.
Q: What’s the biggest threat to the average retiree net worth in the next decade?
A: Healthcare costs and market volatility pose the greatest risks. A single year of nursing home care can wipe out a retiree’s savings, while poor market returns early in retirement can force aggressive withdrawals, depleting principal. Demographic shifts—like the aging boomer cohort—will also strain public resources, potentially reducing Social Security benefits or increasing premiums for Medicare.
