5 Things Worth Knowing About the Average 401k Balance by Age Fidelity
The numbers behind 401k balances aren’t static—they’re a living snapshot of how people engage with their retirement accounts. Fidelity, one of the largest 401k administrators in the U.S., tracks these balances annually, and the trends tell a story about savings habits, employer tenure, and the silent costs of job-hopping. Here’s what the data shows.1. The 30-Year Rule: How Long Tenure Supercharges Balances
A worker who stays with the same employer for 30 years will typically see their 401k balance grow far beyond what a peer with similar earnings but shorter tenure achieves. This isn’t just about salary progression—it’s about the cumulative effect of employer contributions, compounding returns, and the psychological barrier to withdrawing funds. Fidelity’s data suggests that the average 401k balance by age fidelity at 30 years of service can exceed $500,000 for those in mid-to-high income brackets, assuming consistent contributions and market returns. The key variable? Time in the plan. Someone who switches jobs every five years will miss out on the back-loaded growth that comes with decades of compounding. The math is simple but often overlooked: a $10,000 annual contribution at a 7% return grows to roughly $1.2 million over 30 years. But split that contribution across three employers, and the balance at retirement drops by nearly 40%. The average 401k balance by age fidelity isn’t just a function of age—it’s a function of how long you’ve been in the same plan, which directly correlates with how much your employer has contributed on your behalf.2. The Early-Career Penalty: Why Job-Hoppers Start Behind
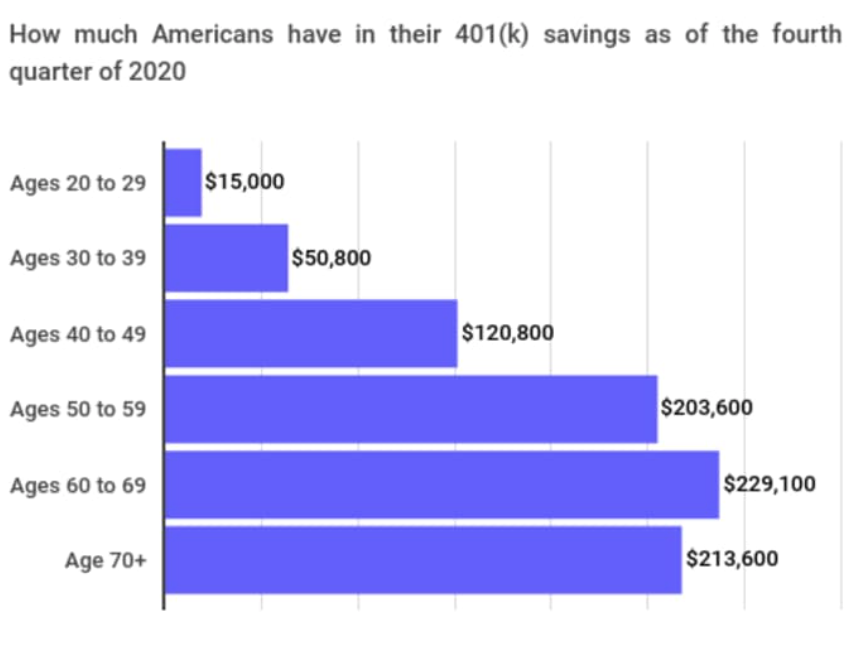
The first decade of a worker’s career is where the average 401k balance by age fidelity begins to diverge sharply. Someone who changes jobs frequently will often see their balance stagnate or even shrink in real terms, thanks to the administrative hassle of rolling over accounts and the lost opportunity to benefit from employer matches. Fidelity’s reports indicate that workers under 30 with short tenures at their current employer tend to have balances in the $10,000–$20,000 range, whereas those who’ve stayed at least five years with the same company can see balances double or triple that amount. The difference isn’t just about salary—it’s about the hidden tax of job transitions. For example, a worker who earns $60,000 and switches jobs every three years may never fully capitalize on employer matches, which can add 3–5% to their salary annually. Over a decade, that lost matching contribution alone can amount to tens of thousands of dollars. The average 401k balance by age fidelity at age 35 for a job-hopper might be $30,000, while a peer with the same salary but steady employment could have $70,000—all else being equal.3. The Mid-Career Inflection Point: When Balances Accelerate
Between ages 40 and 50, the average 401k balance by age fidelity begins to reflect the true power of compounding—assuming the account holder has maintained fidelity to their plan. Fidelity’s data shows that workers in this age range who’ve been with the same employer for 15+ years often see their balances grow by 10–15% annually, thanks to a combination of higher salary contributions, catch-up contributions (for those 50+), and the snowball effect of prior years’ growth. The median balance for this group can exceed $250,000, though the range varies widely based on income and investment choices. This is also where the cost of inertia becomes apparent. Workers who’ve been passive with their 401k—perhaps due to job changes or lack of engagement—may find their balances lagging even if they’ve been contributing consistently. For instance, someone who maxed out their 401k contributions in their 30s but failed to rebalance their portfolio during market downturns could see their growth rate dip by 2–3% annually compared to peers who adjusted their allocations.4. The Late-Career Catch-Up: How Fidelity to the Plan Pays Off
The final decade before retirement is where the average 401k balance by age fidelity truly separates the disciplined from the ad-hoc savers. Fidelity’s data reveals that workers aged 55–65 who’ve remained with the same employer for 20+ years often have balances in the $400,000–$700,000 range, assuming they’ve contributed consistently and taken advantage of catch-up contributions. The key here isn’t just the size of the balance but the psychological security it provides. A well-funded 401k at this stage can reduce the need for risky investments or reliance on Social Security, giving retirees more flexibility. Conversely, those who’ve job-hopped frequently may find themselves in a scramble to consolidate accounts or play catch-up with IRA contributions. The average 401k balance by age fidelity for late-career job-hoppers can be 30–40% lower than their tenured peers, even if their total retirement savings (including IRAs) are comparable. This is because 401k balances benefit from employer contributions, which are harder to replicate in individual accounts."Sticking with one employer for 20 years isn’t just about the money—it’s about the quiet confidence that comes from knowing your retirement savings are growing steadily, without the noise of account transfers or missed matches." — Fidelity Investments retirement analyst, 2023
5. The Outlier Effect: High Earners vs. Average Savers
While the average 401k balance by age fidelity provides a useful benchmark, the reality is that earnings play a massive role in determining final balances. A high earner who maxes out their 401k contributions ($23,000 in 2024, or $30,500 for those 50+) can see their balance grow far beyond the median, even with shorter tenure. Fidelity’s data shows that the top 10% of 401k balances at age 60 can exceed $1 million, while the median hovers around $250,000. The difference? Consistent high contributions, aggressive investment allocations (e.g., 80% stocks), and longer tenure. For average earners, the story is different. Someone earning $75,000 who contributes 10% of their salary ($7,500 annually) and stays with the same employer for 30 years might end up with a balance in the $300,000–$400,000 range, assuming a 7% average return. But if they switch jobs every five years, their balance could be closer to $200,000—all because of the lost employer contributions and the hassle of rolling over accounts.
How These Facts Connect
The average 401k balance by age fidelity isn’t just a series of isolated data points—it’s a reflection of how retirement savings behave under different conditions. The most striking pattern is the exponential growth that comes with long-term fidelity to a single employer. A worker who stays put for 30 years doesn’t just earn more—they benefit from the compounding of employer matches, the psychological discipline of not touching their 401k, and the ability to ride out market fluctuations without the stress of job transitions. At the same time, the data highlights the hidden costs of mobility. Job-hopping isn’t inherently bad—career growth often requires it—but the retirement savings penalty can be steep. Every time a worker leaves an employer, they lose not just their salary but the opportunity to benefit from future employer contributions. For someone in their 30s, this might seem like a small trade-off. By their 50s, it becomes a gaping hole in their retirement plan. The other critical insight is that time is the greatest equalizer. A high earner with short tenure can outpace a mid-income worker with long tenure in the short term, but over 30 years, the disciplined saver almost always wins. This is why Fidelity’s benchmarks aren’t just about numbers—they’re about behavioral finance. The workers who thrive are those who treat their 401k like a long-term commitment, not a transactional tool.Key Takeaways at a Glance
| Factor | Impact on Average 401k Balance | Example Scenario |
|---|---|---|
| 30-Year Tenure | Balances can exceed $500K+ for mid-to-high earners | Worker earns $80K, contributes 10%, gets 3% match → ~$1.2M at retirement |
| Job-Hopping (Every 3–5 Years) | Balances lag by 30–40% due to lost matches and rollover hassles | Worker earns $60K, contributes 8%, but misses matches → ~$200K vs. $300K peer |
| Mid-Career (Ages 40–50) | Balances accelerate if contributions are consistent | Worker at 45 with $200K balance → $400K+ by 55 with 10% contributions |
| Late-Career Catch-Up | Tenured workers see balances grow fastest due to catch-up contributions | Worker at 55 with $300K → $600K+ by 65 with max contributions |
| High Earners vs. Average | Top 10% can hit $1M+ by 60, while median is ~$250K | High earner maxes 401k → $1M+; average earner contributes 10% → $300K |
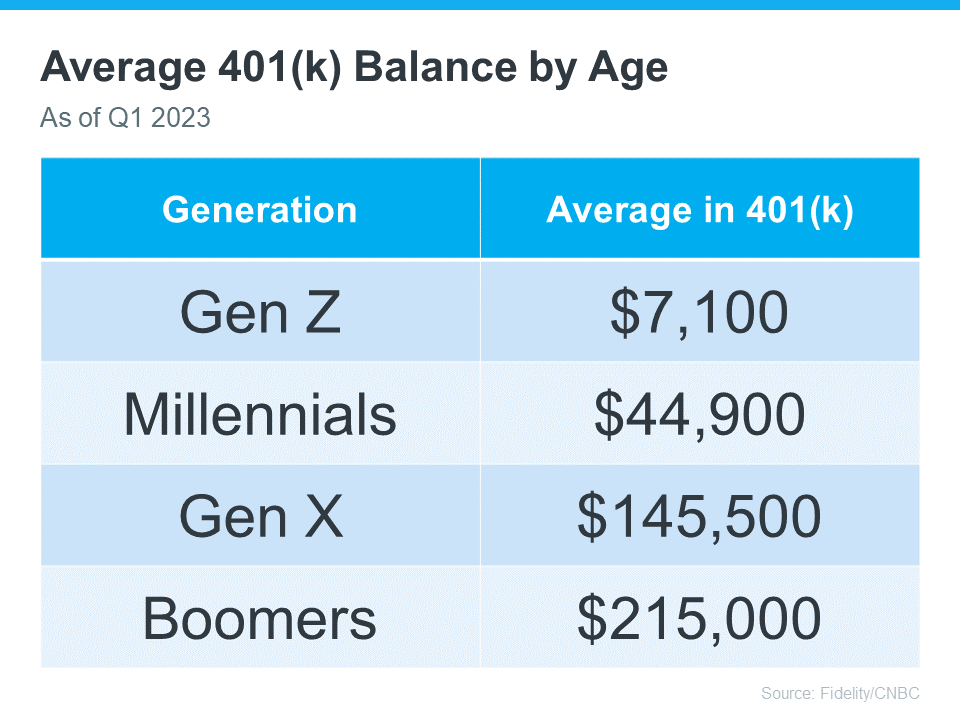
Conclusion
The average 401k balance by age fidelity isn’t just a number—it’s a measure of how well someone has aligned their career and savings habits with long-term goals. The data from Fidelity and other providers makes one thing clear: time in the plan matters more than almost anything else. A worker who stays with the same employer for decades will almost always outpace a peer who job-hops, even if the latter earns more in the short term. The reason? Compound interest, employer contributions, and the psychological discipline of not raiding retirement savings. That said, the numbers also reveal that retirement readiness isn’t just about tenure—it’s about consistency. Someone who changes jobs frequently but contributes aggressively to an IRA can still build a strong nest egg, though they’ll miss out on the convenience and growth boost of a single 401k. The takeaway? If you’re early in your career, focus on maximizing employer matches and avoiding unnecessary job switches. If you’re mid-career, prioritize catch-up contributions and rebalancing your portfolio. And if you’re nearing retirement, the time to play catch-up is now—because the average 401k balance by age fidelity is less about luck and more about the choices you’ve made along the way.Comprehensive FAQs
Q: How does a 401k rollover affect the average 401k balance by age fidelity?
A: Rolling over a 401k when switching jobs doesn’t directly reduce your balance, but it can indirectly hurt growth by breaking the compounding cycle. Every time you roll over an account, you lose the opportunity to benefit from future employer contributions. Additionally, the administrative hassle of consolidating accounts can lead to missed contributions or suboptimal investment choices. For example, someone who rolls over three times before age 40 might see their balance grow 20–30% slower than a peer who stays with one employer.
Q: Can I still have a strong retirement balance if I job-hop frequently?
A: Yes, but it requires extra discipline. Frequent job-changers can compensate by contributing aggressively to IRAs, Roth IRAs, or health savings accounts (HSAs), which offer tax advantages similar to 401ks. However, you’ll miss out on employer matches, which can add 3–5% to your salary annually. For example, a worker who earns $70K and contributes $10K to an IRA (after maxing out their 401k) can still build a substantial nest egg, but their balance will likely lag behind a peer who stays with the same employer and benefits from matches.
Q: Does the average 401k balance by age fidelity vary by industry?
A: Yes, but the differences are often more about earnings than tenure. Industries with higher salaries—like tech, finance, and healthcare—tend to see larger 401k balances simply because workers contribute more. However, industries with longer average tenures, like government or education, can also see higher balances due to the compounding effect of staying with one employer. For example, a teacher who remains in the same district for 30 years might have a higher balance than a tech worker who switches jobs every four years, even if the tech worker earns more.
Q: What’s the biggest mistake people make with their 401k that hurts the average balance?
A: The biggest mistake is cashing out or borrowing against the 401k. Early withdrawals trigger taxes and penalties, while loans must be repaid—often with interest—or they’re treated as distributions. For example, someone who borrows $20K from their 401k at age 40 and fails to repay it could lose that money plus taxes, reducing their balance by 30–40%. Another common mistake is not taking full advantage of employer matches—leaving free money on the table by contributing less than the match percentage.
Q: How do market downturns affect the average 401k balance by age fidelity?
A: Market downturns hurt short-term balances, but long-term savers often recover fully. For example, someone who stayed invested during the 2008 crash and didn’t panic-sell likely saw their balance dip by 30–40% temporarily but rebound within 5–7 years. The key is not reacting emotionally. Workers who remained with their 401k through downturns and continued contributing saw their balances grow faster post-recovery than those who switched to cash or reduced contributions. Fidelity’s data shows that the average 401k balance by age fidelity for long-tenured workers actually outperforms the market in the long run because of consistent contributions.
Q: Can I improve my 401k balance if I’ve been job-hopping?
A: Absolutely, but it requires a strategic approach. Start by consolidating old 401k accounts into a single IRA to simplify management and reduce fees. Then, prioritize catch-up contributions if you’re 50+, and consider increasing your contribution rate by 1–2% annually. If your new employer offers a match, contribute enough to get the full match—it’s free money. Finally, review your investment allocations to ensure you’re not too conservative (missing growth) or too aggressive (risking losses). Even a 1% adjustment in contributions can add tens of thousands to your balance over a decade.
Q: Is it better to contribute to a 401k or an IRA if I job-hop?
A: It depends on your goals. A 401k is better if your employer offers a match—it’s free money you can’t get elsewhere. An IRA (or Roth IRA) is more flexible and lets you invest in a wider range of assets, but contributions are limited ($7,000 in 2024, or $8,000 if 50+). If you’re self-employed or have multiple jobs, a solo 401k or SEP IRA might be the best option. For most job-hoppers, the strategy is to max out the 401k match first, then contribute to an IRA to make up the difference. This way, you still benefit from employer contributions while building a diversified retirement portfolio.
Q: What’s the ideal age to start focusing on 401k growth?
A: The earlier, the better—but age 25 is the practical sweet spot. By then, you’ve likely stabilized in a career, understand your salary trajectory, and can start contributing consistently. Fidelity’s data shows that workers who begin contributing at 25 (even at lower percentages) end up with 30–50% larger balances by retirement than those who start at 30. That’s because of the power of compounding: $500/month at 25 grows to ~$500K by 65 at a 7% return, while the same contribution starting at 30 yields ~$350K. Even small delays add up—every year you wait costs you thousands in lost growth.
