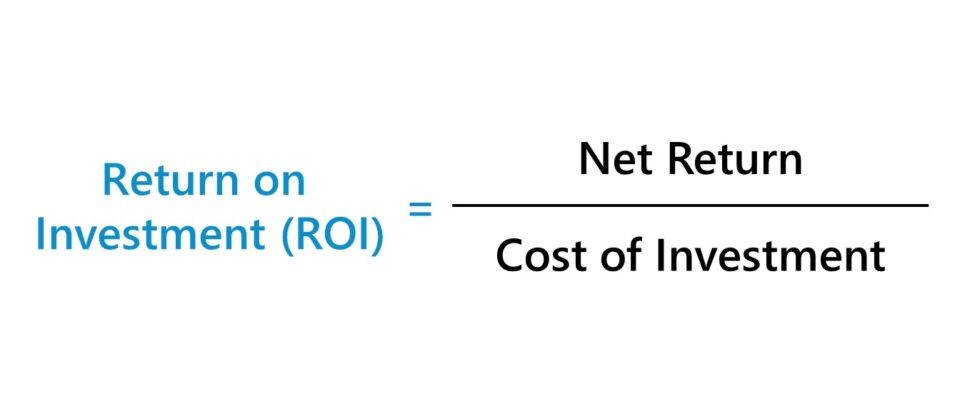
7 Things Worth Knowing About ROI Net Worth
Understanding ROI net worth requires dismantling the myth that wealth is purely quantitative. It’s a philosophy that prioritizes return-on-investment thinking across every asset class, from traditional stocks to human capital. The following insights cut through the noise to reveal how the most sophisticated wealth builders operate.1. ROI Net Worth Isn’t Just About Money—It’s About Time and Effort
Most discussions of net worth fixate on dollar figures, but ROI net worth forces a reckoning with opportunity cost. Time spent managing a business that yields a 15% annual return might be better allocated to an asset generating 30%—even if the latter requires more upfront effort. This is why many HNWIs outsource operational tasks to focus on high-leverage activities: consulting, deal sourcing, or scaling ventures where their expertise directly multiplies returns. The trade-off isn’t just financial; it’s temporal. A CEO who spends 20 hours a week on a side hustle might see their ROI net worth rise faster than if they delegated entirely, but only if that hustle’s marginal return justifies the time. The psychological shift here is critical. Traditional net worth accounting treats all assets as static, but ROI net worth demands an active mindset. It’s not enough to own a property; you must optimize its rental yield, tax benefits, or potential for appreciation. Similarly, a professional’s human capital—skills, network, reputation—must be treated as an asset class with its own return metrics. The gap between passive wealth accumulation and ROI-driven growth often comes down to this: whether you’re tracking numbers or engineering them.2. The Highest ROI Assets Aren’t Always What You Think
The S&P 500 has delivered ~10% annualized returns for decades, making it a cornerstone of diversified portfolios. But for those with ROI net worth in mind, the most lucrative plays often lie in illiquid or alternative assets. Private equity stakes in high-growth startups, for example, can outperform public markets—but they require deep due diligence and patience. Similarly, fractional ownership in luxury assets (yachts, helicopters, vineyards) can generate steady cash flow while preserving liquidity. The key is balancing liquidity risk with return potential. Consider the case of a musician who licenses their catalog to streaming platforms. Their ROI net worth isn’t just the upfront advance; it’s the royalty stream’s longevity, the potential for sync licensing deals, and even the brand’s ability to attract sponsorships. This is where traditional net worth calculations fail: they don’t account for recurring revenue or secondary monetization of assets. The same logic applies to real estate investors who structure properties to capture multiple income streams—rental income, short-term leases, and eventual sale—rather than treating them as one-dimensional holdings.3. Brand Equity Is the Most Undervalued Component of ROI Net Worth
For public figures, entrepreneurs, and even high-level employees, personal brand equity can represent a larger portion of their ROI net worth than their formal assets. A single high-profile endorsement deal or a well-timed media appearance can generate returns far exceeding what a traditional investment might yield. This is why celebrities and influencers meticulously curate their public image—not just for vanity, but because their brand’s market value directly impacts deal flow, speaking fees, and even investment opportunities. The math is straightforward: if a brand’s perceived value increases by 20%, the ROI on associated ventures (merchandise, partnerships, content) rises proportionally. This is why ROI net worth for creators often includes intangibles like audience growth metrics, engagement rates, and monetization potential. A YouTuber with 10 million subscribers might have a brand valuation that dwarfs their direct earnings, especially if they’re positioned for long-term syndication or licensing. The challenge? Quantifying these assets without overinflating their true economic value.4. Tax Optimization Is a Silent Multiplier for ROI Net Worth
The after-tax return on an investment can differ wildly from its pre-tax yield. A ROI net worth strategy must account for tax-efficient structuring, whether through holding companies, offshore trusts, or strategic asset location. For instance, a private equity fund might generate 25% gross returns—but after capital gains taxes, management fees, and carried interest, the net ROI could drop to 12%. The difference isn’t trivial; it’s the margin between mediocrity and exponential growth. High-net-worth families often employ dynamic asset allocation to minimize tax drag. Holding certain assets in tax-advantaged accounts, leveraging loss harvesting, or structuring deals to defer taxable events can boost net returns by 3–5% annually. This is why ROI net worth isn’t just about asset performance; it’s about preserving and enhancing those returns through legal and financial engineering. The most sophisticated players treat tax strategy as an integral part of their investment thesis, not an afterthought.5. The Role of Leverage—When Debt Accelerates ROI Net Worth
Debt is universally feared, but in the context of ROI net worth, it’s often a force multiplier. Mortgages, business loans, and margin debt can amplify returns if the cost of capital is lower than the asset’s expected yield. A real estate investor might take on 70% LTV financing on a property expected to appreciate at 10% annually; their ROI net worth rises not just from equity gains but from the leverage effect on cash-on-cash returns. Similarly, a startup founder might use convertible debt to fund growth, knowing that a successful exit will compound the original investment at a far higher rate than unlevered capital. The catch? Leverage works only if the asset’s ROI exceeds the debt’s cost. A 5% mortgage on a property yielding 8% rental income is a no-brainer; a 10% loan on a volatile asset with uncertain upside becomes a liability. This is why ROI net worth requires dynamic risk assessment—constantly recalibrating the balance between debt exposure and asset performance. The best practitioners treat leverage as a tactical tool, not a crutch.6. The Dark Side: How Over-Optimization Can Destroy ROI Net Worth
Chasing the highest ROI without regard for correlation risk or liquidity constraints is a recipe for disaster. The 2008 financial crisis exposed how overleveraged real estate portfolios collapsed when financing dried up. Similarly, the crypto boom of 2021–2022 revealed how high-ROI assets can become toxic if their underlying markets lack fundamentals. The lesson? ROI net worth isn’t just about maximizing returns; it’s about managing downside risk. Many ultra-wealthy individuals diversify across uncorrelated asset classes—private credit, timberland, fine art—to smooth volatility. Others use hedging strategies, such as short positions or options, to protect against black swan events. The goal isn’t to eliminate risk entirely but to structure the portfolio so that losses in one area don’t cascade into systemic collapse. This is where ROI net worth diverges from traditional wealth management: it’s not just about growth, but resilience."The best investors don’t just chase returns—they design portfolios where the worst-case scenario is still survivable. That’s the difference between a fortune and a flash in the pan." — Ray Dalio, Founder of Bridgewater Associates (paraphrased)
7. The Psychological Barrier: Why Most People Never Calculate ROI Net Worth
The biggest obstacle to ROI net worth isn’t mathematical—it’s behavioral. Most individuals treat wealth as a static number rather than a dynamic system. They focus on what they own rather than how it performs. This mindset leads to suboptimal decisions: holding onto underperforming assets out of emotion, ignoring tax-efficient strategies, or failing to reinvest profits into higher-yielding opportunities. The ROI net worth mindset requires discipline. It means regularly stress-testing assumptions, rebalancing portfolios before emotions take over, and measuring progress not just in dollars but in time-adjusted returns. It’s why the ultra-wealthy often surround themselves with quantitative analysts, tax strategists, and behavioral economists—not just financial advisors. The gap between average net worth and ROI-optimized wealth is rarely about access to capital; it’s about mental frameworks.
How These Facts Connect
The seven principles above don’t operate in isolation; they form a feedback loop that defines ROI net worth as a living, breathing system. The interplay between brand equity and tax optimization, for instance, illustrates how intangible assets can be engineered for higher returns. A musician who structures their catalog under a holding company not only captures more royalties but also reduces taxable income—compounding the ROI on their creative output. Similarly, the leverage dynamic reveals why ROI net worth thrives in high-growth environments but falters in stagnant ones. When interest rates are low, debt becomes a wealth accelerator; when markets turn, it becomes a liability multiplier. The same applies to brand risk: a celebrity’s ROI net worth can evaporate overnight if their public image is damaged, yet if managed well, it can outperform traditional investments for decades. The table below distills these connections into five core pillars of ROI net worth strategy:| Pillar | Key Driver | Risk Factor | Example | ROI Impact |
|---|---|---|---|---|
| Asset Selection | High-growth, illiquid, or alternative assets | Liquidity risk, valuation uncertainty | Private equity in AI startups | Potential 20–50%+ annualized returns |
| Brand & Human Capital | Monetizable reputation, audience, IP | Market saturation, relevance decay | Influencer sponsorships, licensing deals | Recurring revenue streams |
| Tax & Structural Efficiency | Offshore entities, holding companies | Regulatory changes, compliance costs | Carried interest in private funds | 3–8% net return preservation |
| Leverage & Capital Structure | Debt at rates below asset ROI | Interest rate spikes, asset depreciation | Mortgages on rental properties | 2–5x equity growth potential |
| Psychological Discipline | Regular rebalancing, risk management | Emotional decision-making | Dollar-cost averaging in volatile markets | Consistent outperformance over time |

Conclusion
The shift toward ROI net worth reflects a broader evolution in how wealth is measured. No longer is it sufficient to ask, "How much do I have?"—the real question is, "How efficiently is my wealth generating more wealth?" This mindset isn’t limited to the ultra-rich; it’s a framework that can be applied at any income level, from the freelancer optimizing side income to the executive structuring stock options for maximum after-tax gain. The most powerful takeaway? ROI net worth turns passive investing into active wealth engineering. It’s the difference between letting money sit in a savings account and deploying it in ways that compound exponentially. The barriers to entry aren’t financial; they’re educational and psychological. Those who master this approach don’t just build wealth—they accelerate it.Comprehensive FAQs
Q: How do I calculate my ROI net worth?
A: Start by listing all assets (cash, investments, real estate, business equity) and liabilities. Then, assign a return metric to each: rental yield for properties, dividend yield for stocks, or projected growth for private ventures. Sum the after-tax, time-adjusted returns across all assets to derive your ROI net worth. Tools like YNAB or Wealthfront can help, but for precision, consult a quantitative financial advisor.
Q: Can ROI net worth be negative?
A: Yes. If your liabilities (debts, losses) exceed the total returns generated by your assets, your ROI net worth can be negative. This often happens with overleveraged real estate portfolios, underperforming businesses, or high-maintenance assets (e.g., a yacht with high storage/insurance costs). The goal is to restructure such that assets outperform their associated costs.
Q: Is ROI net worth only for the wealthy?
A: No. While the concept is most visible among HNWIs, the principles apply at any scale. A freelancer tracking client acquisition costs vs. revenue per project, a small business owner comparing inventory turnover to profit margins, or a saver comparing high-yield savings rates to inflation are all engaging in ROI net worth thinking. The difference is granularity—not access.
Q: How often should I review my ROI net worth?
A: At minimum, quarterly. High-frequency traders and venture capitalists may adjust weekly, but most individuals should reassess seasonally to account for market shifts, tax changes, or personal goal adjustments. Automated tracking tools (like Personal Capital) can simplify this, but manual reviews ensure no asset is overlooked.
Q: What’s the biggest mistake people make with ROI net worth?
A: Ignoring opportunity cost. Many focus on absolute returns (e.g., "This stock grew 20%") but overlook what that capital could have earned elsewhere. Time spent managing a low-ROI asset is time not spent on a higher-yielding opportunity. The fix? Prioritize assets with the best risk-adjusted returns and exit underperformers quickly.
Q: Can intangible assets (like a personal brand) be part of ROI net worth?
A: Absolutely. For creators, executives, and public figures, brand equity is often the highest-ROI asset in their portfolio. Assigning a monetizable value (e.g., estimated earnings from sponsorships, speaking fees, or licensing) and tracking its growth rate is essential. Tools like Brand Finance or Celebrity Net Worth provide benchmarks, but a customized valuation (by a brand strategist) is ideal.
Q: How does inflation affect ROI net worth?
A: Inflation erodes real returns, meaning a 10% nominal gain might only be 5% in inflation-adjusted terms. ROI net worth strategies must account for this by:
- Investing in inflation-resistant assets (real estate, commodities, TIPS).
- Structuring long-term leases or contracts to lock in pricing power.
- Using hedging instruments (e.g., inflation-protected securities).
Q: Is ROI net worth the same as net worth?
A: No. Net worth is a static snapshot (assets minus liabilities), while ROI net worth is a dynamic calculation (assets’ return-generating capacity minus liabilities’ cost drag). The former tells you what you have; the latter tells you how efficiently you’re growing it. Think of it as the difference between a balance sheet and a profit-and-loss statement.
