
The Complete Overview of return on equity vs return on net worth
Return on equity (ROE) is the metric that built modern capitalism. It distills a company’s profitability relative to shareholders’ equity into a single percentage, making it the gold standard for comparing firms across industries. But ROE’s focus on equity—capital contributed by shareholders plus retained earnings—ignores the broader financial picture. When a corporation borrows heavily to fund growth, its ROE can skyrocket, even as its debt-to-equity ratio becomes unsustainable. This is where return on net worth enters the frame, offering a holistic view that accounts for all assets and liabilities, not just those tied to equity. The distinction becomes sharper at the individual level. A hedge fund manager might report a 15% ROE on her fund’s assets, but her personal return on net worth could be negative if her compensation is tied to performance fees that deplete her liquidity. The disconnect stems from a critical difference: ROE is a forward-looking metric for capital allocation, while return on net worth is a backward-looking audit of wealth preservation. One answers the question How efficiently are we deploying capital? The other asks What have we actually retained?Historical Background and Evolution
The roots of ROE trace back to 19th-century accounting practices, where industrialists sought to quantify how effectively capital was being used in manufacturing. By the 1930s, as corporations grew more complex, ROE became a tool for regulators and investors to assess financial health during the Great Depression. Its rise coincided with the expansion of equity markets, where public companies needed a standardized way to signal performance to distant shareholders. The metric’s dominance was cemented in the post-WWII era, as institutional investors adopted it as a key benchmark for portfolio construction. Return on net worth, by contrast, emerged from the shadows of personal finance and family wealth management. In the 1980s, as tax laws incentivized leveraged buyouts and real estate speculation, ultra-wealthy families began tracking net worth—not just as a balance sheet figure, but as a dynamic metric tied to lifestyle preservation. The term gained traction in the 1990s among private bankers serving high-net-worth individuals, who realized that ROE alone couldn’t explain why some billionaires saw their fortunes shrink even as their companies’ profits grew. The return on equity vs return on net worth debate thus became less about corporate strategy and more about personal financial resilience.Core Mechanisms: How It Works
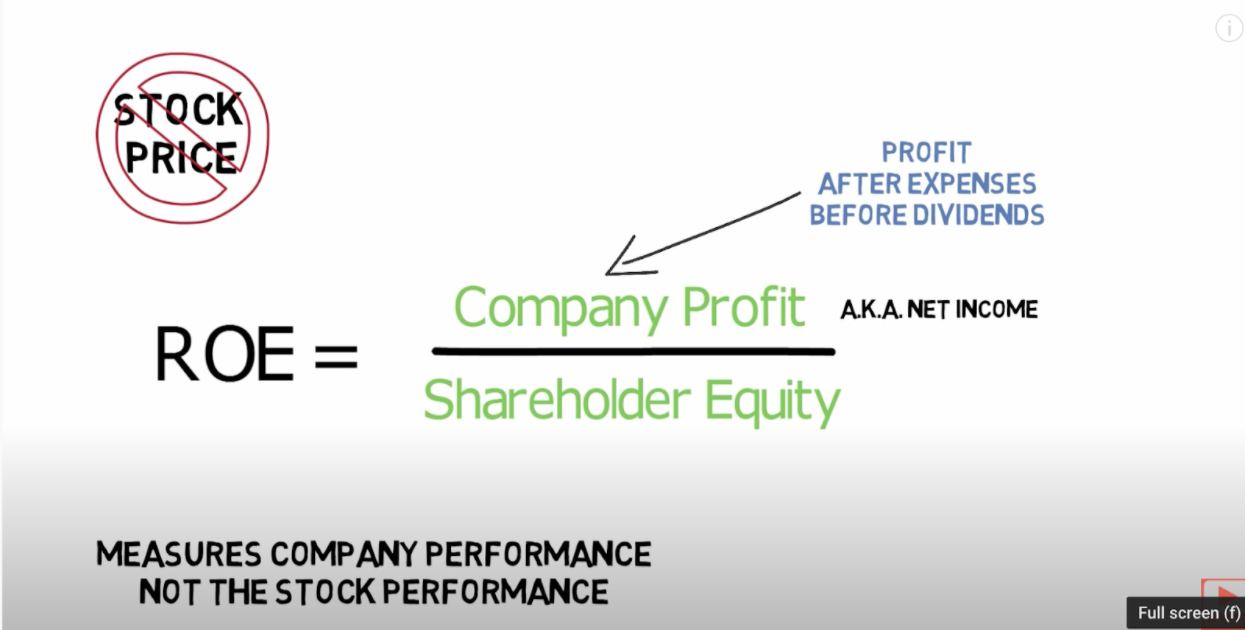
ROE is calculated by dividing net income by shareholders’ equity: (Net Income / Shareholders’ Equity) × 100. The formula is deceptively simple, but its power lies in its ability to reveal how much profit a company generates with the money shareholders have invested. A high ROE suggests efficient capital use, while a low ROE may indicate underperformance—or excessive debt masking true profitability. The metric is particularly sensitive to financial leverage; a company with high debt can inflate its ROE artificially, creating a false sense of outperformance. Return on net worth, however, expands the denominator to include all assets minus all liabilities. For an individual, it might look like this: (Annual Income + Capital Gains – Living Expenses) / Net Worth × 100. The key difference is that it accounts for non-equity assets—such as real estate held personally, private business stakes not listed on a balance sheet, or illiquid investments like art or collectibles. This makes it far more volatile than ROE, as net worth can fluctuate wildly with market conditions or personal spending habits. Where ROE is a snapshot of corporate efficiency, return on net worth is a real-time stress test of wealth sustainability.Key Benefits and Crucial Impact
The obsession with ROE has shaped modern finance, but its limitations are becoming glaring. Consider the case of a tech startup that raises $100 million in venture capital, deploys it into R&D, and achieves a 30% ROE—yet its founders’ personal net worth plummets because the company’s valuation is tied to future revenue, not current profitability. Here, ROE tells an optimistic story, while return on net worth reveals the harsh reality of illiquidity. The two metrics don’t just differ; they often contradict each other, forcing investors to choose between the promise of growth and the certainty of preserved capital. This tension is why private equity firms now supplement ROE with return on invested capital (ROIC) and economic value added (EVA), metrics that bridge the gap between corporate performance and personal wealth outcomes. Yet for individuals, the choice remains stark: chase the high ROE of leveraged bets, or prioritize the steadier (if less glamorous) return on net worth. The former rewards risk-takers; the latter rewards preservers. The distinction explains why some entrepreneurs build empires only to see their personal fortunes vanish, while others quietly accumulate wealth through conservative, net-worth-focused strategies."ROE is the language of the market. Return on net worth is the language of legacy." — James Altucher, financial writer and former hedge fund manager
Major Advantages
- ROE’s clarity makes it ideal for public markets, where transparency is non-negotiable. Investors can compare companies across sectors with a single metric, reducing information asymmetry.
- Return on net worth accounts for personal risk tolerance, revealing how much wealth is truly accessible without liquidating assets—a critical factor for retirees or those with lifestyle dependencies.
- ROE ignores off-balance-sheet liabilities, which can distort true financial health (e.g., a company with high pension obligations may report strong ROE while facing solvency risks).
- Return on net worth adapts to illiquid assets, providing a more accurate picture for individuals with significant holdings in private businesses, real estate, or collectibles.
- While ROE is static (based on historical financials), return on net worth is dynamic, reflecting real-time changes in spending, market conditions, and asset valuations.
Comparative Analysis
| Metric | Key Focus | |
|---|---|---|
| Return on Equity (ROE) | Profitability relative to shareholders’ equity; leverages financial statements. | |
| Return on Net Worth (RONW) | Wealth growth relative to total assets minus liabilities; includes personal and private assets. | |
| Primary Use Case | Corporate valuation, public investing, M&A due diligence. | Personal wealth management, family offices, ultra-high-net-worth planning. |
| Sensitivity to Leverage | Highly sensitive—debt inflates ROE artificially. | Less sensitive unless debt erodes liquidity or asset values. |
Future Trends and Innovations
As artificial intelligence reshapes financial modeling, ROE may soon be augmented by predictive analytics that simulate how changes in debt, taxes, or regulatory environments could alter true economic returns. For individuals, the rise of robo-advisors for net worth optimization suggests that return on net worth could become as mainstream as ROE—though adoption will hinge on whether platforms can accurately model illiquid assets. The biggest shift may come from ESG (Environmental, Social, and Governance) investing, where return on net worth could incorporate non-financial metrics like carbon footprint or social impact, forcing a redefinition of what "wealth" entails. The return on equity vs return on net worth divide may also blur as more high-net-worth individuals incorporate corporate structures into their personal finances. Private equity firms already use holding companies to optimize tax efficiency, and as wealth management becomes more sophisticated, the lines between personal and corporate financial metrics will continue to fade. The result? A future where investors no longer choose between ROE and return on net worth, but instead demand a unified metric that reconciles both perspectives.
Conclusion
The debate over return on equity vs return on net worth isn’t about which metric is superior—it’s about recognizing that they answer different questions. ROE remains the backbone of corporate finance, a tool honed over centuries to evaluate how well capital is deployed. Return on net worth, though less formalized, offers a brutally honest assessment of what’s actually left after the dust settles. The tension between the two reflects a deeper truth: finance is not monolithic. It’s a discipline of trade-offs, where the pursuit of high returns often comes at the expense of wealth preservation—and vice versa. For corporations, the challenge is aligning ROE with sustainable growth. For individuals, it’s ensuring that the metrics driving their investments don’t obscure the reality of their net worth. The solution may lie not in abandoning either metric, but in using them together—ROE to guide capital allocation, and return on net worth to guard against the silent erosion of wealth. In an era of unprecedented market volatility, that dual lens may be the only way to navigate the future.Comprehensive FAQs
Q: Can return on net worth be negative even if ROE is positive?
A: Absolutely. A company might report a strong ROE due to high profits relative to equity, but if its debt obligations or operational costs exceed its cash flow, the owners’ net worth could decline. For example, a leveraged buyout that boosts ROE might leave the acquirer’s personal net worth depleted if the business struggles to service debt.
Q: How do family offices use return on net worth differently than corporations?
A: Family offices prioritize liquidity-adjusted returns, meaning they factor in how easily assets can be converted to cash without triggering capital gains taxes or disrupting long-term strategies. Unlike corporations, which focus on ROE for shareholder returns, family offices often optimize for intergenerational wealth transfer, where preserving net worth outweighs short-term ROE gains.
Q: Are there industries where return on net worth is more important than ROE?
A: Yes. Industries with high fixed costs (e.g., real estate, shipping) or significant off-balance-sheet risks (e.g., private equity, hedge funds) often see a wider gap between ROE and return on net worth. For instance, a shipping magnate might report strong ROE on vessel operations, but if fuel costs or regulatory changes erode asset values, their personal net worth could suffer disproportionately.
Q: Can an individual improve their return on net worth without affecting ROE?
A: Yes, through non-equity wealth strategies. Reducing discretionary spending, diversifying into low-tax assets (e.g., municipal bonds, certain trusts), or holding illiquid assets (e.g., farmland, vintage wine) can boost net worth without altering a company’s ROE. The key is focusing on wealth accumulation rather than profitability metrics.
Q: Why don’t more public companies disclose return on net worth?
A: Because it’s not a standardized financial metric. Net worth for a corporation would require disclosing all assets and liabilities—including private holdings, executive perks, and non-operational investments—many of which are considered proprietary or irrelevant to shareholders. Unlike ROE, which is derived from audited financials, return on net worth would introduce subjectivity and potential legal risks.
Q: What’s the biggest misconception about comparing ROE and return on net worth?
A: The assumption that one is "better" than the other. ROE is a corporate efficiency metric; return on net worth is a personal wealth metric. Chasing high ROE without regard for net worth can lead to financial ruin, while fixating solely on net worth may stifle growth. The optimal approach is to align them—using ROE to guide investment decisions while ensuring those decisions don’t compromise long-term net worth.
