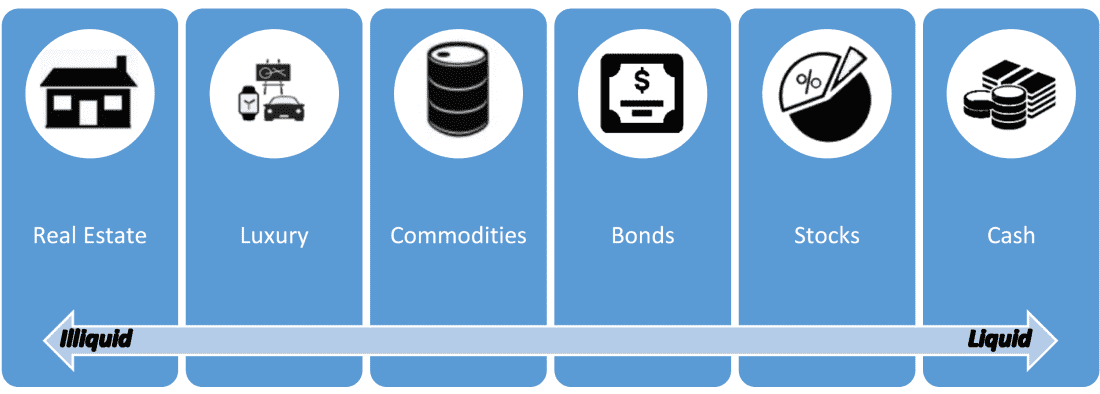
Common Myths About liquid vs illiquid assets
The first misconception is that liquidity is synonymous with safety. Not all liquid assets are risk-free; in fact, some of the most liquid instruments—like short-term corporate debt or leveraged ETFs—carry hidden volatility. During the 2008 financial crisis, money market funds, once considered the safest of liquid investments, saw redemptions surge as underlying assets lost value. The SEC later revealed that some funds held Lehman Brothers paper worthless overnight, yet investors assumed they could withdraw funds at par. Another persistent myth frames illiquid assets as inherently speculative. While private equity or real estate syndications do involve higher risk, they also provide structural protections that public markets lack. For example, a well-structured commercial real estate loan might offer 6–8% yields with principal repayment schedules, whereas a dividend stock yielding 4% could be slashed by a single earnings miss. The key difference? Illiquid assets often let investors lock in returns over time, insulating them from short-term market noise.Myth 1: "All liquid assets are equally easy to sell"
The reality is that liquidity isn’t a uniform trait—it’s a sliding scale. Even "liquid" assets like small-cap stocks or thinly traded ETFs can suffer from slippage, where the act of selling depresses the price. In 2021, the meme-stock frenzy saw retail investors pile into GameStop, only to face liquidity traps when they tried to exit. Bid-ask spreads widened to 20% or more, trapping early buyers. Meanwhile, institutional traders with access to dark pools could unload positions without moving the market—highlighting how liquidity privileges often favor those with scale. The deeper issue is opportunity cost. Selling a liquid asset quickly might seem ideal, but it can force investors into suboptimal tax brackets or trigger capital gains taxes prematurely. A better framework is to ask: What’s the true cost of liquidity? For a hedge fund, that might mean higher management fees to hold cash reserves. For a family office, it could mean foregoing a 12% IRR on a private deal to maintain a 30-day exit window.Myth 2: "Illiquid assets are only for the ultra-wealthy"
While private equity funds typically require $250,000 minimum investments, illiquid assets span a broader spectrum. Farmland, for instance, can be purchased in parcels as small as $50,000 through platforms like AcreTrader, offering 10–12% annualized returns with no correlation to stocks. Similarly, fractional ownership in art or collectibles—via companies like Masterworks—allows investors to access blue-chip assets like Picasso paintings with as little as $20,000. The barrier isn’t wealth; it’s access. The real exclusionary factor is knowledge. Illiquid markets often lack transparency, forcing investors to rely on sponsors’ track records rather than public filings. This asymmetry creates a Catch-22: without experience, it’s hard to evaluate deals, yet without capital, it’s hard to gain experience. The solution? Start small. Platforms like Fundrise or Yieldstreet offer diversified real estate and credit portfolios with minimum investments as low as $500, democratizing exposure to traditionally illiquid asset classes.Myth 3: "Liquidity always comes at the expense of returns"
This is the most dangerous oversimplification. The data shows that the relationship between liquidity and returns is context-dependent. A study by Credit Suisse found that from 1990 to 2020, the S&P 500 (a liquid asset) delivered ~9.5% annualized returns, while private equity (illiquid) returned ~13%. However, the same study noted that publicly traded REITs—which are highly liquid—outperformed private real estate by 2–3% annually. The distinction? Structural efficiency. Liquidity premiums vanish when illiquid assets are structured to mitigate information gaps or alignment problems. Consider gold. As a physical commodity, gold is illiquid—selling a 400-ounce bar requires finding a buyer willing to pay the premium for bulk. Yet, gold ETFs (like GLD) trade with the liquidity of stocks, offering the same exposure without storage costs. The lesson? Liquidity is a feature, not a fundamental trait of an asset class. It’s about packaging. A liquid wrapper can turn an illiquid asset into one that trades like a stock, but at a cost—usually higher fees or diluted upside.
What Holds Up to Scrutiny
At its core, the liquid vs illiquid assets debate hinges on two verifiable truths: 1. Liquidity is a spectrum, not a binary state. Even cash isn’t perfectly liquid—witness the 2020 bank runs on Silicon Valley Bank, where depositors with "liquid" accounts faced delays retrieving funds. 2. Illiquidity can be a feature, not a bug. The endowment model popularized by Harvard and Yale allocates 40–50% of assets to illiquid holdings (private equity, venture capital, real estate) precisely because these assets deliver higher risk-adjusted returns over long horizons. The evidence supports this: a 2022 paper by the National Bureau of Economic Research analyzed 1,000+ pension funds and found that those with 10–20% illiquid allocations outperformed peers by 1.2% annually, adjusting for risk. The catch? This requires time and discipline. Illiquid assets demand a 5–10 year holding period to realize their potential, making them unsuitable for short-term traders or those needing emergency access to capital."Liquidity is not just about selling quickly—it’s about selling without consequences. The best investors don’t chase liquidity; they structure their portfolios to balance access to cash with the ability to compound returns over time." — Barry Sternlicht, founder of Starwood Capital (as quoted in The New York Times, 2019)
| Common Belief | What the Evidence Says |
|---|---|
| "Cash is the most liquid asset." | Cash is highly liquid in normal markets, but during crises (e.g., 2008, 2020), banks impose withdrawal limits or freeze accounts. Physical cash is also vulnerable to theft or inflation erosion. |
| "Illiquid assets are always higher-risk." | While some illiquid assets (e.g., distressed debt) carry higher risk, others (e.g., stabilized commercial real estate) offer predictable cash flows with lower volatility than public equities. |
| "ETFs are always liquid." | Most ETFs trade with minimal slippage, but leveraged or inverse ETFs suffer from compounding decay, and thinly traded ETFs (e.g., niche sectors) can have wide bid-ask spreads. |
| "Private equity delivers outsized returns with no downside." | Private equity does outperform public markets long-term, but illiquidity penalties (e.g., 1–2% annual fees) and J-curve effects (early losses before distributions) can erode gains for smaller investors. |
| "Real estate is illiquid by definition." | While single-family homes are illiquid, REITs and public non-traded REITs offer liquidity at the cost of lower control. Even private real estate can be liquid via 1031 exchanges or fractional platforms. |
Why the Confusion Persists
The primary reason for persistent confusion is behavioral economics. Humans are wired to prefer immediate gratification, and liquidity delivers that—even if it comes at the expense of long-term growth. Financial advisors often reinforce this bias by framing illiquid assets as "speculative," while liquid assets are marketed as "safe." The result? A portfolio tilted toward short-term flexibility, even when the investor’s goals (e.g., retirement, legacy building) demand illiquidity. Another factor is asymmetry in information. Retail investors have access to liquid markets through apps like Robinhood, but illiquid markets remain opaque, controlled by institutions with private deal flows. This creates a feedback loop: because illiquid assets are harder to evaluate, fewer retail investors participate, reinforcing the myth that they’re only for the elite. The truth? Tools like automated fractional ownership platforms are slowly democratizing access—but the learning curve remains steep.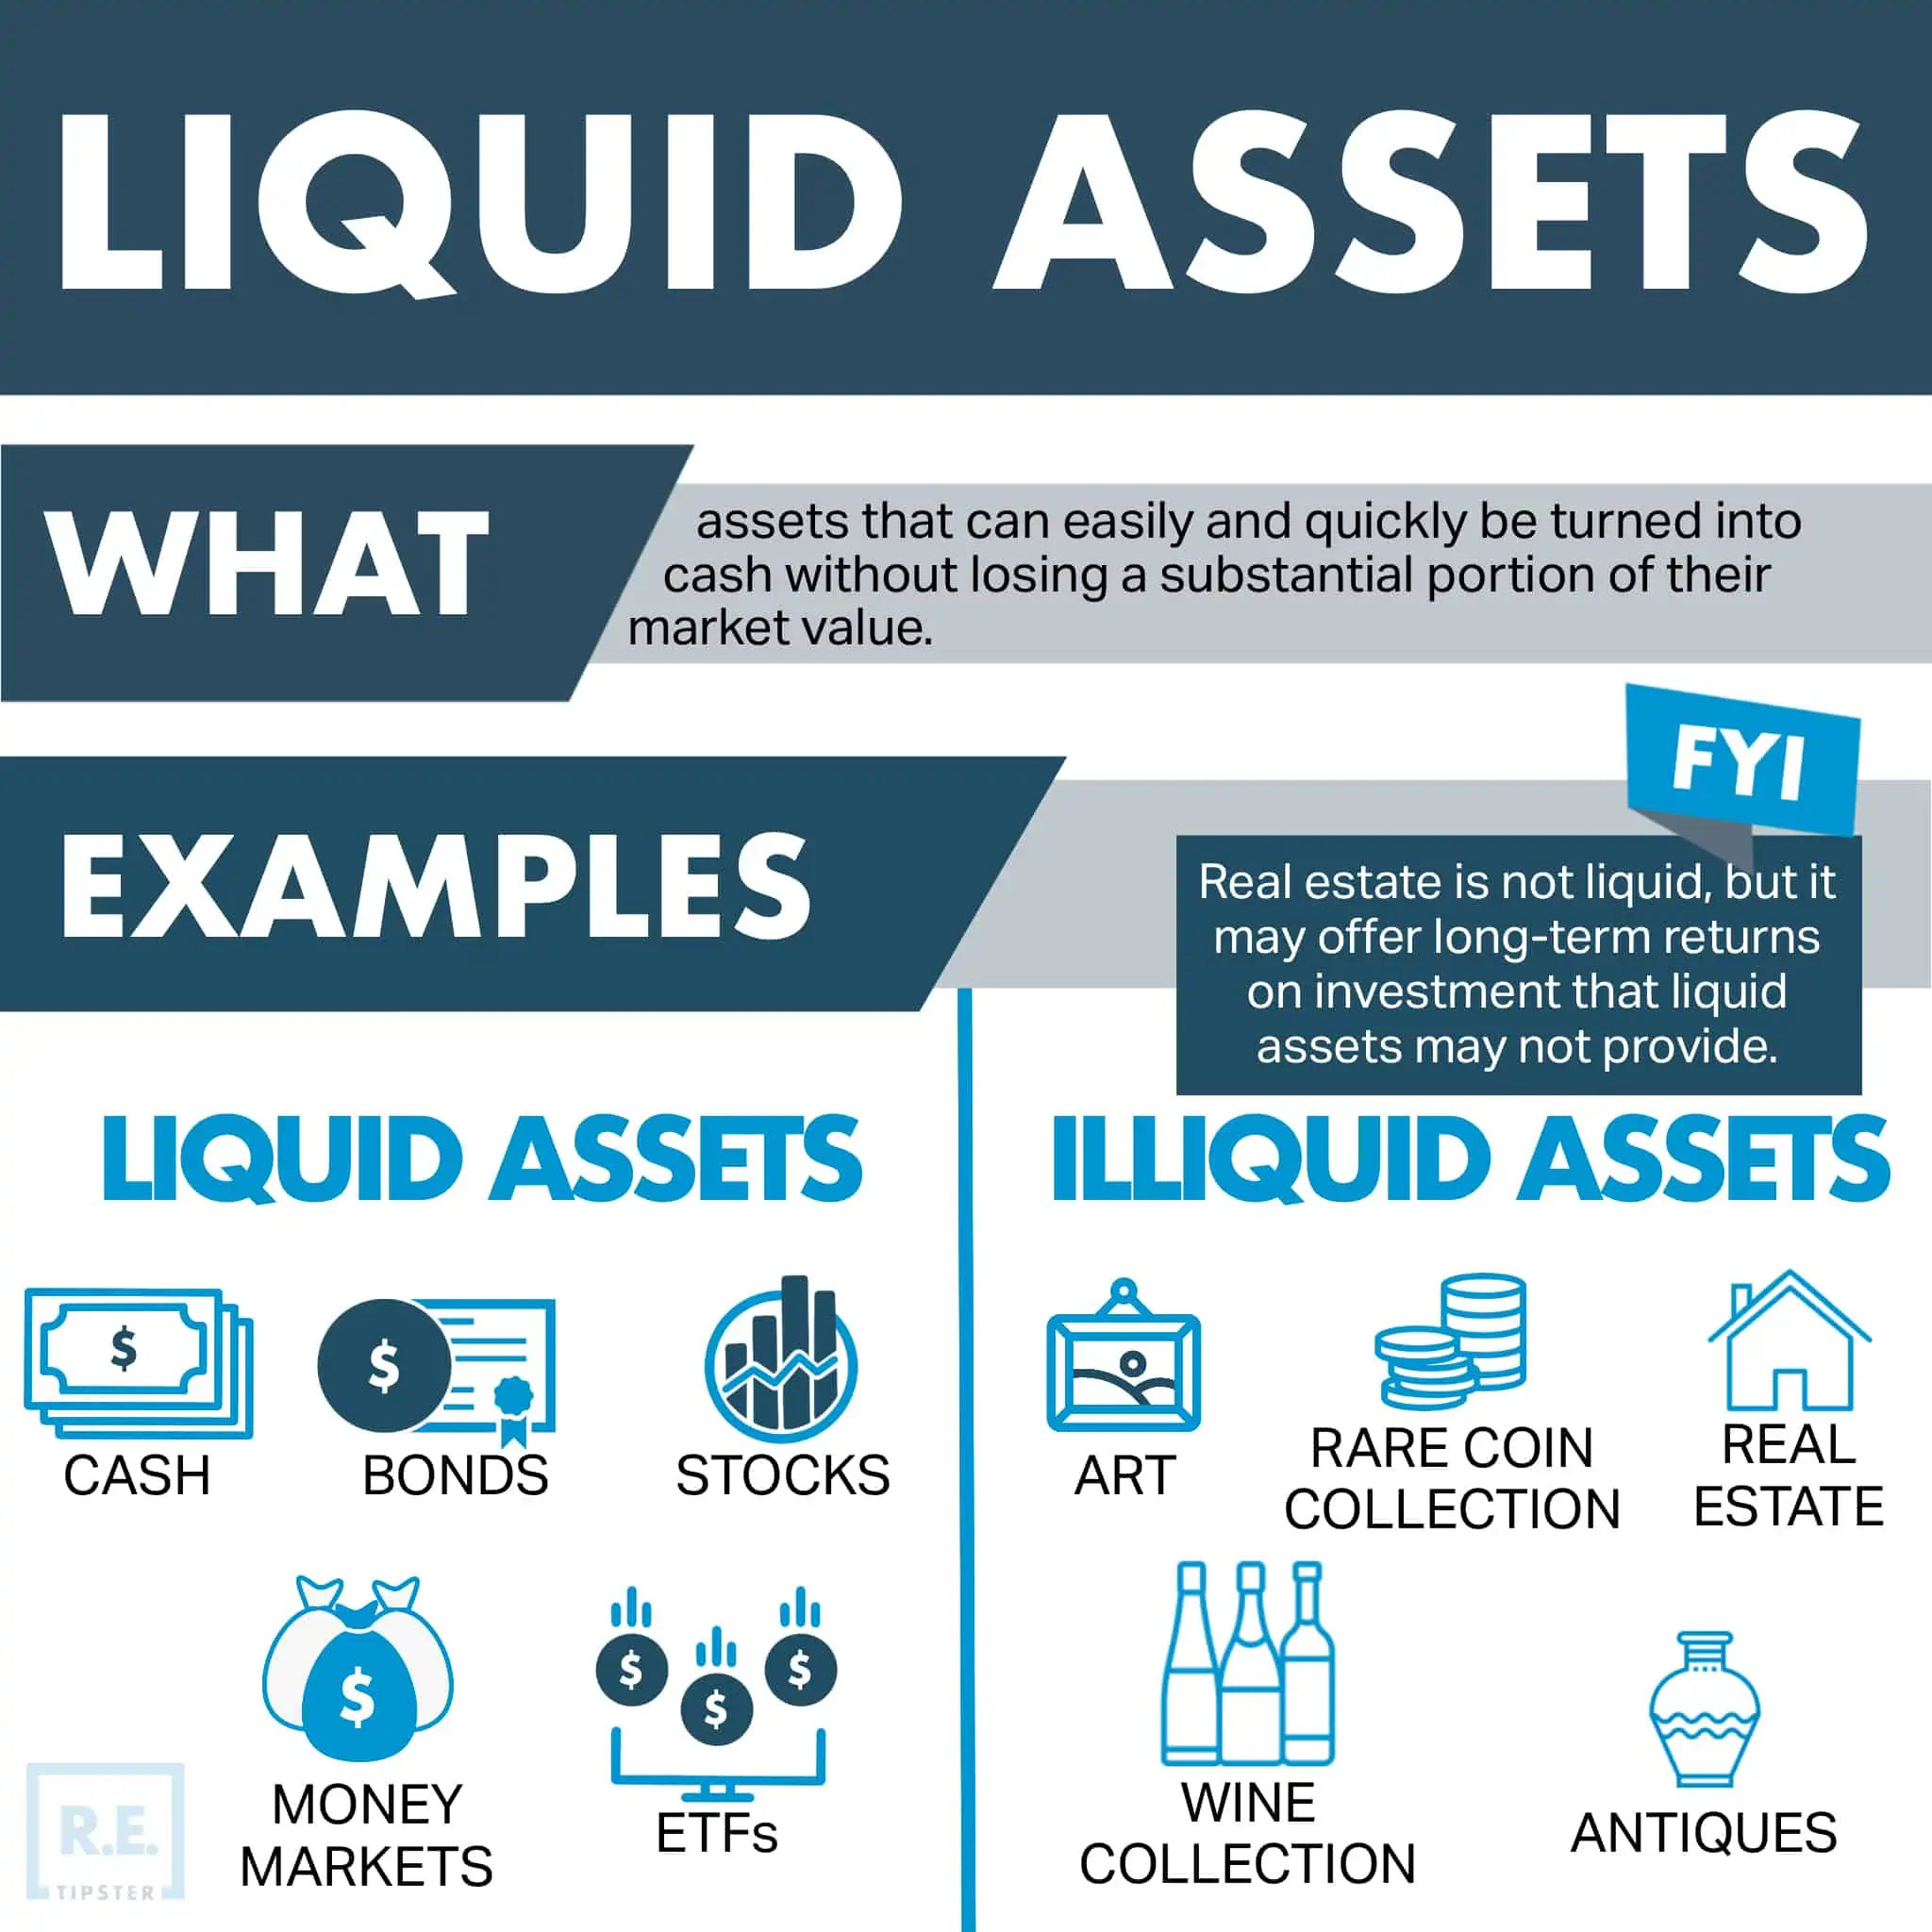
Conclusion
The liquid vs illiquid assets divide isn’t about choosing one side over the other. It’s about designing a portfolio that matches your time horizon, risk tolerance, and liquidity needs. A 25-year-old tech worker can afford to allocate 30% of their portfolio to illiquid venture capital, while a 60-year-old retiree might cap illiquid exposure at 5% to avoid forced sales in a downturn. The critical step is auditing your own constraints: How quickly do you need access to capital? What’s your tolerance for volatility? Only then can you allocate assets intelligently. The future of asset liquidity will likely see more hybrid structures—publicly traded private assets (like SPACs or direct-listing IPOs), tokenized real estate, and algorithmic market-making for alternative investments. These innovations could blur the lines further, but the fundamental trade-offs will remain: speed vs. yield, certainty vs. upside, control vs. convenience. The investors who thrive will be those who stop treating liquidity as a checkbox and start treating it as a strategic lever.Comprehensive FAQs
Q: Can I hold illiquid assets in a tax-advantaged account like an IRA?
A: Yes, but with restrictions. Traditional and Roth IRAs allow illiquid assets like private equity, real estate, or collectibles. However, self-directed IRAs (SDIRAs) are required for non-public investments, and prohibited transactions (e.g., using IRA funds for personal use) can trigger penalties. Consult a CPA familiar with alternative investments.
Q: How do I know if an illiquid asset is a good fit for my portfolio?
A: Ask three questions: 1. Time horizon: Can you hold this for 5+ years without needing liquidity? 2. Diversification: Does this asset class move independently of your liquid holdings (e.g., stocks, bonds)? 3. Sponsor track record: For private deals, verify the general partner’s (GP’s) history of distributions to investors, not just management fees. Start with fractional platforms (e.g., Fundrise, RealtyMogul) to test the waters before committing larger sums.
Q: What’s the biggest mistake investors make when mixing liquid and illiquid assets?
A: Overconcentrating in illiquid assets during market downturns. When public markets crash, illiquid assets can’t be sold to rebalance, forcing investors to hold losing positions. A rule of thumb: Never let illiquid holdings exceed 20–30% of your total portfolio unless you have a dedicated emergency liquidity buffer (e.g., 12–24 months of expenses in cash or cash equivalents).
Q: Are there any illiquid assets that behave like liquid ones?
A: Yes, but with caveats: - Publicly traded REITs (e.g., VICI, O) offer liquidity similar to stocks, though they may underperform private real estate. - Direct-listing IPOs (e.g., Spotify, Slack) allow early investors to exit faster than traditional VC-backed companies. - Tokenized assets (e.g., tBills on Blockchain.com, real estate on RealT) use smart contracts to mimic liquidity, though regulatory risks remain. The trade-off? Higher fees or diluted ownership in the liquid wrapper.
Q: How do I value an illiquid asset if I need to sell it early?
A: Illiquid assets are typically valued using one of three methods: 1. Discounted Cash Flow (DCF): Projects future income streams (e.g., rental yields, dividend growth) and discounts them to present value. 2. Comparable Sales: Looks at recent transactions of similar assets (e.g., selling a 10% stake in a biotech startup at a 3x revenue multiple). 3. Liquidity Discount: Applies a 20–50% haircut to the "fair market value" to account for the difficulty of selling. For forced sales, auction platforms (e.g., Artfinder for collectibles, BizBuySell for businesses) can provide a floor price, but expect to sell below "true value."
Q: Can illiquid assets protect me during a recession?
A: Sometimes, but not always. Assets like gold, farmland, and infrastructure tend to hold value or appreciate during downturns due to inflation hedging or essential demand. However, distressed private equity or overleveraged real estate can collapse. The key is asset selection: Focus on assets with: - Stable cash flows (e.g., apartment buildings with long leases). - Inflation-linked contracts (e.g., farmland leases tied to commodity prices). - Barrier-to-entry costs (e.g., rare art, vintage wine) that prevent forced fire sales. Avoid illiquid assets tied to cyclical industries (e.g., retail real estate, tech startups) during recessions.
Q: What’s the most liquid asset class that still offers meaningful returns?
A: Dividend-paying blue-chip stocks (e.g., S&P 500 dividend aristocrats) offer ~3–4% yields with daily liquidity and inflation protection. For higher yields (~5–7%), consider: - Publicly traded REITs (e.g., PLD, VICI). - High-yield corporate bonds (investment-grade or BBB-rated). - Money market funds (e.g., Vanguard Treasury Money Market, ~4.5% yield as of 2023). The trade-off? These assets are more volatile than cash but far more liquid than private investments.
