The Complete Overview of Engineering Economy Net Present Worth
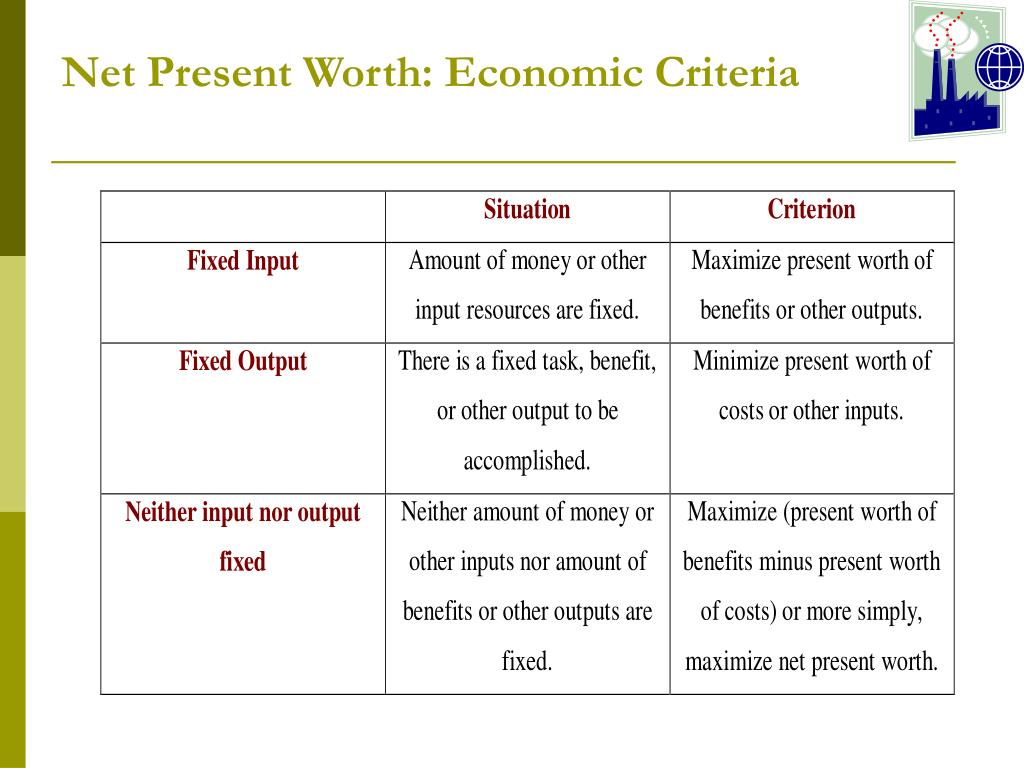
Engineering economy net present worth (NPW) serves as the financial litmus test for capital-intensive projects, where millions—or billions—of dollars are at stake. At its core, NPW is a discounted cash flow (DCF) technique that evaluates whether an investment’s future benefits outweigh its costs, adjusted for the time value of money. The formula—NPW = Σ (Cash Flowₜ / (1 + r)ᵗ) – Initial Investment—seems straightforward, but its real-world application demands nuance. Variables like discount rates (often tied to the project’s risk profile), inflation adjustments, and tax implications can shift NPW outcomes dramatically. For instance, a solar farm in Germany might show a positive NPW at a 5% discount rate but turn negative at 8%, altering the entire investment thesis. The method’s dominance in engineering economics stems from its ability to standardize comparisons across disparate projects. Whether evaluating a new manufacturing plant or a municipal wastewater system, NPW provides a common denominator for decision-making. However, its effectiveness hinges on the quality of input data. A 2018 study by the American Society of Civil Engineers found that 30% of infrastructure projects faced cost overruns due to underestimated operational expenses—a flaw NPW can expose if cash flow projections are rigorous. The challenge lies in balancing precision with practicality; engineers must avoid paralysis by analysis while ensuring their NPW models aren’t oversimplified.Historical Background and Evolution
The roots of engineering economy net present worth trace back to 18th-century economic thought, particularly the work of Daniel Bernoulli and his theory of utility. But it was the 20th century that formalized NPW as a tool for engineers, thanks to the rise of large-scale public works during the Industrial Revolution. Governments and corporations needed a way to justify expenditures like dams, railways, and power grids—projects that could take decades to yield returns. The U.S. Bureau of Reclamation’s 1930s dam projects, for example, relied on early NPW-like calculations to secure funding, even if the terminology wasn’t yet standardized. The modern framework emerged in the 1950s–60s with the advent of computers, which allowed for complex iterative calculations. Textbooks like Engineering Economy by Leland Blank and Anthony Tarquin (first published in 1974) cemented NPW as a cornerstone of engineering curricula. Today, software like @RISK and MATLAB’s Financial Toolbox automates NPW computations, but the underlying principles remain unchanged: account for all cash flows, apply the correct discount rate, and let the numbers dictate the outcome. The evolution reflects broader shifts—from analog slide rules to AI-driven scenario analysis—but the core question persists: Is this project worth the investment in today’s dollars?Core Mechanisms: How It Works
Understanding NPW requires dissecting its three critical components: cash flow estimation, discounting, and decision criteria. Cash flow estimation begins with identifying all relevant inflows (revenue, savings, subsidies) and outflows (capital costs, maintenance, taxes). For a wind farm, this might include energy sales, government subsidies, and turbine maintenance contracts. Each cash flow is then discounted back to the present using the formula PV = FV / (1 + r)ᵗ, where r is the discount rate—often the weighted average cost of capital (WACC) or a risk-adjusted hurdle rate. The discount rate is where subjectivity enters the equation. A low-risk municipal bond project might use a 3% rate, while a high-tech R&D venture could require 12%. This rate reflects not just inflation but the opportunity cost of tying up capital elsewhere. Once all cash flows are discounted, NPW is simply the net sum of these present values minus the initial investment. A positive NPW signals a viable project; negative, a money-loser. The margin between NPW and zero determines the project’s financial attractiveness.Key Benefits and Crucial Impact
Engineering economy net present worth (NPW) isn’t just a calculation—it’s a decision accelerator. In an era where capital is scarce and stakeholders demand accountability, NPW provides the transparency needed to justify expenditures. Governments use it to prioritize infrastructure; corporations deploy it to greenlight expansions; even nonprofits rely on NPW to secure grants for community projects. The method’s strength lies in its objectivity: it removes emotional bias from financial evaluations, ensuring that only projects with quantifiable upside proceed. Consider the case of a city evaluating two waste-management options: a $50 million landfill or a $70 million recycling plant. NPW analysis might reveal that the landfill has a higher NPW due to lower upfront costs, but the recycling plant’s environmental benefits could tip the scales in a cost-benefit analysis. Here, NPW becomes one piece of a larger puzzle, but its role is non-negotiable. Without it, decisions would default to political expediency or short-term savings—often at the expense of long-term sustainability."NPW is the financial equivalent of a stress test for projects. If it fails, you don’t need to build it—you need to rethink the entire premise." — Dr. Elena Vasquez, Professor of Civil Engineering, Stanford University
Major Advantages
- Risk quantification: NPW explicitly accounts for the time value of money, forcing decision-makers to confront the erosion of future dollars. A project with NPW of $2 million today may only yield $1 million in real terms after inflation.
- Project comparability: NPW allows apples-to-apples comparisons between projects with different lifespans or cash flow patterns. A 10-year oil pipeline and a 30-year hydroelectric dam can both be evaluated on the same financial footing.
- Stakeholder alignment: Investors, engineers, and policymakers all interpret NPW the same way, reducing miscommunication. If the NPW is positive, the project has buy-in from the data.
- Regulatory compliance: Many funding bodies (e.g., World Bank, EU grants) require NPW analysis as part of approval processes. Failing to meet NPW thresholds can disqualify entire proposals.
Comparative Analysis
| Metric | Engineering Economy NPW | Alternative Methods | |--------------------------|------------------------------------------------------|--------------------------------------------------| | Primary Focus | Net present value of all cash flows | IRR (internal rate of return), payback period | | Time Value Handling | Explicit discounting of all future flows | IRR ignores cash flow timing beyond breakeven | | Decision Rule | NPW > 0 = accept; NPW < 0 = reject | IRR > hurdle rate = accept (but may conflict with NPW) | | Strengths | Accounts for all project lifespan cash flows | IRR is intuitive for simple projects | | Weaknesses | Sensitive to discount rate assumptions | Payback period ignores post-breakeven cash flows |Future Trends and Innovations
The future of engineering economy net present worth (NPW) lies in its integration with big data and predictive analytics. Traditional NPW models rely on historical averages for variables like maintenance costs or energy prices, but machine learning is now enabling dynamic NPW calculations. For example, a smart grid project’s NPW can be recalculated in real-time as energy demand forecasts update. Tools like AI-driven Monte Carlo simulations are also refining NPW by modeling thousands of probabilistic scenarios, reducing the risk of blind spots in cash flow projections. Another frontier is sustainability-adjusted NPW, where environmental and social costs (e.g., carbon emissions, community displacement) are quantified and incorporated into the NPW formula. Initiatives like the Social Cost of Carbon are pushing this boundary, though the challenge remains in assigning monetary values to non-market impacts. As climate regulations tighten, NPW may evolve into a triple-bottom-line metric, balancing financial, environmental, and social returns. The question isn’t whether NPW will change—it’s how quickly it can adapt to an increasingly complex decision landscape.
Conclusion
Engineering economy net present worth (NPW) remains the gold standard for evaluating capital projects because it distills complex financial realities into a single, actionable metric. Its ability to weigh long-term benefits against upfront costs makes it indispensable in fields where failure isn’t an option—whether it’s a bridge spanning a river or a data center powering a city. Yet NPW isn’t infallible. Poor data, incorrect discount rates, or overlooked externalities can lead to flawed conclusions. The key is treating NPW as a starting point, not an endpoint, and supplementing it with qualitative analysis, risk assessments, and stakeholder input. As projects grow more sophisticated—think offshore wind farms or autonomous transit systems—NPW will continue to evolve. But its fundamental purpose remains unchanged: to ensure that every dollar invested today delivers the maximum possible return, in both financial and societal terms. In an age of constrained resources, that’s a principle no engineer, investor, or policymaker can afford to ignore.Comprehensive FAQs
Q: How do I determine the correct discount rate for NPW calculations?
A: The discount rate should reflect the project’s risk and the opportunity cost of capital. For government projects, it’s often the risk-free rate plus a risk premium (e.g., 3–5% for low-risk infrastructure). Private sector projects may use the WACC (weighted average cost of capital), which incorporates equity and debt costs. Always align the rate with the project’s financing structure and economic environment.
Q: Can NPW be used for non-profit or public-sector projects?
A: Absolutely. While NPW originated in for-profit contexts, it’s widely used in public-sector evaluations—especially when comparing projects with different timelines or budgets. For example, a city might use NPW to decide between a new library ($15M NPW) and a community center ($12M NPW), even if neither generates direct revenue. The focus shifts to societal benefits rather than pure profitability.
Q: What happens if NPW is zero?
A: An NPW of zero means the project’s present value of inflows exactly equals its outflows. While technically neutral, this is rare in practice because it implies perfect alignment between costs and benefits—often a sign of oversimplified assumptions. In reality, a zero NPW suggests the project is financially break-even, which may still be justified if it meets strategic or social goals.
Q: How do inflation and taxes affect NPW?
A: Inflation erodes the real value of future cash flows, so NPW calculations must use nominal discount rates (which include inflation) or real discount rates (inflation-adjusted). Taxes reduce cash flows via depreciation deductions and taxable income, so NPW models for taxable projects should incorporate after-tax cash flows. Ignoring either can lead to over- or under-estimating a project’s true NPW.
Q: Is NPW always better than IRR for project selection?
A: Not necessarily. NPW is superior when comparing mutually exclusive projects (e.g., choosing between two power plants) because it directly measures value creation. IRR can mislead when projects have uneven cash flows or differing scales, as a higher IRR doesn’t always mean higher NPW. Best practice is to use both metrics alongside payback period and sensitivity analysis for robust decision-making.
Q: Can NPW be negative and still be a good investment?
A: Technically, yes—but with caveats. A negative NPW implies the project destroys value under current assumptions. However, if the project has strategic benefits (e.g., entering a new market, meeting regulatory requirements), stakeholders might proceed despite the financial loss. In such cases, NPW should be paired with qualitative analysis (e.g., market share gains, compliance risks) to justify the decision.
Q: How do I handle uncertain cash flows in NPW analysis?
A: Uncertainty is managed through sensitivity analysis, scenario testing, and probabilistic methods. For example, you might run NPW calculations at discount rates of 5%, 8%, and 12% to see how results vary. Advanced techniques like Monte Carlo simulations randomly vary input parameters (e.g., energy prices, maintenance costs) thousands of times to generate a probability distribution of possible NPW outcomes.
