The Complete Overview of eFax.com’s Financial Landscape
eFax.com’s financial story is one of quiet endurance. Unlike high-growth SaaS companies that chase viral adoption, eFax.com’s growth is measured in steady monthly recurring revenue (MRR) and customer retention rates. Its efax.com net worth isn’t defined by a single valuation event but by its ability to sustain profitability in a shrinking market for fax services. Publicly, OpenText has never broken out eFax’s standalone financials, but industry estimates suggest its revenue hovers around $20–30 million annually, with gross margins in the 70–80% range—a testament to its low overhead and high-margin service model. The company’s valuation at acquisition provides a historical anchor, but its current worth depends on how OpenText leverages it within its broader platform. If eFax’s integration with OpenText’s document management tools drives incremental revenue, its net worth could be higher than standalone estimates; if it remains a niche product, its value may be limited to its cash-flow-positive status. What sets eFax.com apart is its defensive positioning in a market where faxing is often seen as a necessary evil. Healthcare providers, legal firms, and government agencies still require faxing for HIPAA compliance, court filings, and official correspondence. eFax.com’s ability to serve these verticals without disruption—through uptime guarantees, secure transmission, and audit trails—makes it indispensable to its core users. This stickiness is reflected in its customer lifetime value (CLV), which industry analysts estimate at 3–5 times its average annual contract value. The company’s pricing strategy, which avoids deep discounts in favor of predictable subscriptions, further stabilizes its revenue streams. While it may lack the glamour of a cloud-native disruptor, eFax.com’s efax.com net worth is underpinned by a business model that thrives on necessity rather than novelty.Historical Background and Evolution
The fax machine’s heyday in the 1990s and early 2000s was built on physical hardware, but eFax.com recognized that the real value lay in the document transmission process itself. By eliminating the need for a fax machine, it reduced costs for businesses while expanding access to faxing capabilities. This shift from hardware to software-as-a-service (SaaS) was prescient: it allowed eFax to scale without the limitations of physical infrastructure. The company’s early adopters were small businesses and freelancers who couldn’t justify the expense of a dedicated fax line but still needed to send documents securely. Over time, eFax.com broadened its appeal by adding features like batch faxing, fax-to-email, and electronic signatures, positioning itself as more than just a fax service but a document workflow solution. The 2016 acquisition by OpenText was a strategic move for both parties. OpenText, which specializes in enterprise content management, saw eFax as a way to tap into the $5 billion+ global fax services market, even as the industry contracted. For eFax, the acquisition provided capital for R&D and global expansion, particularly in Europe and Asia, where faxing remains more prevalent than in the U.S. Post-acquisition, eFax.com underwent rebranding and integration efforts, aligning its technology with OpenText’s broader platform. This transition hasn’t been seamless—some users report fragmented support and occasional integration hiccups—but it has reinforced eFax’s role as a specialized tool within a larger ecosystem. The acquisition also clarified its efax.com net worth trajectory: no longer a standalone player, its value is now tied to OpenText’s ability to monetize its capabilities beyond basic faxing.Core Mechanisms: How It Works
eFax.com’s business model is deceptively simple: it acts as an intermediary between senders and recipients, converting digital documents into fax format and vice versa. Users upload files via its web portal or email, and eFax handles the rest—routing the fax to the recipient’s number, logging the transmission, and storing a copy for audit purposes. The service’s reliability stems from its redundant infrastructure, which includes backup servers and fail-safes to prevent lost faxes. For businesses, this means peace of mind; for eFax, it means minimizing costly errors that could erode trust. Revenue is generated through subscription plans, ranging from basic pay-per-use models to enterprise contracts with custom features. The company also monetizes add-ons like electronic signatures, API access, and bulk faxing tools, which appeal to larger organizations with complex workflows. Unlike competitors that rely on ads or upsells, eFax’s pricing is transparent, with no hidden fees—a strategy that builds trust with its B2B clientele. Its integration with tools like Microsoft Office, Salesforce, and QuickBooks further enhances its utility, making it more than just a fax service but a seamless extension of existing business software. This ecosystem approach is critical to its efax.com net worth, as it reduces churn and increases the average contract value per customer.Key Benefits and Crucial Impact
eFax.com’s enduring relevance lies in its ability to solve a problem that other tools can’t: the need for legally binding, timestamped document transmission. In industries where electronic records must meet strict compliance standards, eFax’s service provides an audit trail that email or cloud storage cannot. This isn’t just about nostalgia for faxing; it’s about risk mitigation. A misplaced email or a delayed PDF can lead to legal penalties or lost business. eFax’s reliability—backed by SLAs and uptime guarantees—makes it a non-negotiable tool for its core users. The company’s impact extends beyond its direct customers. By digitizing faxing, eFax.com has reduced the environmental footprint of paper-based document transmission, aligning with sustainability trends in corporate responsibility. Its integration with modern workflows also bridges the gap between legacy systems and digital transformation, allowing businesses to modernize without abandoning critical processes. For OpenText, eFax serves as a gateway product, introducing enterprises to its broader suite of document management tools. This symbiotic relationship is a key driver of eFax’s efax.com net worth, as it creates upsell opportunities beyond its core service."Faxing isn’t dead—it’s just gone digital. eFax.com doesn’t sell a product; it sells peace of mind." — Industry analyst, 2023
Major Advantages
- Compliance-first design: Meets HIPAA, GDPR, and other regulatory requirements with built-in audit logs and secure transmission.
- Hybrid workflow integration: Works alongside email, cloud storage, and CRM systems without disruption.
- Predictable pricing: No surprise fees or usage-based surprises, unlike pay-per-use competitors.
- Global reach: Supports international faxing with local number options, critical for multinational businesses.
Comparative Analysis
| eFax.com | Competitors (HelloFax, RingCentral Fax, etc.) |
|---|---|
| Subscription-based with enterprise-grade SLAs. | Mixed models: pay-per-use, freemium, or bundled with other services. |
| Deep integration with OpenText’s document management. | Limited to basic API or third-party integrations. |
| Focus on compliance-heavy industries (healthcare, legal). | Broader appeal but weaker compliance features. |
| Reportedly $20–30M annual revenue, high gross margins. | Smaller revenue streams, often tied to parent companies’ telecom businesses. |
| Acquired by OpenText (2016), now part of a larger ecosystem. | Mostly independent or owned by telecom giants with shifting priorities. |
Future Trends and Innovations
The future of eFax.com hinges on two competing forces: the decline of faxing as a standalone need and the rise of document workflow automation. As industries adopt electronic signatures and blockchain-based document verification, the demand for traditional faxing may diminish. However, eFax’s ability to adapt—by embedding its capabilities into broader document management platforms—could extend its relevance. OpenText’s strategy suggests a shift toward positioning eFax as a modular component within its AI-driven content management suite, where faxing becomes one of many transmission methods rather than the sole focus. Innovation will likely come from AI-assisted document processing, where eFax could automate routing, classification, and even basic compliance checks. If OpenText succeeds in blending eFax’s reliability with emerging technologies like automated workflows or smart contracts, its efax.com net worth could see an indirect boost as part of a larger valuation. The risk? If OpenText prioritizes other products, eFax may become a legacy feature rather than a growth driver. For now, its stability—rather than explosive growth—remains its most valuable asset.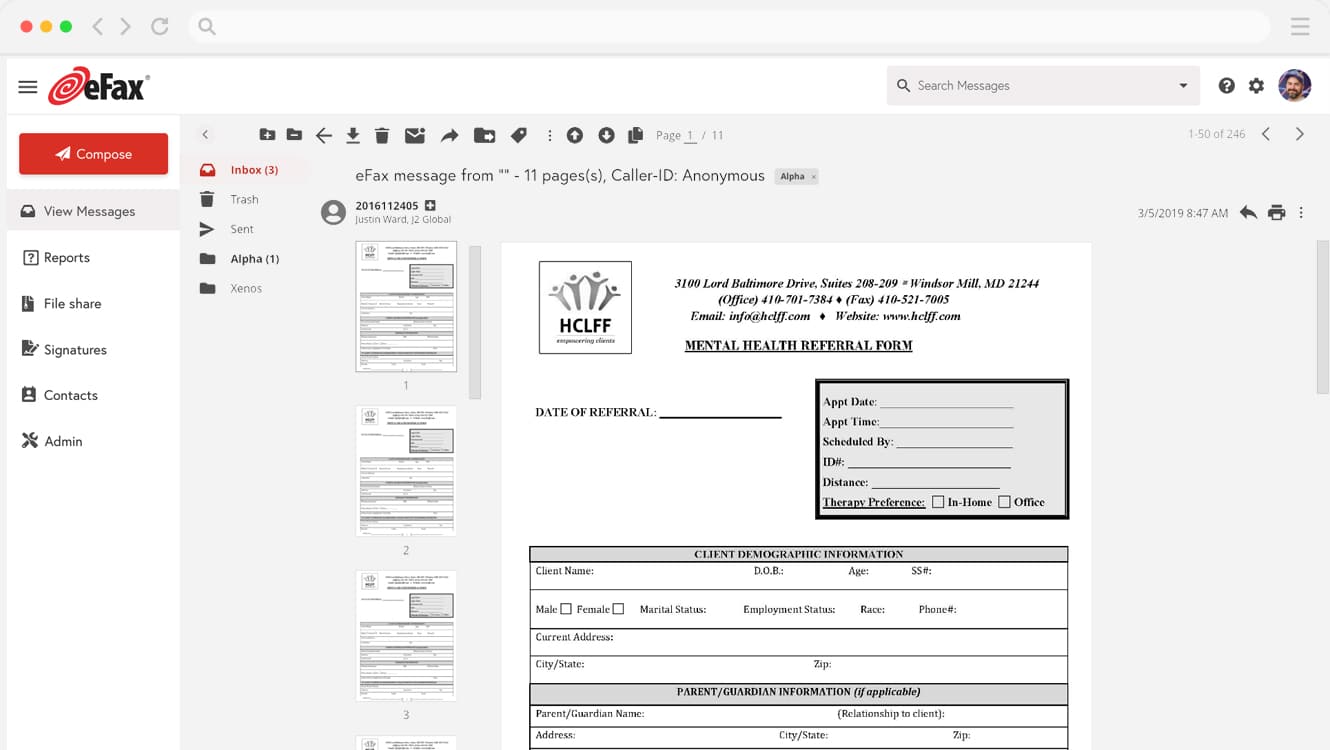
Conclusion
eFax.com’s story is one of adaptive survival in an industry that most assumed would die. Its efax.com net worth isn’t measured in billion-dollar rounds or IPOs but in its ability to remain financially viable while serving a niche that refuses to disappear. The company’s strength lies in its defensive positioning: it doesn’t chase trends; it fulfills needs that others overlook. For OpenText, eFax is more than a fax service—it’s a bridge to enterprise document management, and its continued relevance is tied to how well it integrates with broader digital transformation efforts. As faxing fades from mainstream consciousness, eFax.com’s legacy may not be in its standalone success but in its role as a catalyst for digital workflow evolution. Its net worth, then, is less about the dollars it generates today and more about the value it unlocks for businesses navigating the transition from paper to pixels. In an era where "disruption" is overused, eFax’s quiet persistence is a reminder that some industries don’t die—they just change shape.Comprehensive FAQs
Q: Is eFax.com still profitable?
A: Yes, eFax.com operates as a cash-flow-positive business within OpenText’s portfolio. While exact figures aren’t public, industry estimates suggest it maintains gross margins of 70–80%, driven by its subscription model and low operational costs. Its profitability stems from serving compliance-heavy sectors where alternatives like email or cloud storage fall short.
Q: How does eFax.com’s net worth compare to similar services?
A: Direct comparisons are difficult due to private ownership, but eFax’s acquisition value (reportedly $50–70M in 2016) and its integration with OpenText suggest a higher net worth than standalone competitors like HelloFax or RingCentral Fax. Most rivals operate at smaller scales, often as add-ons to telecom or messaging services, whereas eFax’s specialization in faxing and compliance gives it a defensive valuation advantage.
Q: Does OpenText’s ownership affect eFax.com’s financial health?
A: OpenText’s acquisition provided capital for expansion and R&D, but it also introduced integration challenges. While eFax retains its core service, its growth is now tied to OpenText’s broader strategy. If OpenText prioritizes other products, eFax may see reduced investment; however, its stable revenue streams make it a low-risk asset within the portfolio. Some users report mixed experiences with post-acquisition support, but financially, eFax remains a reliable revenue contributor for OpenText.
Q: Are there any risks to eFax.com’s long-term viability?
A: The biggest risk is technological obsolescence. As industries adopt electronic signatures, blockchain-based verification, and AI-driven document processing, the need for faxing could decline. However, eFax mitigates this by positioning itself as part of a larger document workflow solution, not just a fax service. Regulatory requirements in healthcare and legal sectors also act as a moat, ensuring demand persists. The greater risk may lie in OpenText’s ability to innovate around eFax’s core offering rather than letting it stagnate as a legacy product.
Q: How does eFax.com’s pricing model impact its net worth?
A: eFax’s subscription-based, transparent pricing is a key driver of its financial stability. Unlike competitors that rely on ads or pay-per-use models—which can be volatile—eFax’s predictable revenue streams contribute to high gross margins. This model also reduces churn, as businesses prefer the consistency of a fixed cost over unpredictable usage fees. The result is a revenue stream that scales with customer retention, a critical factor in assessing its net worth.
Q: Has eFax.com expanded into new markets or services?
A: Since its acquisition, eFax has focused on deepening integrations with OpenText’s document management tools rather than expanding into new services. It has, however, strengthened its presence in Europe and Asia, where faxing remains more common. The company has also added features like electronic signatures and API access to appeal to larger enterprises. While it hasn’t pivoted away from faxing, its strategic alignment with OpenText’s platform suggests a future where faxing becomes one component of a broader digital workflow ecosystem.
Q: What role does eFax.com play in OpenText’s overall business?
A: For OpenText, eFax serves as a gateway product—introducing enterprises to its document management suite while providing a specialized, high-margin service. OpenText likely views eFax as a revenue generator with upsell potential, particularly for businesses that need compliance-ready document transmission. Its integration with OpenText’s AI and automation tools could also position eFax as a legacy feature within a modern workflow, ensuring its relevance even as faxing’s standalone use declines.
Q: Are there any rumors or speculation about eFax.com being sold again?
A: There have been no credible reports of eFax.com being up for sale since its 2016 acquisition. OpenText has not indicated plans to divest the asset, and given eFax’s stable revenue contribution, there’s little incentive to sell. Speculation about a potential sale typically arises when a company underperforms or when its parent company shifts strategy—neither appears to be the case for eFax. Its future lies in organic growth within OpenText’s ecosystem, not as a standalone acquisition target.
