6 Things Worth Knowing About Couchbase Net Worth
Couchbase’s financial story is less about public disclosures and more about reading between the lines. The company’s couchbase net worth is a mosaic of private funding, customer contracts, and competitive positioning—none of which are neatly packaged for public consumption. Below are six critical pieces of the puzzle, each revealing how Couchbase’s value is constructed, defended, and occasionally challenged.1. The $150 Million Series E Round Set a New Benchmark
In 2017, Couchbase raised $150 million in Series E funding, a sum that at the time made it the largest private funding round for a database company. This infusion pushed its valuation to $400 million, a figure that seemed ambitious for a firm still grappling with scaling its enterprise sales. Yet the round wasn’t just about money—it was a vote of confidence in Couchbase’s ability to monetize its NoSQL platform amid a market dominated by open-source alternatives like MongoDB. The funding allowed the company to double down on cloud deployments and hire aggressively, positioning it as a serious contender in the database wars. What’s often missed is how this round reshaped perceptions of couchbase net worth. Before 2017, the company was viewed as a niche player; afterward, it became a dark horse in the enterprise software space. The valuation wasn’t just a number—it signaled that investors believed Couchbase could command premium pricing for its managed services and support contracts. This shift laid the groundwork for later funding rounds, though specifics remain scarce. Industry observers now cite this moment as the turning point where Couchbase’s worth stopped being speculative and started being strategic.2. Revenue Growth Outpaces Public Comparables
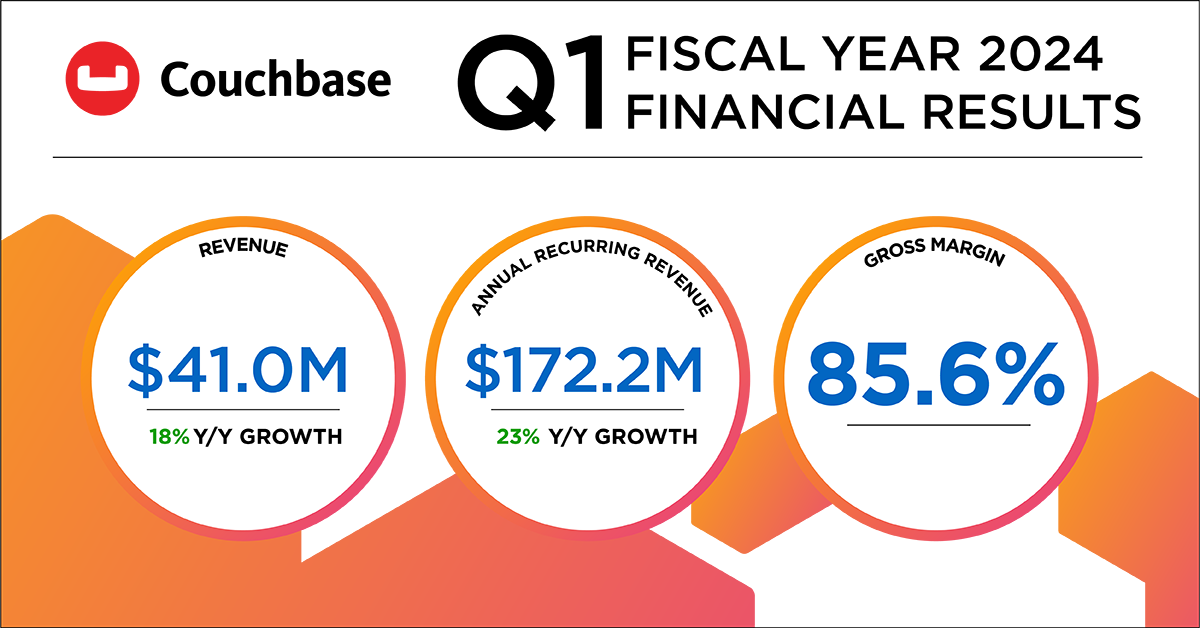
Couchbase’s revenue trajectory is one of the few tangible metrics available, though exact figures are guarded. Reports suggest annual revenue has consistently exceeded $200 million in recent years, with gross margins flirting with 80%. These numbers are impressive by private-company standards, but they’re also a double-edged sword: high margins mean profitability, but they also attract scrutiny over whether the company is leaving money on the table by staying private. Comparisons to publicly traded peers like MongoDB (which went public in 2017) are inevitable, though flawed. The key difference lies in Couchbase’s business model. While MongoDB’s growth has been tied to its open-source community and freemium strategy, Couchbase has leaned into subscription-based, enterprise-grade licensing—a model that typically justifies higher valuations but requires deeper customer relationships. This approach has allowed Couchbase to secure contracts with Fortune 500 firms, including financial services and telecom giants, where downtime isn’t an option. The result? A couchbase net worth that’s less about user count and more about sticky, high-margin revenue streams.3. Strategic Acquisitions Inflated Valuation Expectations
Couchbase’s 2023 acquisition of Kinetica, a real-time analytics database, wasn’t just a product expansion—it was a valuation booster. Kinetica’s technology filled gaps in Couchbase’s portfolio, particularly in time-series data and geospatial analytics, areas critical for industries like logistics and smart cities. The deal, rumored to be worth tens of millions, wasn’t disclosed publicly, but its strategic rationale sent a clear message: Couchbase was doubling down on becoming a one-stop shop for operational and analytical workloads. Acquisitions like this don’t just add to top-line revenue; they recalibrate how the market perceives couchbase net worth. By broadening its use cases, Couchbase reduces its reliance on any single vertical, making it less vulnerable to sector-specific downturns. Analysts speculate that such moves could push its valuation into the $4 billion to $6 billion range if executed successfully, though private valuations are notoriously volatile. The Kinetica deal also underscored Couchbase’s willingness to pay for growth, a tactic that could either accelerate its worth or dilute it—depending on integration challenges.4. The IPO Question: Why Stay Private?
Couchbase has repeatedly delayed IPO discussions, despite investor pressure and the allure of liquidity. The reasons are telling. First, staying private allows the company to avoid the scrutiny of quarterly earnings reports, a luxury that gives it flexibility in product roadmaps and pricing. Second, private markets have historically offered higher valuations for high-growth tech firms—something Couchbase’s leadership may prioritize over the transparency of a public listing. Finally, the company’s focus on long-term enterprise adoption (rather than rapid user growth) aligns better with private funding cycles. The decision to stay private also shapes how couchbase net worth is perceived. Without a market cap to anchor expectations, the company’s value becomes a moving target, influenced by whispers of potential acquirers (including Oracle and IBM) rather than shareholder demands. This ambiguity can be a double-edged sword: it keeps speculation alive but also makes it harder for stakeholders to gauge true worth. Yet for Couchbase’s leadership, the trade-off may be worth it—control over narrative and strategy often outweighs the benefits of going public.5. Competitive Pressure from Open-Source Rivals
Couchbase’s couchbase net worth isn’t just about its own performance—it’s a reflection of the broader NoSQL market. Open-source competitors like MongoDB and Cassandra Community have eroded some of the premium pricing power that once justified Couchbase’s valuation. These rivals offer free tiers and community-driven development, making it harder for Couchbase to argue that its enterprise features are worth the cost. The result? A valuation ceiling that’s lower than it might otherwise be, as customers weigh open-source flexibility against Couchbase’s managed services. Yet Couchbase has countered this pressure with a dual strategy: it continues to invest in its open-source core (Couchbase Server) while aggressively selling its Couchbase Capella cloud platform and professional services. This approach ensures that while the community edition keeps the brand relevant, the subscription and support revenue—where margins are highest—drive couchbase net worth upward. The challenge lies in balancing these priorities without alienating either enterprise clients or the open-source community.6. The Oracle Acquisition Rumor: A Valuation Litmus Test
For years, whispers of an Oracle acquisition have circulated, with valuations floating between $3 billion and $5 billion. These rumors aren’t idle chatter—they’re a barometer for couchbase net worth. If Oracle were to seriously pursue Couchbase, it would likely signal that the company’s valuation has reached a tipping point where strategic value outweighs standalone growth potential. Oracle’s interest stems from Couchbase’s strengths in hybrid cloud deployments and its ability to integrate with Oracle’s own database products, creating a formidable stack for enterprise customers. The catch? No deal has materialized, and the rumors may be more about valuation leverage than imminent action. For Couchbase, these discussions serve as a reality check: they force the company to justify its worth in terms of synergies, not just revenue. If the rumors persist without resolution, it could indicate that couchbase net worth is still being negotiated—or that Oracle’s appetite for database acquisitions has cooled. Either way, the chatter keeps the company’s financial story in the spotlight, even if the numbers remain private.
How These Facts Connect
Couchbase’s couchbase net worth isn’t a static figure; it’s a dynamic interplay of funding rounds, competitive moves, and market perception. The $150 million Series E round wasn’t just a funding milestone—it set the template for how Couchbase would be valued: not by user growth alone, but by its ability to monetize enterprise-grade reliability. This approach has paid off in high margins, but it’s also made the company vulnerable to open-source disruption, forcing it to double down on services and cloud offerings to sustain its worth. The strategic acquisitions, like Kinetica, reveal another layer: couchbase net worth is as much about diversification as it is about revenue. By expanding into analytics, Couchbase isn’t just adding products—it’s broadening the use cases that justify its valuation. Meanwhile, the IPO delay suggests that leadership believes private markets offer better terms, even if it means living with ambiguity. Together, these factors paint a picture of a company that’s playing the long game, where worth is measured in customer lock-in and strategic flexibility rather than quarterly earnings.| Factor | Impact on Valuation | Key Example |
|---|---|---|
| Funding Rounds | Sets baseline valuation; signals investor confidence | $150M Series E (2017) → $400M valuation |
| Revenue Model | High margins justify premium pricing | 80%+ gross margins on subscriptions |
| Acquisitions | Expands product portfolio; recalibrates worth | Kinetica deal (2023) for analytics capabilities |
| Competitive Pressure | Open-source rivals cap growth potential | MongoDB’s freemium model vs. Couchbase’s enterprise focus |
Conclusion
Couchbase’s couchbase net worth is a study in contrasts: a private company with public-market aspirations, a database firm that thrives on enterprise stickiness yet faces open-source competition, and a valuation that’s as much about strategy as it is about revenue. The numbers—whether $3 billion, $5 billion, or somewhere in between—are less important than what they represent: a bet on the future of NoSQL in a cloud-first world. For now, Couchbase’s leadership seems content to let the market speculate while it focuses on execution, knowing that a high valuation is only as good as the next product release or customer contract. The bigger question isn’t what Couchbase is worth today, but whether its model can sustain that worth in a decade. If cloud-native databases remain a cornerstone of enterprise IT, Couchbase’s valuation could climb further. If open-source alternatives continue to gain traction, its worth may plateau—or worse, decline. One thing is certain: the company’s financial story is far from over, and its couchbase net worth will keep evolving alongside the tech landscape it helps define.Comprehensive FAQs
Q: Is Couchbase’s valuation publicly disclosed?
A: No. As a private company, Couchbase does not disclose its exact valuation. Industry estimates based on funding rounds and revenue reports suggest figures in the $3 billion to $5 billion range, but these are speculative. The last confirmed valuation was $400 million following its 2017 Series E round.
Q: How does Couchbase’s revenue compare to MongoDB’s?
A: Couchbase’s revenue is reportedly above $200 million annually, with gross margins near 80%. MongoDB, which went public in 2017, reported $900 million in revenue in 2022, but its model relies heavily on open-source adoption and community growth—areas where Couchbase focuses less. Direct comparisons are difficult due to differing business models.
Q: Why hasn’t Couchbase gone public yet?
A: Couchbase has cited multiple reasons for delaying an IPO, including the desire to avoid quarterly earnings pressure, maintain flexibility in product strategy, and potentially secure a higher valuation in private markets. Some analysts speculate that leadership may also be waiting for an opportune moment—such as a strong revenue uptick or a major acquisition—to maximize proceeds.
Q: Are there rumors of an Oracle acquisition?
A: Yes. For years, rumors of an Oracle acquisition have surfaced, with valuations reportedly ranging from $3 billion to $5 billion. These discussions are often tied to Oracle’s interest in Couchbase’s hybrid cloud capabilities and its ability to complement Oracle’s existing database products. However, no formal agreement has been announced, and the rumors may serve as a valuation benchmark rather than an imminent deal.
Q: How does Couchbase’s business model affect its worth?
A: Couchbase’s subscription-based, enterprise-focused model justifies higher valuations by ensuring recurring revenue and high margins. Unlike open-source competitors, it monetizes support, services, and managed cloud offerings (e.g., Couchbase Capella), which are critical for industries where uptime and compliance are non-negotiable. This model has allowed it to command premium pricing, but it also makes its couchbase net worth more sensitive to enterprise economic cycles.
Q: What role do acquisitions play in Couchbase’s valuation?
A: Acquisitions like Kinetica (2023) are strategic moves that can inflation or recalibrate Couchbase’s worth. By expanding into new areas (e.g., real-time analytics), these deals broaden the company’s use cases, making it more attractive to a wider range of customers. However, they also introduce integration risks and potential dilution, which could temporarily suppress valuation expectations if not executed smoothly.
Q: Could Couchbase’s valuation decline in the future?
A: Yes. While Couchbase’s couchbase net worth has grown due to its enterprise focus and cloud strategy, risks include open-source competition, shifts in enterprise spending, or failure to innovate in key areas like AI-driven databases. If rivals like MongoDB or Cassandra gain more traction in the cloud, or if economic downturns reduce IT budgets, Couchbase’s valuation could face downward pressure—though its high-margin model provides some cushion.
