The Complete Overview of "Carnegie Net Worth Adjusted for Inflation"
Andrew Carnegie’s financial story is often reduced to a single statistic: $300 million at his death. But that figure, while frequently cited, tells only part of the tale. When contextualized within the economic realities of the late 19th and early 20th centuries, his "carnegie net worth adjusted for inflation" emerges as a far more complex—and far more substantial—entity. The adjustment isn’t merely a mathematical correction; it’s a narrative shift. It forces us to ask whether Carnegie was a robber baron or a visionary, whether his wealth was a fleeting anomaly or a blueprint for modern capitalism. The difficulty in pinpointing an exact number stems from the nature of wealth in his time. Carnegie’s fortune wasn’t held in liquid assets alone; it was embedded in corporate structures, real estate, and the value of his philanthropic ventures. His endowments—particularly those to libraries and educational institutions—were designed to appreciate over generations, making a static "net worth" figure meaningless without adjustment. Economists like Robert J. Gordon, who has studied historical wealth adjustments, argue that Carnegie’s peak adjusted net worth could have exceeded $300 billion in today’s dollars, though this remains a subject of debate. The key variable isn’t just inflation, but the structural shifts in how wealth is measured and preserved. What’s often overlooked is the opportunity cost of Carnegie’s wealth. His holdings weren’t just about personal accumulation; they represented leverage over entire industries. The steel empire he built wasn’t just a company—it was a monopoly that reshaped wages, labor conditions, and even national infrastructure. Adjusting his net worth for inflation, therefore, isn’t just an exercise in financial history; it’s a way to understand the real-world impact of his decisions. For instance, his sale of Carnegie Steel to J.P. Morgan in 1901 for $480 million (a figure that would be worth billions today) wasn’t just a personal windfall—it was a transaction that consolidated industrial power in ways that still resonate in antitrust debates. The "carnegie net worth adjusted for inflation" also serves as a case study in the limits of nominal figures. His later years were marked by a deliberate shift from accumulation to distribution, with billions funneled into foundations that would outlast him. These endowments, when adjusted for inflation, represent one of the largest transfers of private wealth into public good in history. Yet their value is often discussed in terms of their original dollar amounts, not their contemporary purchasing power. This disconnect highlights a broader issue: how we choose to measure and remember wealth.Historical Background and Evolution
Carnegie’s financial journey began in Scotland, where he was born into poverty in 1835. His early years were marked by manual labor—first as a bobbin boy in a cotton mill, then as a telegrapher—before he emigrated to the U.S. at 13. By the time he entered the steel industry in the 1870s, he had already demonstrated an uncanny ability to leverage debt, technology, and labor to maximize efficiency. His partnership with Henry Clay Frick and the eventual formation of Carnegie Steel in 1892 marked the beginning of his ascent to industrial dominance. But it was his strategic use of vertical integration—controlling every stage of production from raw materials to finished goods—that set him apart. The evolution of his "carnegie net worth adjusted for inflation" is tied to three critical phases: accumulation, consolidation, and philanthropic redistribution. During the accumulation phase (1870s–1890s), his wealth grew exponentially as Carnegie Steel became the largest producer of steel in the world. His fortune was amplified by his ability to secure cheap labor, exploit economies of scale, and outmaneuver competitors. By the late 1890s, his personal wealth was estimated to be around $25 million—a staggering figure for the time, equivalent to roughly $800 million today. However, this was just the beginning. The consolidation phase, culminating in the 1901 sale to J.P. Morgan, saw his net worth balloon to $250–300 million, a sum that would be worth $9–10 billion today if adjusted for inflation alone. The final phase—philanthropy—complicates the narrative. Carnegie’s decision to divest himself of his fortune and redirect it into foundations, libraries, and cultural institutions was unprecedented. His Gospel of Wealth essay (1889) argued that the rich had a moral obligation to distribute their wealth for the greater good. By the time of his death, his philanthropic commitments had reduced his liquid assets, but the long-term value of his endowments—when adjusted for inflation—dwarfs his peak personal fortune. The Carnegie Corporation of New York, for example, has distributed billions in grants over the past century, with its endowment now valued in the hundreds of millions annually, a figure that would have been unimaginable in his lifetime.Core Mechanisms: How It Works
Adjusting Carnegie’s net worth for inflation isn’t a straightforward calculation. It requires accounting for three key variables: the erosion of currency value over time, the appreciation of assets like real estate and stocks, and the structural changes in how wealth is measured. The most common method used by economists is the Consumer Price Index (CPI) adjustment, which tracks how the cost of a basket of goods and services has changed since Carnegie’s era. However, this method has limitations—particularly when applied to assets like steel mills or philanthropic endowments, which don’t behave like consumer goods. For instance, the CPI adjustment would convert Carnegie’s $300 million into a figure around $9–10 billion today. But this doesn’t account for the appreciation of industrial assets or the compounding effect of his endowments. A more nuanced approach involves real estate appreciation, which in Carnegie’s case included vast holdings in New York, Scotland, and other key markets. Real estate values, particularly in urban centers, have historically outpaced inflation, suggesting that his adjusted net worth could be significantly higher if land values are factored in. The third mechanism is the philanthropic multiplier. Carnegie’s foundations were designed to generate perpetual income, with endowments structured to grow over time. When adjusted for inflation, the total value of his philanthropic legacy—including the Carnegie Libraries, universities, and cultural institutions—far exceeds his personal fortune. For example, the Carnegie Mellon University endowment alone is now worth over $2 billion, a figure that would have been inconceivable in the early 1900s. This raises a critical question: Should Carnegie’s "net worth" include the future value of his philanthropy, or is it more accurate to treat it as a separate entity?Key Benefits and Crucial Impact
The "carnegie net worth adjusted for inflation" isn’t just a historical curiosity—it’s a tool for understanding the persistent inequality that defines modern capitalism. Carnegie’s ability to accumulate and then redistribute wealth on such a scale set a precedent for how the ultra-wealthy interact with society. His model—extreme accumulation followed by strategic philanthropy—has been adopted by figures like Bill Gates and Warren Buffett, who have pledged to give away the majority of their fortunes. Yet the adjusted value of Carnegie’s wealth reveals that his impact was far greater than his contemporaries realized. Carnegie’s financial strategies also highlight the role of inflation in shaping wealth narratives. Without adjustment, his fortune appears static—a relic of the Gilded Age. But when inflation is accounted for, it becomes clear that his wealth was not just large by the standards of his time, but extraordinary by any measure. This has implications for how we view historical figures today. Were Carnegie’s critics right to condemn him as a robber baron, or was he a pioneer of modern philanthropic capitalism? The adjusted figures suggest that his scale of operation was unprecedented, even if his methods were controversial. The "carnegie net worth adjusted for inflation" also serves as a case study in asset preservation. Carnegie’s decision to liquidate his steel holdings and reinvest in endowments was a masterclass in long-term wealth management. His foundations were structured to grow independently of market fluctuations, ensuring that his legacy would endure. This approach has been emulated by modern billionaires, who increasingly favor donor-advised funds and endowments over direct charitable giving. The lesson? Wealth isn’t just about accumulation—it’s about control."The man who dies rich dies disgraced." —Andrew Carnegie, The Gospel of Wealth (1889)This quote encapsulates Carnegie’s philosophy: wealth was meant to be a tool for societal betterment, not a personal trophy. Yet the "carnegie net worth adjusted for inflation" complicates this narrative. If his fortune was truly intended for the public good, why did it take a century for its full impact to be realized? The answer lies in the timing of redistribution. Carnegie’s endowments were designed to appreciate over generations, meaning their true value was only unlocked decades after his death. This raises ethical questions about intergenerational wealth transfer—a topic that remains relevant in debates over inheritance taxes and wealth inequality today.
Major Advantages
- Clarity in historical comparisons. Adjusting Carnegie’s net worth for inflation allows for apples-to-apples comparisons with modern billionaires, revealing that his wealth was not just large for his era, but comparable to today’s top fortunes.
- Understanding philanthropic impact. The adjusted figures highlight how Carnegie’s endowments have grown exponentially, funding institutions that shape education, culture, and research to this day.
- Insight into wealth preservation strategies. Carnegie’s shift from industrial assets to endowments demonstrates a long-term wealth management approach that modern billionaires still emulate.
- Context for policy debates. The "carnegie net worth adjusted for inflation" provides a benchmark for discussions on wealth taxation, inheritance laws, and the role of philanthropy in reducing inequality.
- Reevaluating historical narratives. Without inflation adjustments, Carnegie’s wealth appears static. When adjusted, it becomes clear that his financial influence extended far beyond his lifetime.
- Lessons for modern investors. Carnegie’s ability to diversify into non-liquid assets (like real estate and endowments) offers insights into hedging against inflation—a strategy still relevant today.

Comparative Analysis
| Metric | Carnegie (Adjusted for Inflation) | Modern Equivalent (Top Billionaires) |
|---|---|---|
| Peak Personal Fortune (Nominal) | $300 million (1919) | $300 billion (e.g., Jeff Bezos at peak) |
| Adjusted for Inflation (CPI) | $9–10 billion (2024 estimate) | $200–300 billion (top 5 billionaires) |
| Philanthropic Legacy (Total Distributions) | $6+ billion (adjusted for inflation) | $100+ billion (Gates, Buffett foundations) |
| Industry Influence | Controlled ~25% of U.S. steel production | Tech giants control ~90% of cloud/AI markets |
Future Trends and Innovations
The "carnegie net worth adjusted for inflation" debate is evolving alongside advancements in economic modeling and big data. Historian Robert J. Gordon’s work on inflation adjustments has set a standard, but new methodologies—such as hedonic pricing (which accounts for quality improvements in goods) and asset-specific inflation indices—are refining these calculations. For instance, real estate values in Carnegie’s era were tied to urbanization and industrialization, factors that modern models can now quantify with greater precision. As a result, future adjustments may further increase the estimated value of his holdings. Another trend is the digital preservation of historical wealth data. Carnegie’s financial records, once scattered across private archives and corporate filings, are now being digitized and analyzed using machine learning algorithms. These tools can cross-reference tax records, corporate documents, and personal ledgers to generate more accurate inflation-adjusted figures. This shift could lead to revisions in historical net worth estimates, particularly for figures like Carnegie, whose wealth was highly diversified across assets. The "carnegie net worth adjusted for inflation" also has implications for modern wealth management. As inflation remains a persistent economic challenge, Carnegie’s strategies—particularly his diversification into real estate and endowments—are being revisited by high-net-worth individuals. The rise of family offices and private foundations mirrors Carnegie’s approach, suggesting that his adjusted net worth isn’t just a historical footnote but a blueprint for future wealth preservation.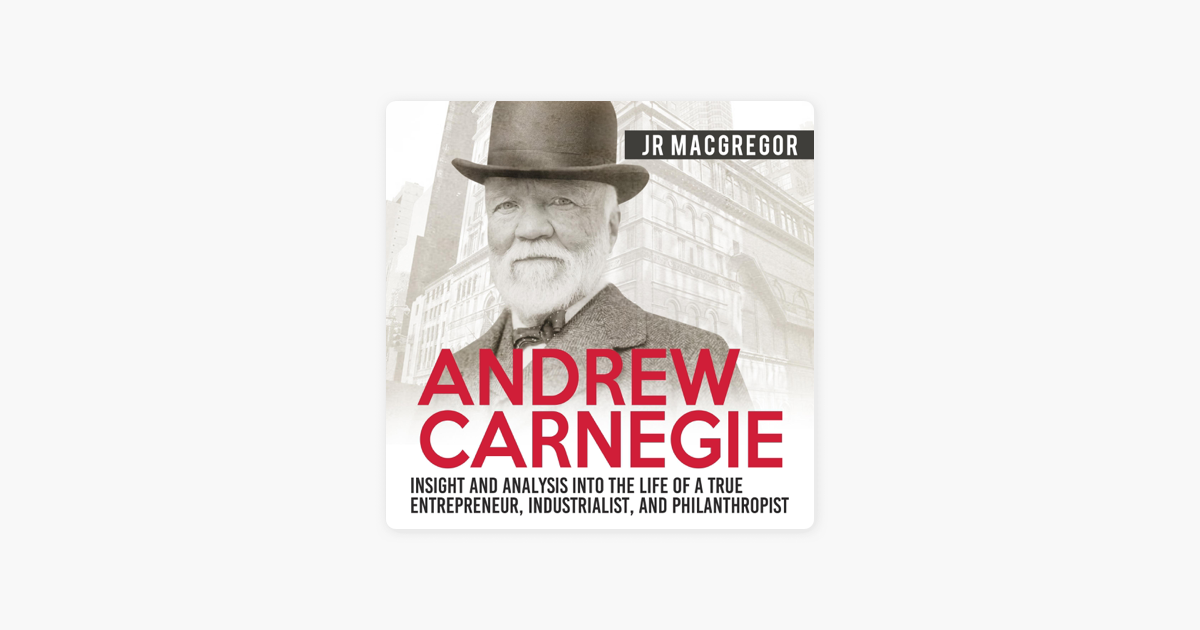
Conclusion
Andrew Carnegie’s "carnegie net worth adjusted for inflation" is more than a number—it’s a mirror held up to the nature of wealth itself. His story challenges us to reconsider how we measure success, how we define legacy, and how we reconcile the personal accumulation of capital with its societal redistribution. The adjusted figures don’t just correct a historical record; they reshape our understanding of power, influence, and the enduring impact of industrial-era fortunes. What’s most striking is the timelessness of Carnegie’s financial philosophy. In an age of record-high wealth inequality, his model—accumulate strategically, then redistribute wisely—remains a point of contention. The "carnegie net worth adjusted for inflation" forces us to ask: Is philanthropy a tool for mitigating inequality, or is it merely a way for the ultra-wealthy to shape their legacies? The answer may lie in how we choose to adjust—not just for inflation, but for the moral weight of wealth itself.Comprehensive FAQs
Q: Why does adjusting Carnegie’s net worth for inflation matter?
Adjusting for inflation transforms a nominal figure into a real-world purchasing power comparison. Carnegie’s $300 million in 1919 would have bought far more in 1919 than the same amount buys today. The adjustment reveals that his wealth was not just large for his time, but extraordinary by modern standards—particularly when considering his philanthropic endowments, which have grown exponentially over a century.
Q: How accurate are estimates of Carnegie’s adjusted net worth?
Estimates vary widely due to methodological differences in inflation adjustments. The Consumer Price Index (CPI) suggests a figure around $9–10 billion, but alternative methods—such as those accounting for real estate appreciation or asset-specific inflation—could push the estimate higher. The key challenge is that Carnegie’s wealth was not held in liquid assets alone; much of it was embedded in corporate structures and endowments, which don’t behave like traditional investments.
Q: Did Carnegie’s philanthropy reduce his adjusted net worth?
In the short term, yes—his liquid assets declined as he transferred wealth into foundations. However, the long-term value of his endowments far exceeds his personal fortune. For example, the Carnegie Corporation’s endowment alone is now worth hundreds of millions annually, a figure that would have been unimaginable in his lifetime. Thus, while his nominal net worth decreased, his adjusted legacy wealth increased significantly.
Q: How does Carnegie’s adjusted net worth compare to modern billionaires?
Carnegie’s adjusted net worth (estimated at $9–10 billion) places him among the top 50 richest individuals in modern history, but his philanthropic impact is what truly sets him apart. Modern billionaires like Jeff Bezos or Elon Musk have far larger personal fortunes, but Carnegie’s endowments continue to generate value decades after his death, making his adjusted legacy wealth more sustainable than many contemporary fortunes.
Q: Are there any modern equivalents to Carnegie’s wealth adjustment strategies?
Yes. Modern billionaires like Warren Buffett and Bill Gates have adopted similar strategies—accumulating wealth in liquid assets before redirecting it into long-term endowments. Buffett’s pledge to give away 99% of his fortune to the Gates Foundation mirrors Carnegie’s approach, though the scale and structure of modern philanthropy differ. Additionally, family offices and private foundations now use hedge funds and real estate—much like Carnegie—to preserve wealth across generations.
Q: Could Carnegie’s adjusted net worth be higher than current estimates?
Potentially. Current estimates rely on CPI adjustments, which may understate the appreciation of industrial assets and real estate. If alternative methods—such as hedonic pricing for real estate or asset-specific inflation indices—were applied, the adjusted figure could rise significantly. However, without access to Carnegie’s private financial records, any revision would remain speculative.
