Breaking Down the Numbers
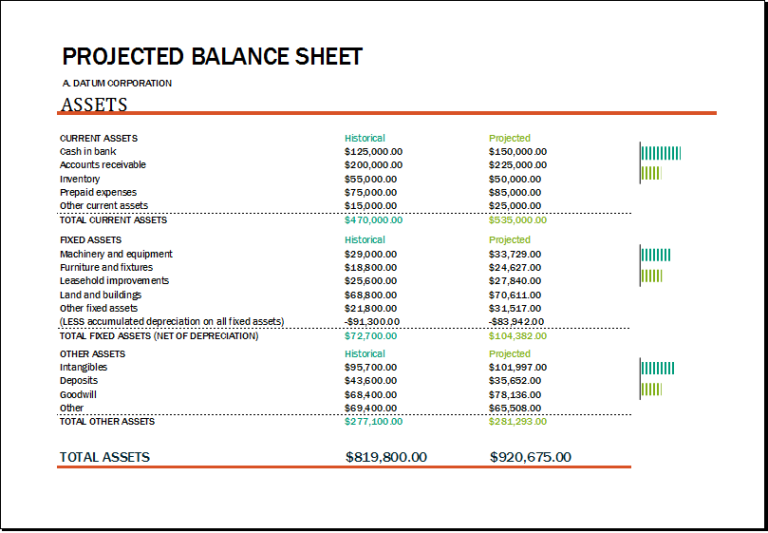
The balance sheet net worth on balance sheet is the residual value after liabilities are subtracted from assets—simple in theory, complex in practice. For most companies, this figure is dominated by two categories: tangible net assets (property, inventory, equipment) and intangible assets (goodwill, patents, brand value). The latter is where balance sheet net worth on balance sheet becomes a battleground. Goodwill, for example, arises from acquisitions and is tested annually for impairment. If a company overpays for an asset, its balance sheet net worth on balance sheet can plummet overnight when goodwill is written down. The disconnect between balance sheet net worth on balance sheet and market value is especially stark in industries where growth is driven by unproven assets. Consider a biotech firm with a balance sheet net worth on balance sheet of $300 million—mostly in cash—but whose true value rests on a single experimental drug. If the drug fails Phase III trials, the balance sheet net worth on balance sheet remains unchanged, while the company’s market cap could collapse. This illustrates a fundamental truth: balance sheet net worth on balance sheet is a backward-looking metric, while market value is forward-looking. Investors ignore the former at their peril.The Verified Baseline
Publicly traded companies in the U.S. and EU must disclose their balance sheet net worth on balance sheet under GAAP or IFRS, respectively. For most, this appears in the equity section as "shareholders’ equity," broken down into: - Paid-in capital (cash from share issuance) - Retained earnings (profits reinvested) - Accumulated other comprehensive income (foreign currency gains, pension adjustments) - Treasury stock (shares repurchased and retired) What’s verifiable? The hard assets—cash, inventory, fixed assets—are audited and subject to physical verification. But even here, discrepancies arise. A retailer might list inventory at cost, while its liquidation value is far lower. The balance sheet net worth on balance sheet doesn’t account for this obsolescence until the asset is sold. Similarly, accounts receivable are recorded at face value, not net of potential bad debts. The balance sheet net worth on balance sheet thus reflects a best-case scenario unless footnotes reveal higher-than-expected credit risk. The most transparent balance sheet net worth on balance sheet belong to companies with minimal intangibles and no off-balance-sheet exposures. A manufacturing firm with no acquisitions, no operating leases, and no pension plans will have a balance sheet net worth on balance sheet that closely mirrors its economic reality. For others, the gap between balance sheet net worth on balance sheet and true worth is a matter of accounting policy—and sometimes, aggressive interpretation.What the Estimates Suggest
Industry analysts often adjust balance sheet net worth on balance sheet to reflect hidden risks. For instance, a bank’s balance sheet net worth on balance sheet might exclude loan loss reserves, which are instead recorded as liabilities. Yet these reserves are the first line of defense against defaults. Adjusting for them could reveal a balance sheet net worth on balance sheet that’s 10–15% lower than reported. Similarly, tech companies with high R&D expenditures may capitalize development costs, inflating balance sheet net worth on balance sheet—until those projects fail and goodwill must be impaired. Private companies present an even greater challenge. Their balance sheet net worth on balance sheet is often prepared for tax or financing purposes, not transparency. A family-owned business might value its real estate at appraised worth while undervaluing inventory to reduce taxable income. The result? A balance sheet net worth on balance sheet that’s artificially low for creditors but high for heirs. Valuation firms like PwC or Deloitte often reconcile these discrepancies when assessing buyout potential, but their adjusted balance sheet net worth on balance sheet remains proprietary.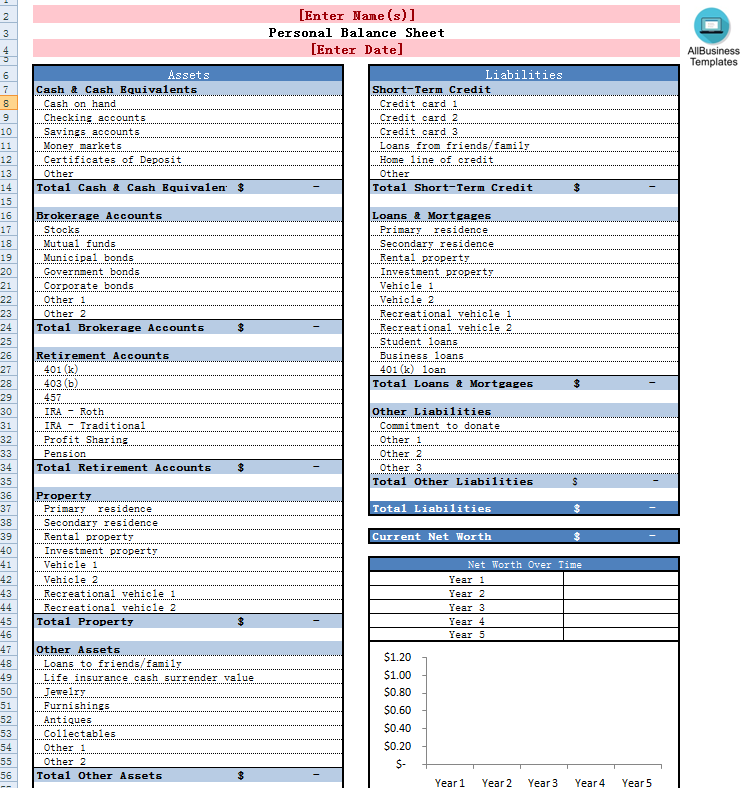
Case Study: A Closer Look
Consider the 2019 collapse of WeWork’s parent company, The We Company, which revealed how balance sheet net worth on balance sheet can mislead. On paper, its balance sheet net worth on balance sheet was inflated by: 1. Capitalized operating leases (treated as assets rather than liabilities). 2. Overstated goodwill from acquisitions that never generated returns. 3. Related-party transactions with Adam Neumann’s entities, which weren’t fully disclosed. When SoftBank demanded a restructuring, the true balance sheet net worth on balance sheet—after adjusting for lease liabilities and goodwill impairment—was a fraction of the $47 billion valuation. The lesson? A balance sheet net worth on balance sheet that ignores operating leases or contingent liabilities is a house of cards."The balance sheet is a snapshot, but the footnotes are the story. If you don’t read them, you’re flying blind." — Martin Fridson, former portfolio manager at Lehman Brothers
| Factor | Estimated Impact on Adjusted Net Worth |
|---|---|
| Capitalized operating leases (reclassified as liabilities) | Reduction of ~$10 billion (industry estimates) |
| Goodwill impairment from failed acquisitions | Reduction of ~$5–$8 billion (post-restructuring) |
| Related-party loans to Neumann (written off) | Reduction of ~$1.7 billion (audited) |
| Unrecorded tenant improvement liabilities | Reduction of ~$2–$4 billion (estimated) |
What This Means Going Forward
Regulators are tightening scrutiny on balance sheet net worth on balance sheet transparency. The SEC’s 2023 proposal to require disclosure of off-balance-sheet risks—including derivatives, guarantees, and special-purpose entities—aims to close loopholes that distort balance sheet net worth on balance sheet. Meanwhile, private equity firms now face pressure to mark down goodwill annually, reducing the temptation to inflate balance sheet net worth on balance sheet through overpaying for assets. For investors, the takeaway is clear: balance sheet net worth on balance sheet is a starting point, not an endpoint. The most resilient companies don’t just report a high balance sheet net worth on balance sheet; they reconcile it with cash flow, debt covenants, and qualitative risks. A tech giant with a balance sheet net worth on balance sheet of $50 billion but $30 billion in unredeemed convertible debt is in a far different position than one with the same balance sheet net worth on balance sheet but no such liabilities. The distinction matters when markets turn.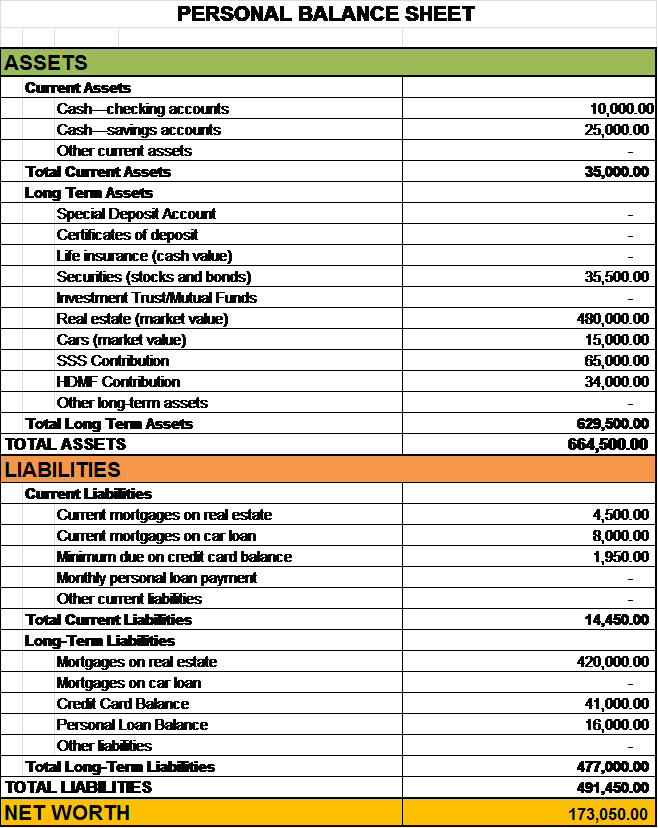
Conclusion
The balance sheet net worth on balance sheet is a tool, not a truth. It can reveal solvency, but it can also conceal it—through omissions, assumptions, or outright misrepresentation. The companies that survive financial crises are those that treat balance sheet net worth on balance sheet as a floor, not a ceiling. They stress-test their balance sheets for worst-case scenarios, disclose contingent liabilities proactively, and ensure their balance sheet net worth on balance sheet aligns with economic reality—not just accounting rules. For the rest, the balance sheet net worth on balance sheet remains a numbers game. And in finance, as in life, the numbers alone rarely tell the full story.Comprehensive FAQs
Q: Can a company’s balance sheet net worth on balance sheet be negative?
A: Yes. If a company’s liabilities exceed its assets, its balance sheet net worth on balance sheet (shareholders’ equity) becomes negative. This is common in distressed firms or those with high debt loads. For example, a leveraged buyout target might show a negative balance sheet net worth on balance sheet before restructuring.
Q: How do operating leases affect balance sheet net worth on balance sheet?
A: Under old GAAP rules, operating leases didn’t appear on the balance sheet, inflating balance sheet net worth on balance sheet by excluding lease liabilities. Since 2019, leases >12 months must be capitalized, reducing balance sheet net worth on balance sheet for lessees. This change forced companies like Amazon to adjust their balance sheet net worth on balance sheet downward by billions.
Q: Why does a company’s market cap often exceed its balance sheet net worth on balance sheet?
A: Because balance sheet net worth on balance sheet doesn’t account for growth potential. A tech startup with $100 million in cash but no revenue might trade at a $5 billion valuation if investors bet on future profits. The balance sheet net worth on balance sheet reflects past transactions; market value reflects future expectations.
Q: Are there industries where balance sheet net worth on balance sheet is more misleading?
A: Yes. Financial services (due to off-balance-sheet derivatives), biotech (unproven assets), and private equity (loaded debt) are notorious for balance sheet net worth on balance sheet distortions. In contrast, utilities or commodity traders have balance sheet net worth on balance sheet that closely track economic value.
Q: How can I spot a balance sheet net worth on balance sheet that’s artificially high?
A: Look for: 1. Goodwill >50% of total assets (suggests overpaying for acquisitions). 2. High capitalized leases (check footnotes for operating lease liabilities). 3. Frequent "other comprehensive income" adjustments (can hide volatility). 4. Related-party transactions (may inflate asset values). Always cross-reference with cash flow statements and management discussions.
