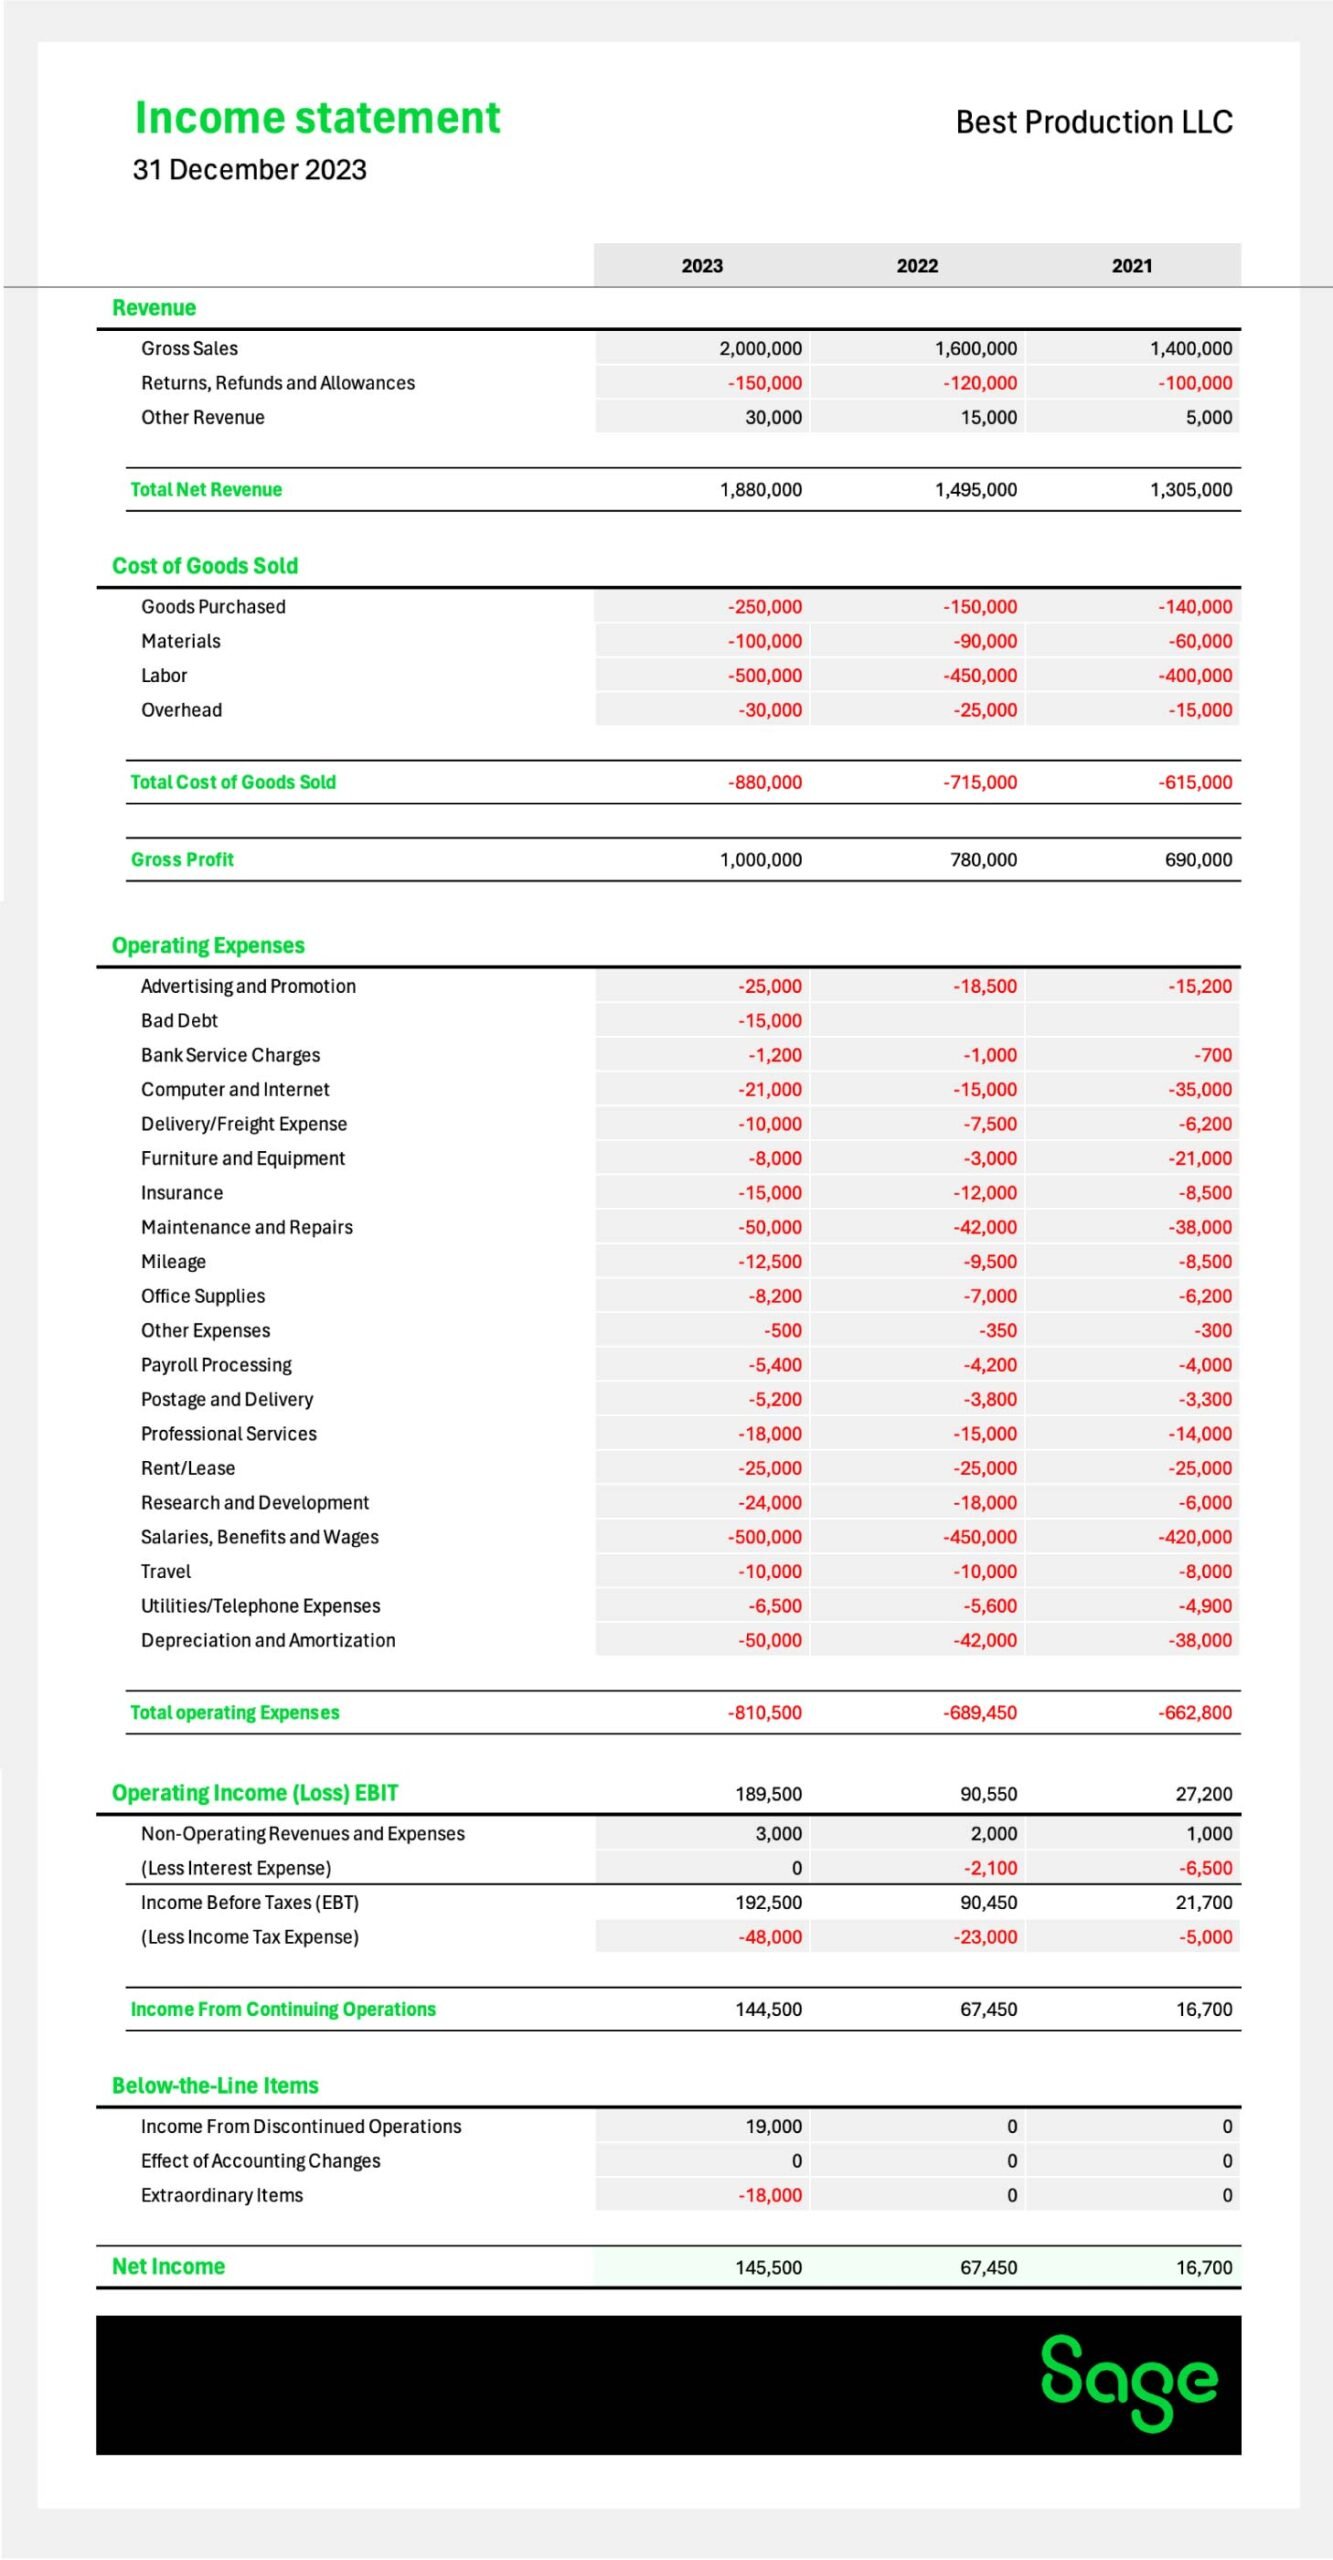
Where It All Began
The income statement’s origins trace back to the Industrial Revolution, when factories and railroads demanded accountability. Before then, financial records were ad-hoc ledgers, useful for audits but not for strategic planning. The shift came with the need to track profitability—not just assets, but the flow of money in and out. Early accountants, like Luca Pacioli (the "father of accounting"), laid the groundwork, but it was the 19th-century rise of limited-liability corporations that forced clarity. Shareholders needed to know if their investments were yielding returns, not just if the company had assets. The income statement was born as a tool to measure earnings over a period, not a static valuation. The confusion with net worth, however, didn’t emerge until later. In the 1920s, as personal finance literature exploded, terms like "net worth" became household names. But corporate finance remained distinct. The income statement was the domain of CFOs and auditors; net worth was the turf of wealth managers and tax advisors. The two worlds rarely collided—until they did. The Great Depression exposed a critical flaw: many "profitable" companies on paper were insolvent in reality. The income statement showed earnings, but the balance sheet revealed the truth. The disconnect between the two became a liability, not just a theoretical debate.The Early Signs
By the 1950s, the gap widened as business schools began teaching accounting as a unified discipline. Students memorized the three financial statements—the income statement, balance sheet, and cash flow statement—as if they were interchangeable. Textbooks often lumped them together under "financial reporting," with little emphasis on their distinct purposes. The income statement, in particular, was framed as a "profit-and-loss" document, which—while accurate—painted it as a catch-all for financial health. It wasn’t until the 1970s, with the rise of conglomerates and complex capital structures, that the distinction became critical. The real turning point came in the 1980s, when corporate scandals like those at Enron and WorldCom forced regulators to tighten reporting standards. The income statement’s role as a performance document became non-negotiable. Yet, the public’s understanding lagged. Even today, surveys show that an income statement is a statement of question 56 options: a) the net worth of a company remains a common misconception, especially among non-finance professionals. The problem isn’t just ignorance; it’s the way financial jargon is repackaged for accessibility. Terms like "bottom line" (net income) are conflated with "net worth," when in reality, the bottom line is just one piece of a much larger puzzle.The Turning Point
The Enron collapse in 2001 was the catalyst. The company’s income statement showed billions in profits, but its balance sheet hid debt and off-balance-sheet entities that made it effectively insolvent. The income statement had lied—not because it was flawed, but because it was being misinterpreted. Investors and analysts had treated it as a proxy for net worth, ignoring the fact that earnings don’t equal equity. The aftermath led to the Sarbanes-Oxley Act, which mandated stricter disclosure rules. Yet, the damage was done: the myth that an income statement is a statement of question 56 options: a) the net worth of a company persisted, now with regulatory backing. What changed wasn’t just the law, but the language. Accountants and educators began emphasizing the temporal nature of the income statement—its focus on periodic performance rather than point-in-time valuation. The balance sheet, they argued, was the true statement of net worth. The income statement was its dynamic counterpart. The shift was subtle but profound: financial health wasn’t static. It was a process."The income statement doesn’t tell you what you own; it tells you what you’ve earned—and what you’ve lost—along the way. Confusing the two is like reading a speedometer and thinking it measures your car’s total distance traveled." — Robert Kiyosaki (adapted from financial lectures, 2005)
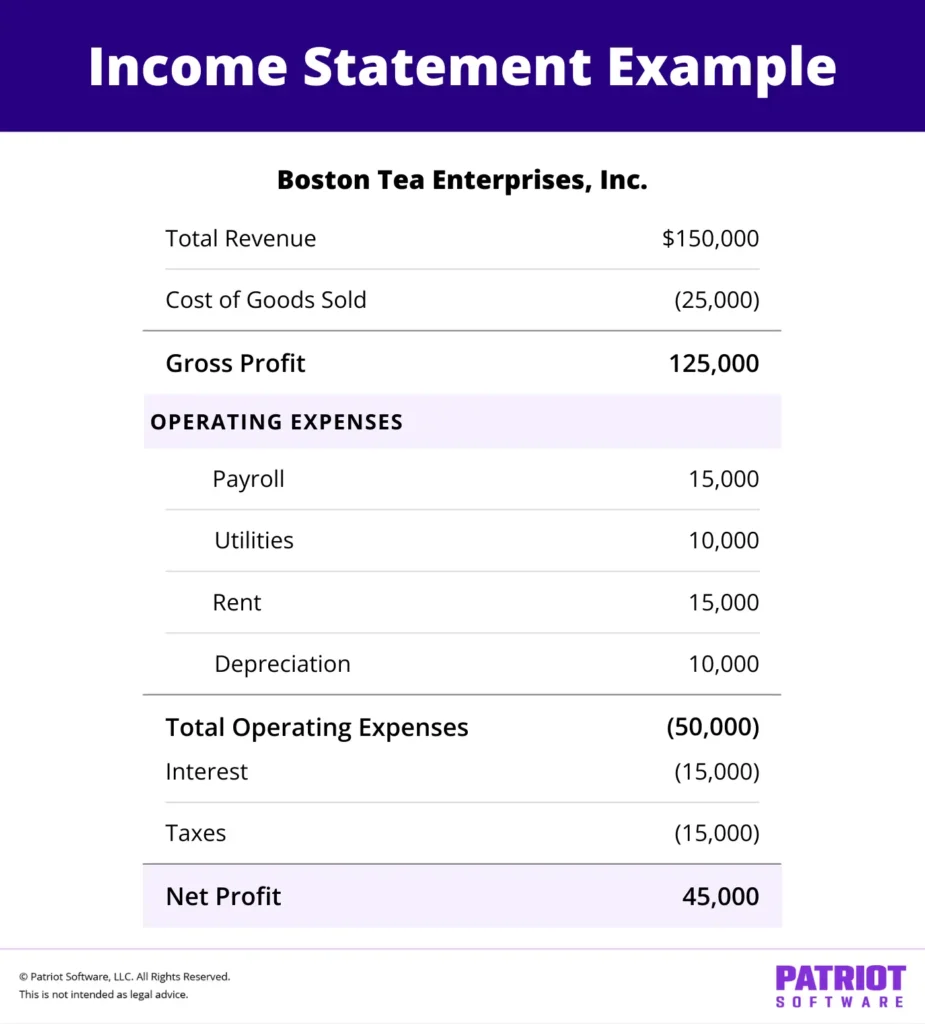
The Build-Up, Year by Year
| Period | Key Development |
|---|---|
| 1800s–1920s | Income statements emerge as profit-tracking tools for industrial corporations. Net worth remains a personal finance concept. |
| 1930s–1950s | Great Depression exposes gaps between reported profits and actual solvency. Income statements are scrutinized but still treated as "profit" documents. |
| 1960s–1980s | Business schools standardize accounting education, but conflate income statements with net worth in introductory courses. "Bottom line" becomes shorthand for financial health. |
| 1990s–2000s | Dot-com bubble and Enron scandal force a reckoning. Regulators and educators push to separate income statements (performance) from balance sheets (valuation). The term "net worth" is increasingly reserved for personal finance. |
Lessons From the Journey
- The income statement is a story, not a snapshot. It answers: How did we perform this year? The balance sheet answers: What do we own today? Mixing the two leads to misdiagnoses of financial health.
- Profit ≠ Cash Flow ≠ Net Worth. A company can be "profitable" on paper but broke in reality—Enron’s lesson.
- Language shapes perception. Terms like "bottom line" (net income) are often misused as proxies for "net worth," blurring critical distinctions.
- Regulation alone can’t fix misconceptions. Education must bridge the gap between technical definitions and real-world application.
- The myth persists because it’s convenient. Net worth is tangible; earnings are abstract. But abstract doesn’t mean irrelevant.
- For investors, the income statement is a leading indicator; the balance sheet is a trailing one. Ignoring the difference is like predicting the weather by looking at yesterday’s clouds.
Where Things Stand Today
Today, an income statement is a statement of question 56 options: a) the net worth of a company is less about ignorance and more about context. The rise of fintech and AI-driven financial tools has democratized access to income statements, but it hasn’t always improved understanding. Platforms like YCharts or Bloomberg Terminal make the data accessible, yet many users still treat the income statement as a substitute for a balance sheet. The result? A generation of entrepreneurs and investors making decisions based on incomplete pictures. The good news is that the distinction is clearer than ever. Modern accounting frameworks—like IFRS and GAAP—have refined the language, though the challenge remains in translating those frameworks into actionable insights. The bad news? The myth is still profitable for those who peddle oversimplified financial advice. A quick Google search for "how to read a company’s financials" yields results that often conflate the two, perpetuating the cycle.
Conclusion
The income statement is not a statement of net worth. It’s something far more dynamic—and far more critical. It’s the difference between knowing a company made money and understanding how it made it, what it spent, and why its profits might not translate to growth. The confusion isn’t just semantic; it’s strategic. A startup might show consistent profits on its income statement but be drowning in debt (a balance sheet issue). A mature corporation might report declining earnings (income statement) while its assets appreciate (balance sheet). The two must be read together, but they must never be assumed to mean the same thing. The next time you see an income statement is a statement of question 56 options: a) the net worth of a company, pause. Ask: Is this about what I own, or what I’ve earned? The answer will tell you whether you’re looking at a company’s health—or just its symptoms.Comprehensive FAQs
Q: Why does the income statement matter more than net worth for investors?
The income statement reveals sustainability. Net worth shows what you have at a moment in time, but earnings (or losses) over multiple periods indicate whether a company can generate returns consistently. A high net worth with declining earnings is a red flag; a modest net worth with growing profits is a green light.
Q: Can a company have a high net worth but poor income statement performance?
Absolutely. Think of a company with vast real estate holdings (high assets) but little revenue (low earnings). Its balance sheet might show strength, but its income statement would reflect stagnation. This is why diversified investors analyze both.
Q: How do small businesses often misinterpret their income statements?
Small business owners frequently treat the income statement as a cash-flow tool, assuming that profits = available funds. In reality, expenses like depreciation or accounts payable can show up as costs on the income statement without immediately affecting cash. This leads to overconfidence in "profitable" but cash-strapped operations.
Q: Are there industries where income statements are more important than balance sheets?
Yes. Tech startups, for example, often prioritize income statement growth (revenue, margins) over balance sheet health (assets, debt) because their value is tied to future earnings potential. Conversely, asset-heavy industries like utilities rely more on balance sheets to assess stability.
Q: What’s the most common real-world mistake tied to this confusion?
Assuming that a company’s "bottom line" (net income) is equivalent to its cash reserves. Many businesses go bankrupt despite reporting profits because they’ve reinvested heavily or carried high liabilities. The income statement doesn’t account for these nuances—only the balance sheet does.
Q: How can I tell if someone is misusing the income statement as a net worth proxy?
Watch for language like "This company is worth X because it earned Y." That’s a dead giveaway. A proper analysis would say, "This company earned Y this quarter, but its net worth is determined by assets minus liabilities." The first is a performance claim; the second is a valuation claim.
Q: Can AI or financial tools fix this misunderstanding?
Tools can highlight the differences, but they can’t replace education. An AI might flag that a company’s income statement shows losses while its balance sheet is strong—but it won’t explain why that matters. Human judgment is still the bridge between data and decision-making.
