Where It All Began
The origins of modern high-net-worth client acquisition financial services trace back to the post-WWII era, when Swiss private banks quietly became the custodians of European aristocracy and industrialists fleeing inflation. The model was simple: cash deposits in numbered accounts, minimal paperwork, and a culture of silence. Clients didn’t walk into branches—they were invited. The threshold wasn’t a minimum balance; it was exclusivity. The early signs of a more structured approach emerged in the 1970s, when U.S. banks began targeting wealthy Americans who wanted to diversify beyond domestic markets. Citibank’s private client division, for instance, didn’t just offer checking accounts—it offered global custodianship. The message was clear: if you had enough wealth to matter, you deserved a team that operated like a sovereign entity, not a retail bank. This was the birth of tiered wealth management, where clients weren’t segmented by balance sheets but by risk profiles and lifestyle needs.The Early Signs
By the 1980s, the game had grown more competitive. Japanese zaibatsu families, Middle Eastern royalty, and Latin American business tycoons were all vying for the same elite bankers. The solution? Specialized desks. UBS created a dedicated team for Asian clients; Credit Suisse hired former diplomats to navigate geopolitical risks. The acquisition process wasn’t transactional—it was cultural. A banker in Hong Kong might host a client in Kyoto, not to sell bonds, but to understand their worldview. The other shift was technology. In the late 1990s, as the internet democratized finance, private banks realized they couldn’t afford to look like dinosaurs. They built secure portals for ultra-high-net-worth individuals (UHNWIs) to monitor portfolios in real time—but with the caveat that no one else could see them. The irony? The more digital the tools became, the more analog the relationships stayed.The Turning Point
The 2008 financial crisis didn’t just test wealth managers—it redefined high-net-worth client acquisition financial services. When fortunes evaporated overnight, the banks that retained clients were the ones who acted like partners, not vendors. A tech CEO in Silicon Valley didn’t want a quarterly report; he wanted a damage assessment and a plan to rebuild. The banks that survived didn’t cut ties—they deepened them. The turning point wasn’t just about survival. It was about reputation. Clients who had trusted banks with billions suddenly demanded transparency without compromise. The result? A new breed of wealth manager emerged—one that blended old-world discretion with modern compliance. The message was no longer "We’ll hide your money." It was "We’ll protect it, legally and strategically.""The ultra-rich don’t care about your fees. They care about whether you’ll still be there when the next crisis hits—and whether you’ll have a plan before they even know there’s a crisis." — Former Head of Private Banking, UBS (2010)

The Build-Up, Year by Year
| Period | What Changed |
|---|---|
| 2000–2007 | Banks raced to open "wealth management" divisions, but many failed to differentiate. The winners were those that offered bespoke solutions—e.g., structuring assets for non-domiciled clients or setting up family offices. |
| 2008–2015 | Post-crisis, due diligence became non-negotiable. Banks that couldn’t verify source of wealth lost clients to competitors. The rise of family offices also fragmented the market—some UHNWIs preferred managing their own wealth. |
| 2016–Present | Digital natives (tech founders, crypto entrepreneurs) entered the HNWI space, demanding agility and innovation. Banks responded with private credit, alternative investments, and AI-driven portfolio insights—but only for clients who met strict thresholds. |
Lessons From the Journey
- Access isn’t just about money—it’s about perception. A client with £50 million might be turned away if they lack the right network or risk tolerance profile.
- Compliance is the new luxury. The banks that mastered AML and tax transparency didn’t just avoid fines—they became trusted advisors in an era of scrutiny.
- Relationships outlast products. A banker who understands a client’s personal risks (e.g., divorce, political exposure) will keep them longer than one who just sells hedge funds.
- Silos don’t work. The best wealth managers integrate tax, legal, and investment teams—not in separate departments, but as a unified strategy.
- The client’s time is the real currency. A UHNWI won’t tolerate meetings without clear outcomes. Efficiency is a status symbol.
Where Things Stand Today
Today, high-net-worth client acquisition financial services is a dual-edged sword. On one side, the barriers to entry have never been higher: regulatory hurdles, cybersecurity risks, and client expectations demand near-perfect execution. On the other, the opportunities are unprecedented. Private credit markets are booming, ESG investing is reshaping portfolios, and cross-border wealth is more liquid than ever. The banks leading the charge aren’t just chasing assets—they’re curating ecosystems. A family office in Monaco might offer private school placements, art authentication, and even concierge legal services for clients. The acquisition process has become holistic: it’s not about signing a client, but designing a lifestyle around their wealth. Yet the biggest challenge remains trust. In an era where data breaches and whistleblowers are common, the ultra-rich demand proof—not just of returns, but of loyalty. The banks that thrive will be those that earn it.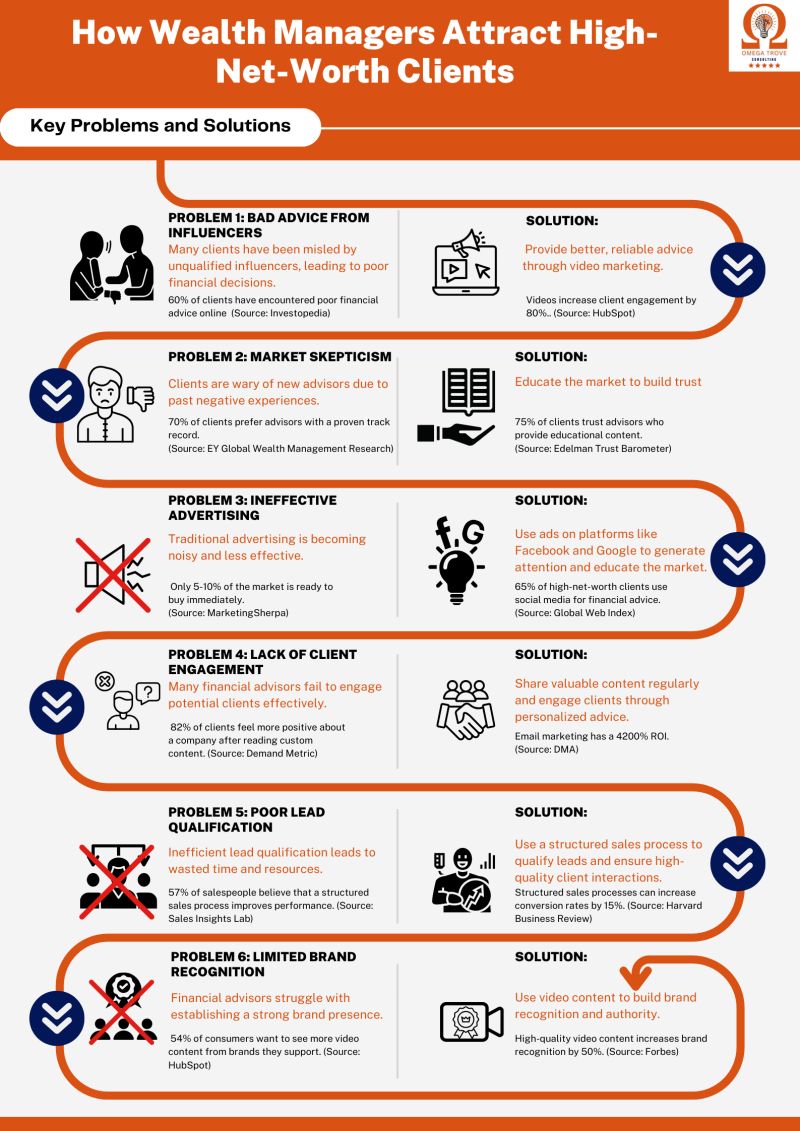
Conclusion
High-net-worth client acquisition financial services has evolved from a transactional art to a strategic science. The banks that dominated in the 20th century relied on secrecy and connections; today’s leaders rely on technology, compliance, and deep specialization. But the core principle hasn’t changed: wealth management isn’t about money. It’s about control. The future belongs to those who can anticipate risks before clients do—whether it’s geopolitical shifts, market volatility, or personal liabilities. The ultra-rich don’t just want advisors; they want guardians. And in a world where trust is the rarest currency of all, the banks that provide it will write the next chapter.Comprehensive FAQs
Q: What’s the minimum net worth required to be considered "high-net-worth" in financial services?
Industry standards vary, but $1 million in liquid assets is the common threshold for "high-net-worth individuals" (HNWIs), while $30 million+ defines "ultra-high-net-worth" (UHNWIs). However, access to elite services often depends on more than just numbers—network, risk profile, and lifestyle needs play a critical role.
Q: How do private banks verify the source of wealth for HNW clients?
Due diligence is multi-layered: banks review tax records, business ownership, inheritance documents, and sometimes third-party audits. Some engage forensic accountants to trace assets back to their origin. The goal isn’t just compliance—it’s risk mitigation. A client with unexplained wealth may be accepted, but their portfolio will be highly restricted until full transparency is achieved.
Q: Can a family office replace a traditional private bank?
It depends. Family offices (typically serving $500M+ net worth) offer full-service control, but they require in-house expertise in tax, legal, and investment. Many UHNWIs use both: a bank for liquidity and global reach, and a family office for bespoke structuring. The hybrid model is now the norm.
Q: What’s the biggest mistake wealth managers make in acquiring HNW clients?
Assuming money is the only currency. Many bankers focus on product pitches (private equity, art investments) instead of understanding the client’s personal risks (e.g., divorce, political exposure). The best acquisitions happen when the bank solves a problem—not just manages wealth.
Q: How has digital transformation changed HNW client acquisition?
Technology has raised the bar, not lowered it. While digital portals and AI-driven insights are now expected, human relationships remain irreplaceable. The shift has been toward "digital-first, human-always"—where clients use apps for monitoring but still demand face-to-face strategy sessions. Banks that automate without personalization risk losing clients to competitors who blend both.
Q: What’s the role of ESG in high-net-worth wealth management today?
ESG is no longer optional—it’s a differentiator. UHNWIs increasingly demand impact alongside returns, whether through private equity in renewable energy or philanthropic structuring. The challenge for banks is balancing financial performance with ethical investing—a client who wants 10% returns with zero carbon footprint is a tough sell, but those who can deliver it command premium fees.
Q: Are there regions where HNW client acquisition is easier?
No region is "easy," but some are more strategic. The Middle East and Asia offer high-growth potential due to dynasty wealth, while Europe and the U.S. have mature markets with strict compliance. The key isn’t the region—it’s local expertise. A bank in Singapore might struggle with a Russian oligarch’s tax structuring, while a Swiss private banker might fail to navigate a Chinese tech founder’s cross-border risks.
