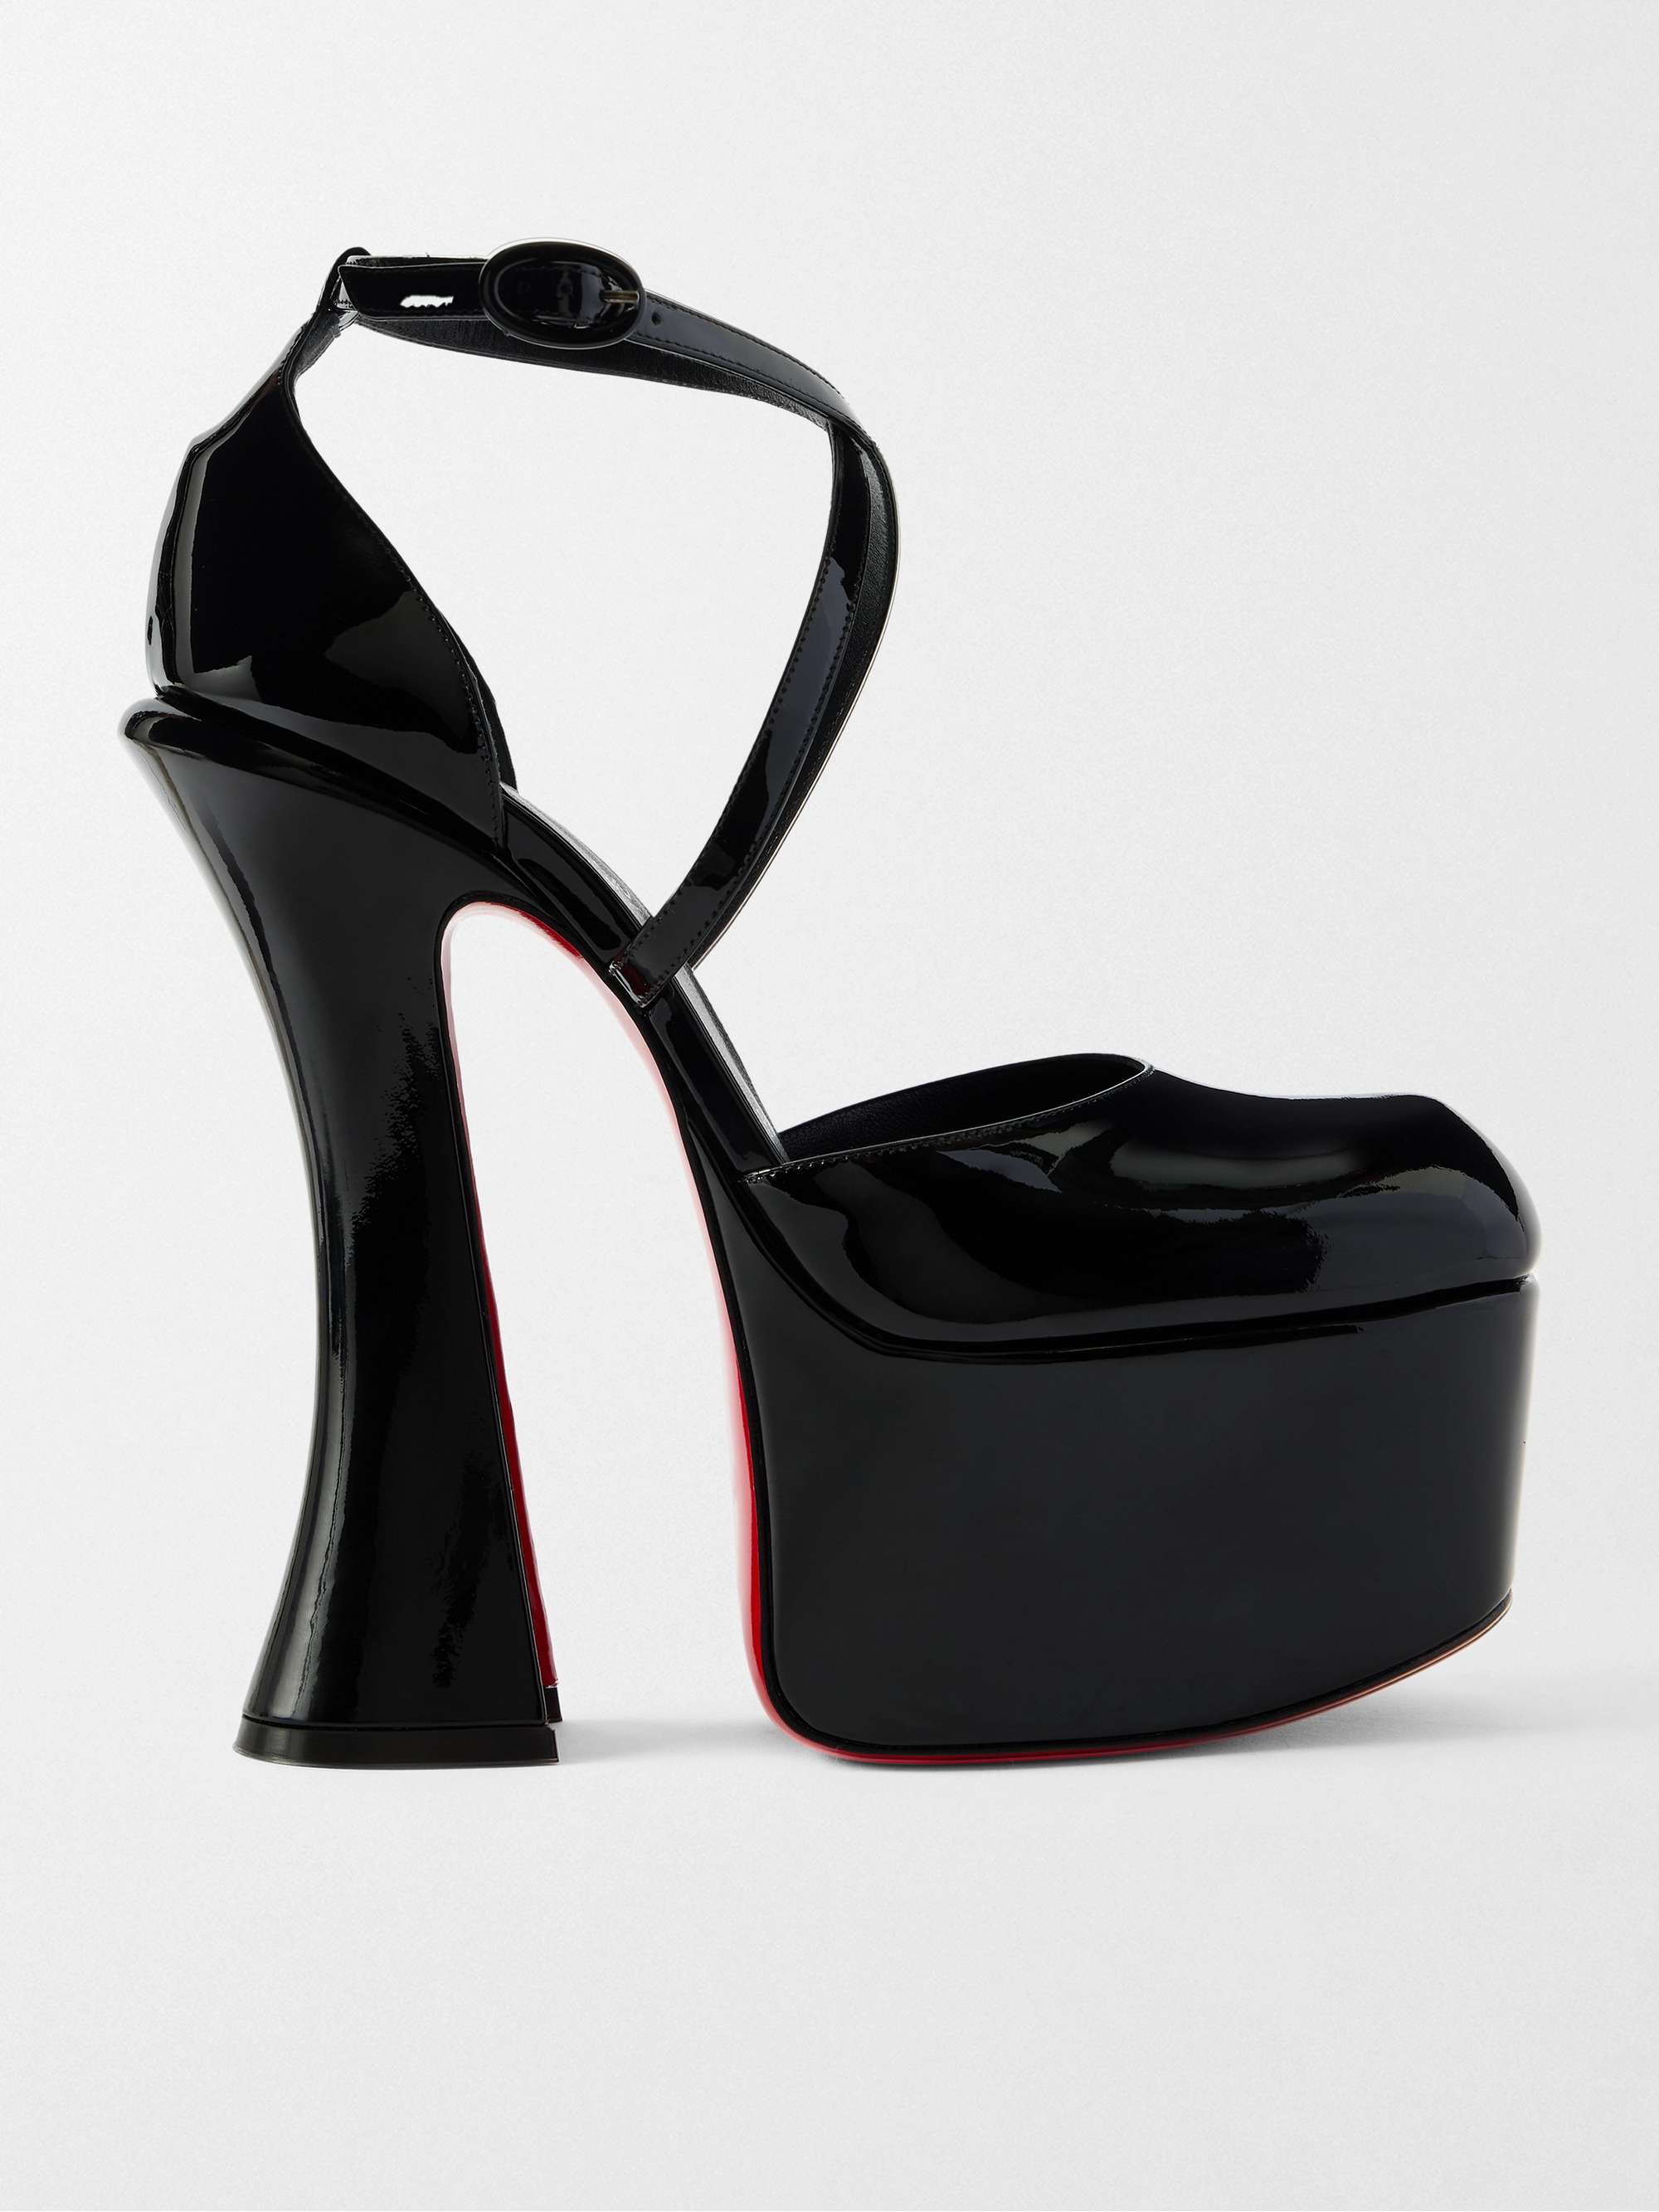
Breaking Down the Numbers
The Christian Louboutin net worth isn’t a static figure but a dynamic one, shaped by revenue streams that extend beyond traditional retail. The brand operates on three pillars: direct sales (through its own boutiques and e-commerce), wholesale partnerships with luxury retailers, and licensing agreements for fragrances, accessories, and even collaborations (like the 2019 partnership with Netflix’s Emily in Paris). Each pillar carries its own risk-reward profile. Direct sales, for instance, offer higher margins but require heavy investment in physical and digital infrastructure. Wholesale, meanwhile, expands reach but at the cost of diluted brand control. Licensing, the most speculative of the three, can multiply revenue overnight—or fizzle if the product doesn’t resonate. What sets Louboutin apart is its vertical integration. Unlike many designers who outsource production entirely, the brand maintains a significant portion of its manufacturing in France and Italy, where labor costs are high but quality standards are non-negotiable. This approach ensures consistency but also inflates production expenses. The red sole isn’t just paint; it’s a meticulous application process that takes skilled artisans hours per pair. Industry estimates suggest that Louboutin’s gross margins hover around 40-50%, well above the industry average for luxury footwear. The key variable, however, is how much of that profit trickles down to Louboutin personally versus reinvestment in the business.The Verified Baseline
The only concrete data points come from legal filings and rare interviews. In 2019, Louboutin confirmed to Vogue that the brand’s annual revenue exceeded €500 million—a figure that would place it among the top 10 independent luxury houses in Europe. That same year, the company opened its first freestanding store in New York’s SoHo district, a $10 million investment that signaled expansion beyond its traditional strongholds in Paris, Dubai, and Tokyo. More telling was the 2021 announcement of a €100 million partnership with LVMH’s private equity arm, though Louboutin retained full creative and operational control. This deal wasn’t a sale; it was a strategic injection of capital to fuel growth without surrendering equity. Public records also reveal the brand’s global footprint. As of 2023, Louboutin operated over 100 boutiques worldwide, with plans to open 20 more by 2025. The company employs roughly 1,200 people across its ateliers, corporate offices, and retail locations. While these numbers don’t directly translate to Louboutin’s personal wealth, they provide context for the scale of the operation he oversees. The brand’s ability to sustain such a workforce—and pay artisans premium wages—is a testament to its financial health. Yet without audited financial statements, even these figures are incomplete.What the Estimates Suggest
Industry estimates for Christian Louboutin’s net worth vary widely, reflecting the brand’s private nature. A 2022 report by Business of Fashion suggested the company’s enterprise value could exceed $2 billion, with Louboutin’s personal stake worth between $1.5 billion and $2 billion. These figures assume a conservative valuation of 60% ownership (the remainder held by investors or retained earnings). The upper end of the range aligns with Louboutin’s refusal to pursue aggressive cost-cutting—his insistence on French leather and hand-painted soles ensures premium pricing but limits scalability. Speculation intensifies when considering the brand’s untapped markets. Louboutin has yet to launch a full-fledged men’s line, despite demand from male customers willing to pay luxury prices for the red sole. A men’s collection could add $100–200 million annually to revenue, according to estimates from Luxury Daily. Similarly, the brand’s fragrance division, launched in 2011, remains underdeveloped compared to competitors like Chanel or Dior. If Louboutin were to double down on scent, analysts project potential revenue of €50–100 million per year—a drop in the bucket compared to the brand’s footwear dominance but a meaningful upside. The wild card? A potential IPO or partial sale. Louboutin has ruled out going public, but a strategic sale to a conglomerate like LVMH or Kering could push his net worth into the $3 billion+ range—if he were to cash out.
Case Study: A Closer Look
No single decision illustrates Louboutin’s financial acumen better than his 2015 lawsuit against Yves Saint Laurent. The case wasn’t just about protecting a trademark; it was a masterclass in brand equity. When Saint Laurent introduced its own red-soled shoe, Louboutin sued for €100,000 per infringing pair sold in France. The lawsuit succeeded, forcing Saint Laurent to redesign its shoes—and sending a message to the industry that Louboutin would defend his intellectual property at any cost. The legal battle cost millions in fees, but the long-term payoff was immeasurable: the red sole became synonymous with Louboutin, not just high heels. The financial impact of the lawsuit is harder to quantify. Legal experts estimate Louboutin spent €5–10 million on litigation, but the brand’s stock (if it had one) would have surged on the news. Instead, the victory reinforced Louboutin’s position as the undisputed king of red soles, allowing the brand to charge a 20–30% premium on its products. Today, a pair of Louboutin heels retails for $600–$1,200, with limited-edition models selling for $2,000+. The red sole isn’t just a design choice; it’s a $1 billion+ revenue driver for the company.“You don’t copy Louboutin. You aspire to Louboutin.” — Christian Louboutin, 2017 interview with The GuardianThe lawsuit also had a secondary effect: it deterred competitors. Brands like Jimmy Choo and Manolo Blahnik avoided red-soled designs in their collections, further cementing Louboutin’s monopoly. This isn’t just about sales; it’s about perceived exclusivity. Consumers don’t just buy the shoe; they buy into the myth that only Louboutin can deliver the “real” red sole.
| Factor | Estimated Impact on Net Worth |
|---|---|
| Trademark enforcement (lawsuits, licensing) | +$500M–$1B (long-term brand protection) |
| Direct-to-consumer expansion (boutiques, e-commerce) | +$300M–$500M (higher margins than wholesale) |
| Celebrity collaborations (e.g., Netflix, Lady Gaga) | +$100M–$200M (marketing ROI) |
| Untapped men’s line potential | +$200M–$400M (if pursued) |
| Possible partial sale or IPO (speculative) | +$1B–$3B (if Louboutin exits majority stake) |
What This Means Going Forward
Louboutin’s greatest asset may be his refusal to chase trends. While fast-fashion brands mimic his designs, Louboutin moves at his own pace—releasing two collections per year, not the industry standard of six. This deliberate slowness ensures scarcity, which in turn sustains pricing power. The brand’s Christian Louboutin net worth will continue to grow as long as it maintains this balance: enough innovation to stay relevant, but enough tradition to justify its premium. The biggest wild card is digital transformation. Louboutin’s e-commerce presence is strong but not dominant; the brand still relies heavily on physical retail. If it fails to modernize its online experience—think AR try-ons, subscription models, or AI-driven personalization—it risks losing ground to younger brands like Bottega Veneta or Prada. Conversely, if Louboutin embraces technology without diluting its craftsmanship, it could unlock another $500 million in revenue within a decade. The challenge is to digitize without democratizing. The red sole must remain exclusive, even in the age of Instagram.
Conclusion
The Christian Louboutin net worth is more than a number; it’s a testament to the power of obsession. Louboutin didn’t build an empire by chasing the latest fashion cycles. He built one by protecting a single, brilliant idea—the red sole—and turning it into a global phenomenon. The brand’s financial success isn’t accidental; it’s the result of relentless enforcement of intellectual property, a ruthless focus on quality, and an understanding that luxury isn’t about accessibility, but aspiration. As Louboutin approaches his 70s, the question isn’t whether his net worth will keep rising—it’s how. Will he sell a stake to a conglomerate and retire as a billionaire? Will he pass the torch to a successor and risk diluting the brand’s magic? Or will he continue to innovate within the constraints of his own vision? One thing is certain: the red sole will always be worth more than the shoe it adorns.Comprehensive FAQs
Q: How much is Christian Louboutin worth in 2024?
Exact figures aren’t public, but industry estimates place his Christian Louboutin net worth between $1.5 billion and $2 billion, based on brand valuation and ownership stakes. Forbes previously suggested $1.2 billion in 2015, but revenue growth and strategic investments likely increased that figure.
Q: Does Christian Louboutin own his brand outright?
He retains majority control, but the company has raised capital through private investors, including a €100 million deal with LVMH’s private equity arm in 2021. Louboutin has repeatedly stated he has no plans to sell full ownership or go public.
Q: How does Louboutin’s wealth compare to other shoe designers?
Louboutin’s Christian Louboutin net worth surpasses most peers. Jimmy Choo’s brand was sold to Tapestry in 2017 for $1.2 billion, but Choo himself is estimated at $100–200 million. Manolo Blahnik’s net worth is around $300 million, while Salman Rushdie (who owns the brand) holds the majority stake. Louboutin’s independence and global dominance put him in a league of his own.
Q: What’s the most valuable part of Louboutin’s business?
Footwear accounts for 70–80% of revenue, with handbags and accessories making up the rest. The red sole is the brand’s $1 billion+ asset—both as a product and a trademark. Licensing (fragrances, collaborations) and direct sales contribute significantly, but the core remains the iconic shoe.
Q: Has Louboutin ever sold a stake in his company?
Yes, but strategically. The €100 million investment from LVMH in 2021 wasn’t a sale—it was equity financing to fuel expansion without losing creative control. Earlier, Louboutin sold a minority stake to Blackstone in 2007 for $200 million, but he reacquired it in 2011 for $300 million, demonstrating his commitment to ownership.
Q: Could Louboutin’s net worth grow if he launched a men’s line?
Absolutely. Industry analysts estimate a men’s collection could add $100–200 million annually to revenue. Louboutin has resisted, citing a focus on his core audience, but if demand persists, it could boost his net worth by $500 million+ over five years. The risk? Diluting the brand’s feminine identity.
Q: What’s the biggest threat to Louboutin’s wealth?
Two factors: counterfeiting (which erodes brand value) and failing to adapt to digital retail. Louboutin has aggressively sued counterfeiters, but the rise of fast-fashion replicas remains a challenge. On the digital front, if the brand lags in e-commerce innovation, it could lose younger consumers to competitors like Bottega Veneta.
Q: Would selling to LVMH or Kering increase Louboutin’s personal fortune?
Potentially, but at a cost. A full acquisition could net him $2–3 billion, but he’d lose creative control and independence. Louboutin has repeatedly said he’d never sell the brand—his fortune is tied to its autonomy. A partial sale (like the 2021 deal) is more likely, allowing capital infusion without surrendering power.
