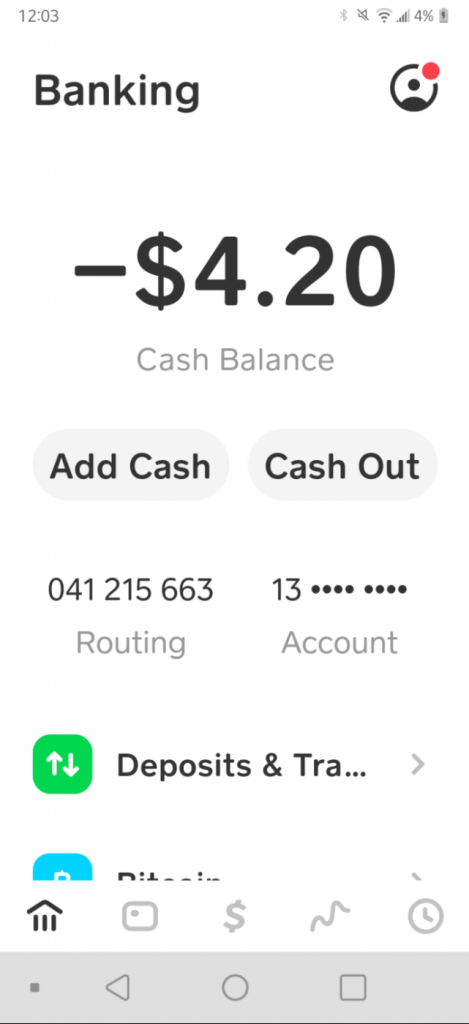
Cash App’s seamless interface and viral growth have made it a staple for millions handling everything from split bills to freelance payments. But beneath its polished surface lies a feature many users overlook: the ability to go into a
negative balance. For some, it’s a temporary convenience; for others, it’s a financial misstep with lasting repercussions. The consequences of a Cash App negative balance—whether through unauthorized overdrafts, forgotten fees, or accidental transactions—can extend beyond a single account. They may affect credit scores, trigger bank penalties, or even lead to account restrictions. Understanding these risks isn’t just about avoiding embarrassment; it’s about protecting your financial stability in an ecosystem where instant transactions often outpace oversight.
The problem starts with how Cash App frames its limits. Unlike traditional banks, which clearly outline overdraft policies, Cash App’s terms on negative balances are buried in fine print. Users might assume a small negative balance is harmless, only to wake up to unexpected holds, frozen funds, or even temporary account locks. Industry estimates suggest that
overdraft-related disputes—including those tied to Cash App—have surged by nearly 30% in the past two years, as digital wallets blur the line between spending and borrowing. Yet most users remain unaware of how these balances interact with linked bank accounts, credit checks, or third-party services that may flag them as red flags.
What follows is a breakdown of the often misunderstood
cash app negative balance consequences, the myths that perpetuate risky behavior, and the concrete steps to mitigate them. The goal isn’t fearmongering but clarity—because once a negative balance becomes a habit, the fallout can be harder to reverse than most realize.

Common Myths About Cash App Negative Balance Consequences
The allure of Cash App’s flexibility has given rise to several misconceptions about negative balances. One persistent belief is that a temporary dip below zero is no different from a bank overdraft—just a minor inconvenience. Another is that Cash App’s instant transfer feature acts as a safety net, shielding users from fees or penalties. These assumptions ignore the platform’s unique mechanics, where negative balances can trigger cascading effects, from linked account holds to delayed payouts for sellers. The reality is far more nuanced: what starts as a small negative balance can escalate into a cycle of fees, restricted access, or even account termination if left unchecked.
The confusion is compounded by Cash App’s lack of real-time transparency. Unlike credit cards, which provide itemized statements, Cash App’s activity feed often lumps transactions together, making it easy to overlook a growing negative balance. Users may not realize they’ve triggered an overdraft until they attempt a withdrawal or receive a notification about insufficient funds. This opacity has led some to treat Cash App as a quasi-banking service, unaware that its policies don’t align with traditional financial safeguards.
####
Myth 1: A Negative Balance Only Affects Cash App Funds
Many assume that if they’re negative on Cash App, the impact is isolated to that account. In truth, a negative balance can seep into linked bank accounts, especially if Cash App places a hold or initiates a transfer to cover the deficit. Some users have reported their primary bank account being flagged for suspicious activity after Cash App’s automated systems attempted to reconcile the balance, leading to temporary freezes. Additionally, if the negative balance persists, Cash App may restrict certain features—like sending or receiving money—until it’s resolved, creating a feedback loop where users can’t access funds to fix the issue.
The interplay between Cash App and external banks is rarely explained upfront. For example, if a user’s linked debit card is declined due to insufficient funds, Cash App may retry the transaction, exacerbating the negative balance. This can happen repeatedly until the user manually intervenes, often by transferring money from another account—a move that might itself trigger fees. The illusion of separation between Cash App and traditional banking is one of the biggest blind spots for users.
####
Myth 2: Cash App Won’t Charge Fees for a Negative Balance
Fees are the silent killer of negative balances, yet many users operate under the assumption that Cash App won’t penalize them for going into the red. The platform’s fee structure is deliberately ambiguous: while Cash App doesn’t charge traditional overdraft fees like banks, it does impose instant transfer fees (1.5% or $0.25, whichever is higher) and may apply holds or restrictions that indirectly cost money. For instance, if a user’s negative balance triggers a hold on their linked account, they might face late fees from their bank or miss automatic payments, both of which compound the financial strain.
Even more insidious is how Cash App’s
Boost and Cash Card features can interact with negative balances. A user with a negative balance might still use their Cash Card for purchases, only to see those transactions deducted from an already depleted account. Some have reported their Cash Card being declined mid-transaction, leading to additional merchant fees or service charges. The cumulative effect of these interactions often far exceeds the initial negative balance, turning a seemingly minor oversight into a costly mistake.
####
Myth 3: You Can Always Fix a Negative Balance Quickly
The idea that a negative balance is easily reversible ignores the administrative hurdles Cash App can impose. Users who attempt to resolve a negative balance by transferring funds may find themselves stuck in a loop: Cash App’s system might reject the transfer if the linked account also has insufficient funds, or it could take days for the platform to process the correction. In some cases, users have described being locked out of their account entirely until they contact support—a process that can take hours or even require verification steps that delay resolution further.
Worse, if the negative balance is tied to a dispute or fraud claim, Cash App may freeze the account while it investigates, leaving users unable to access their funds for weeks. This is particularly problematic for freelancers or small business owners who rely on Cash App for payouts. The assumption that a negative balance is a temporary glitch overlooks the platform’s discretionary policies, which can turn a simple oversight into a prolonged financial setback.
What Holds Up to Scrutiny
At its core, the
cash app negative balance consequences stem from three verifiable factors: automated holds, linked account interactions, and platform discretion. Cash App’s terms of service explicitly state that it may place holds on funds to cover negative balances, and these holds can persist until the balance is resolved—sometimes indefinitely if the user fails to respond to notifications. Unlike banks, which have standardized overdraft policies, Cash App’s approach is reactive, meaning users often learn the rules only after they’ve been applied.
The evidence also shows that negative balances don’t exist in a vacuum. If a user’s linked bank account is also in a precarious state, Cash App’s attempts to reconcile the balance can trigger additional penalties. For example, a user with a negative Cash App balance might see their bank impose its own overdraft fees if Cash App initiates a transfer to cover the deficit. This domino effect is rarely communicated clearly, leaving users to navigate the aftermath without a roadmap.
"Cash App’s negative balance policies are designed for convenience, not protection. Users assume they’re shielded from the same risks as traditional banking, but the reality is far more exposed." — Financial analyst specializing in fintech disputes
|
Common Belief | What the Evidence Says |
|----------------------------------|-------------------------------------------------------------------------------------------|
| Negative balances are isolated | Linked bank accounts can face holds or freezes, and third-party services may flag them. |
| No fees apply | Instant transfers, holds, and restricted access can incur indirect costs. |
| Quick fixes are always possible | Administrative delays, account locks, and support bottlenecks can prolong resolution. |
Why the Confusion Persists
Cash App’s marketing emphasizes speed and simplicity, which obscures the underlying complexity of its financial ecosystem. The platform’s design encourages users to treat it as a primary account—complete with direct deposits, bill payments, and even tax refunds—without disclosing how negative balances interact with these features. For instance, a user might deposit their paycheck into Cash App, only to see it immediately offset by a negative balance from a previous transaction, leaving them with insufficient funds for rent or utilities.
The lack of real-time alerts also plays a role. While Cash App sends notifications for certain transactions, it doesn’t proactively warn users when their balance is trending negative or when a linked account might be affected. This silence allows the problem to fester until it’s too late to act. Additionally, Cash App’s customer support—often cited as a pain point—can leave users in limbo when trying to resolve negative balance issues, further entrenching the confusion.
Conclusion
The cash app negative balance consequences are less about the balance itself and more about the ripple effects it unleashes. What starts as a minor oversight can quickly become a financial quagmire, especially for those who treat Cash App as both a wallet and a bank. The myths surrounding its safety net are dangerous precisely because they’re plausible: the platform’s design makes it easy to assume risks are mitigated. But the reality is that negative balances can expose users to holds, fees, and account restrictions that traditional banking would make clearer upfront.
The key to avoiding these pitfalls is vigilance. Users should treat Cash App as an auxiliary tool rather than a primary account, monitor linked balances closely, and never assume a negative balance will resolve itself. For those already caught in the cycle, the first step is acknowledging the problem before it escalates. The consequences of inaction are rarely just financial—they can disrupt livelihoods, damage credit, and erode trust in digital banking tools meant to simplify life, not complicate it.
Comprehensive FAQs
#### Q: Can a negative Cash App balance affect my credit score?
A: Not directly, but indirectly it can. If Cash App places a hold on your linked bank account and the bank reports the hold as a "pending transaction," it might temporarily reduce your available credit, which could impact your credit utilization ratio. Additionally, if you’re forced to take out a loan or use a credit card to cover the negative balance, that new debt could appear on your credit report.
#### Q: How long can Cash App keep my account restricted due to a negative balance?
A: There’s no fixed timeline, but Cash App’s terms suggest restrictions can persist until the balance is resolved. Some users report being locked out for days to weeks, depending on whether they respond to notifications or contact support. If the negative balance is tied to a dispute, resolution times can stretch even longer.
#### Q: Will Cash App charge me fees for going negative?
A: Cash App doesn’t charge traditional overdraft fees, but you may incur instant transfer fees (1.5% or $0.25) if you use that feature to cover the balance. More critically, negative balances can trigger holds on linked accounts, leading to bank fees or missed payments—both of which compound the financial hit.
#### Q: Can I dispute a negative balance if I think it’s a mistake?
A: Yes, but the process isn’t straightforward. You’ll need to contact Cash App support and provide evidence (e.g., transaction records, screenshots) that the negative balance was unauthorized. Disputes can take weeks to resolve, and Cash App may require additional verification before reversing the balance. If the negative balance was due to your own transactions, disputes are unlikely to succeed.
#### Q: What happens if I ignore a negative balance in Cash App?
A: Ignoring it risks permanent account restrictions, holds on linked funds, and potential penalties from your bank. Over time, Cash App may disable sending/receiving money until the balance is resolved. For businesses or freelancers using Cash App for payouts, this can mean lost income while the issue drags on.