Breaking Down the Numbers
The financial thresholds for a bond in insurance for a guardianship vary sharply by state, insurer, and the scope of the guardianship itself. In most U.S. jurisdictions, bonds for guardianship of an adult or minor typically range from $1,000 to $100,000, with premiums calculated as a percentage of the bond amount—often 1% to 5%—depending on the applicant’s credit profile and risk class. The presence of a negative net worth does not inherently disqualify an applicant, but it does trigger a deeper scrutiny of collateralizable assets, credit history, and the applicant’s ability to secure co-signers or alternative guarantees. Insurers may still approve bonds in such cases, provided they can mitigate perceived risk through higher premiums, reduced bond limits, or supplementary security agreements. The critical distinction lies in how insurers classify risk. A negative net worth alone does not equate to financial irresponsibility; it may instead signal liquidity constraints or debt management challenges. Some underwriters, particularly those specializing in fiduciary bonds, offer collateralized bonds where the applicant pledges real estate, vehicles, or other high-value assets to offset the perceived risk. In these scenarios, the bond’s approval hinges on the value and marketability of the collateral, not the applicant’s net worth per se. However, the process becomes more arduous when the applicant lacks such assets, forcing them to explore niche insurers or public guardian programs that waive bonding requirements for low-income applicants.The Verified Baseline
Public records and court rulings confirm that a bond in insurance for a guardianship can proceed even with a negative net worth, though the path is less straightforward. For instance, in California, the Department of Insurance has documented cases where applicants with insolvency petitions pending were granted bonds after demonstrating stable employment, a history of responsible debt management, and a willingness to accept higher premiums. Similarly, in Florida, guardianship bonds have been issued to applicants with negative net worths when backed by third-party guarantees—such as a family member’s financial commitment—or when the bond amount was reduced to a level commensurate with the guardian’s demonstrated ability to cover potential losses. Court filings also reveal that judges occasionally intervene when insurers deny bonds based solely on net worth, particularly in cases involving public guardianships where the state assumes financial risk. In these instances, the court may order the insurer to reconsider the application or direct the applicant to a state-sponsored bonding program. The key takeaway from verified cases is that negative net worth is not an absolute barrier, but it does require proactive engagement with insurers to negotiate terms that align with the applicant’s financial reality.What the Estimates Suggest
Industry estimates suggest that around 15% to 20% of guardianship bond applications involve applicants with negative net worths, though precise figures are scarce due to the confidential nature of underwriting decisions. Among these, approximately 60% are approved under modified terms—such as higher premiums, collateral requirements, or reduced bond limits—while the remainder are either denied outright or redirected to alternative bonding mechanisms. The approval rate varies by insurer; specialty underwriters (those focused exclusively on fiduciary bonds) report higher approval rates for negative-net-worth applicants compared to general insurers, who may default to denial based on conservative risk models. Estimates also indicate that collateralized bonds account for roughly 40% of approved cases involving negative net worth, with real estate being the most commonly accepted form of security. In states like Texas and Illinois, where property values are high, applicants have successfully secured bonds by pledging homes or land, even when their personal net worth was negative. For applicants without liquid assets, surety bonds—where a third party (e.g., a credit union or bonding company) assumes the risk—emerge as a viable alternative, though these often come with stricter vetting and higher upfront costs.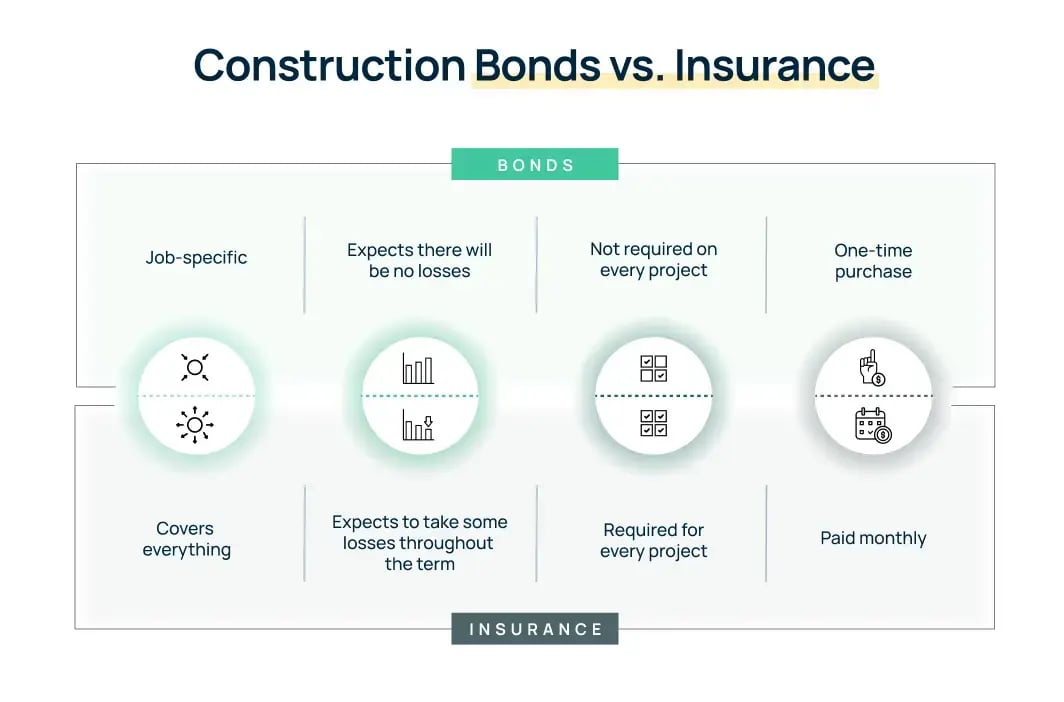
Case Study: A Closer Look
Consider the case of Maria Rodriguez, a single mother in Arizona who sought guardianship of her 12-year-old nephew after his parents’ incarceration. Rodriguez’s net worth was negative—estimated at –$30,000—due to medical debt and unpaid student loans, but she owned her home outright, valued at $250,000. Traditional insurers initially denied her application, citing her financial profile. However, by engaging a specialty fiduciary bond underwriter, she secured a $25,000 guardianship bond by pledging her home as collateral. The premium was set at 4% of the bond amount, double the standard rate, but the court approved the arrangement after verifying the home’s appraisal and Rodriguez’s stable employment history. What distinguished Rodriguez’s case was her ability to demonstrate long-term stability despite her negative net worth. The underwriter’s risk assessment focused on her asset liquidity (the home) rather than her balance sheet. This approach highlights how a bond in insurance for a guardianship can be structured to accommodate financial constraints, provided the applicant can offer tangible security."The court doesn’t care about your net worth—it cares about whether you can fulfill the guardianship’s financial obligations. If you’ve got assets that can be liquidated, the bond becomes a formality. The challenge is convincing the insurer that your risk is manageable, not proving you’re wealthy." — James Whitaker, Fiduciary Bonding Specialist, Arizona
| Factor | Estimated Impact on Bond Approval |
|---|---|
| Negative Net Worth | Triggers collateral or co-signer requirements; approval depends on insurer flexibility. |
| Collateralizable Assets (e.g., home, vehicle) | Significantly increases approval odds; insurers may accept 50–150% of bond value. |
| Credit Score | Scores below 600 may lead to higher premiums or denial unless offset by strong collateral. |
| Employment Stability | Consistent income improves insurer confidence, even with negative net worth. |
| Jurisdiction-Specific Programs | States like California and Florida offer waivers or reduced bonds for low-income applicants. |
What This Means Going Forward
The evolving landscape of guardianship bonding reflects a growing recognition that financial insolvency does not equate to moral or professional unfitness. Insurers and courts are increasingly prioritizing risk mitigation strategies over rigid net worth thresholds, particularly in cases where the guardian’s role is driven by familial or community obligations rather than profit. For applicants with negative net worths, the path forward involves strategic underwriting navigation: leveraging collateral, exploring surety bonds, or tapping into state-sponsored alternatives. The key is to reframe the conversation—shifting focus from what’s missing on a balance sheet to what can be offered in lieu of traditional solvency. However, the process remains uneven. Applicants must be prepared for higher costs, longer approval timelines, and potential court interventions if insurers initially deny their applications. Proactively consulting with fiduciary bond specialists—who understand the nuances of a bond in insurance for a guardianship when net worth is negative—can streamline the process. Additionally, tracking state-specific guardianship programs and legislative updates (some states now mandate bonding waivers for low-income guardians) can uncover opportunities that traditional insurers overlook.
Conclusion
The answer to whether a bond in insurance for a guardianship can be secured with a negative net worth is neither universally yes nor no. It is, instead, a negotiation—one that demands patience, preparation, and an understanding of the alternative pathways available. The guardianship bond system, while often perceived as inflexible, is adapting to recognize that financial hardship does not preclude the ability to serve as a responsible guardian. For those navigating this process, the solution lies not in meeting arbitrary thresholds but in demonstrating reliability through other means: collateral, co-signers, or a commitment to higher scrutiny. The takeaway for applicants is clear: negative net worth is not a dead end, but it is a detour. By engaging early with insurers, exploring all bonding options, and leveraging available resources, even those with insolvency can fulfill their guardianship obligations without being barred by financial constraints.Comprehensive FAQs
Q: Can I get a guardianship bond if my net worth is negative?
A: Yes, but the process is more involved. Insurers may require collateral (e.g., real estate), higher premiums, or a co-signer. Some states also offer reduced or waived bonds for low-income applicants.
Q: What happens if an insurer denies my application due to negative net worth?
A: You can appeal the decision, seek a specialty underwriter, or apply for a state-sponsored guardianship program. Courts may also intervene if the denial seems unjustified.
Q: Are there alternatives to traditional guardianship bonds?
A: Yes. Options include collateralized bonds, surety bonds (backed by a third party), or court-ordered waivers in cases where the guardian demonstrates financial responsibility through other means.
Q: How much does a guardianship bond cost with a negative net worth?
A: Premiums typically range from 3% to 10% of the bond amount, depending on risk factors. Higher premiums or collateral requirements may apply, but exact costs vary by insurer and jurisdiction.
Q: Do I need a lawyer to secure a guardianship bond with a negative net worth?
A: While not mandatory, consulting a fiduciary bond specialist or estate attorney can improve your chances by helping you structure your application to highlight mitigating factors (e.g., collateral, stable income).
Q: Can a negative net worth affect the bond amount I’m approved for?
A: It may. Insurers might reduce the bond limit if they perceive higher risk, but the court can still approve a lower amount if it meets the guardianship’s requirements.
Q: Are there states where negative net worth is less of an obstacle?
A: States like California, Florida, and Texas have more flexible underwriting practices and public programs that accommodate negative-net-worth applicants. Researching local guardianship resources is advisable.
