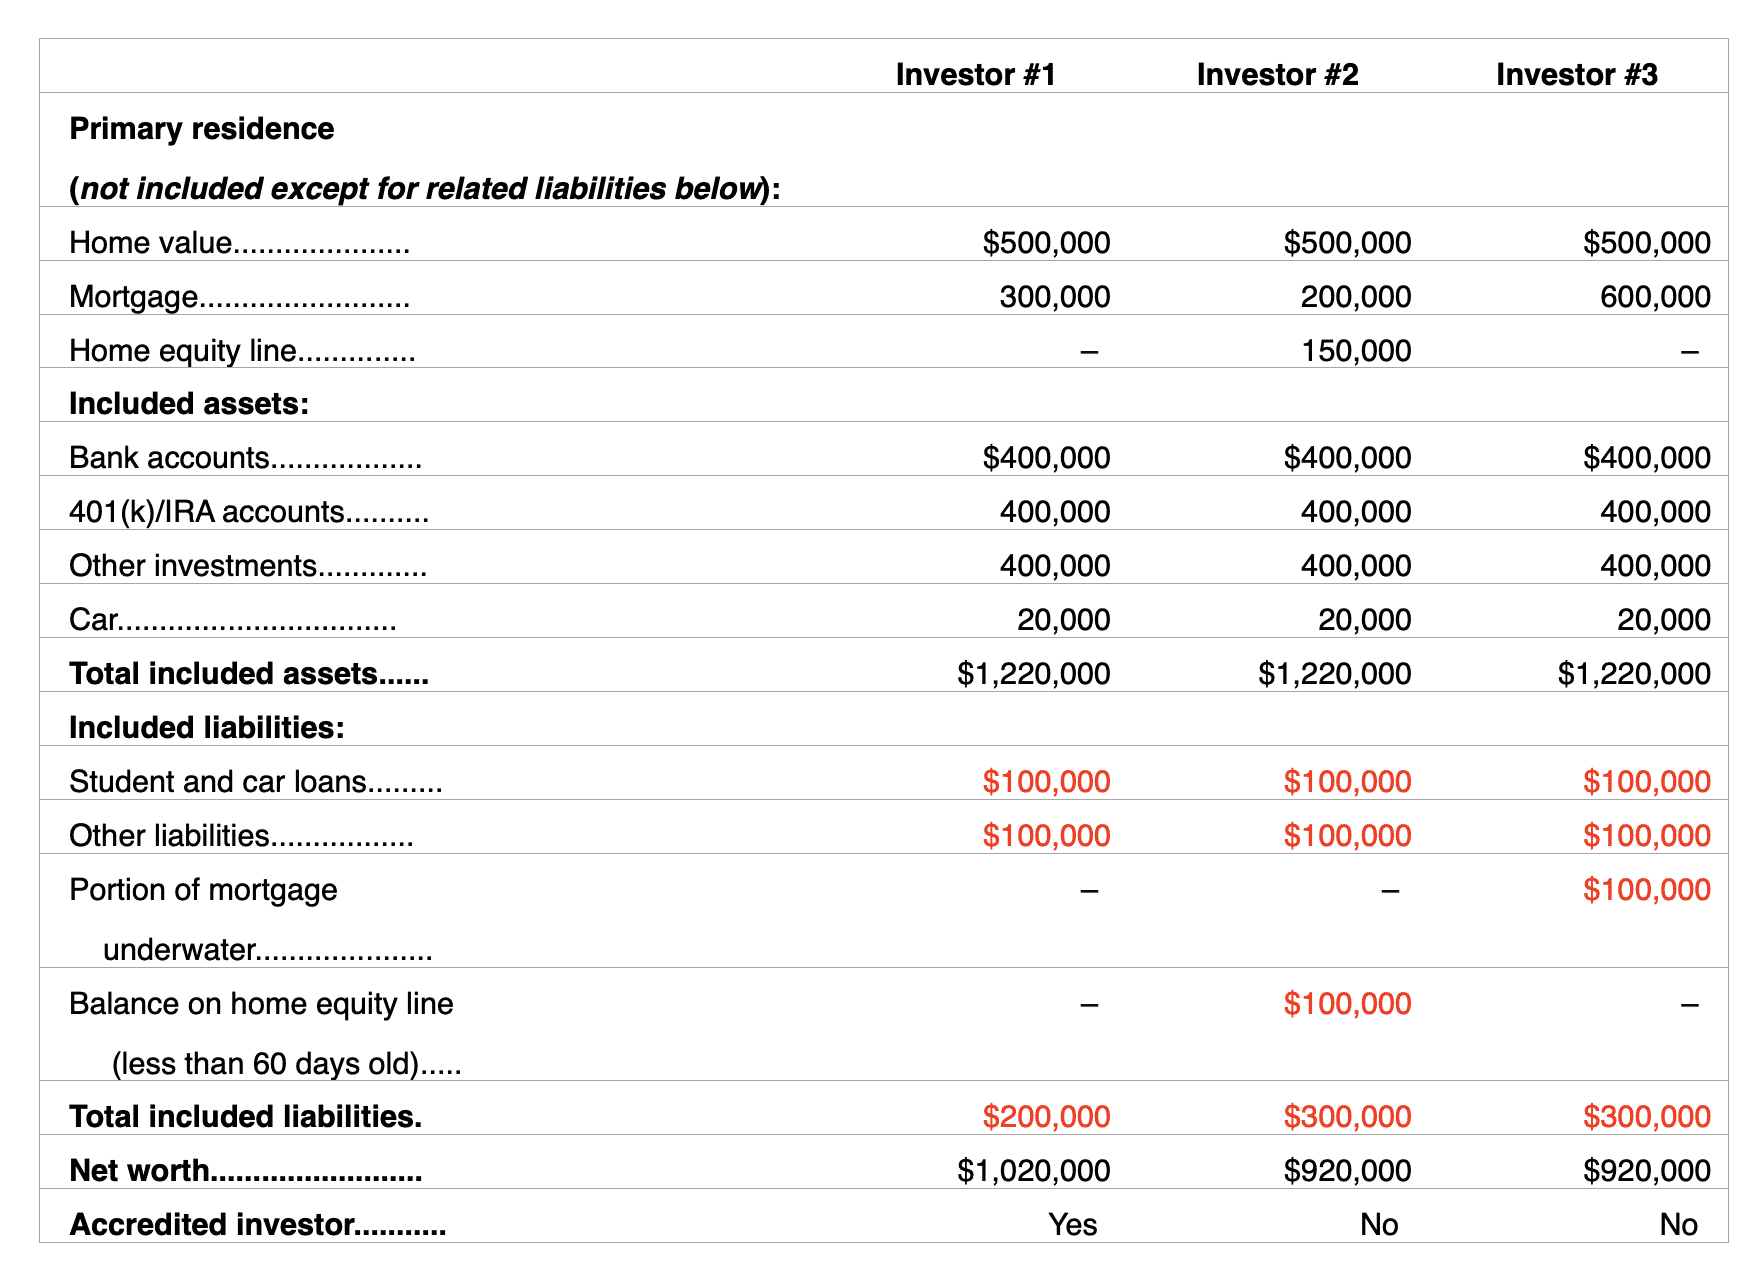
Where It All Began
The concept of net worth as a gatekeeper for high-stakes investing traces back to the 1933 Securities Act, which sought to protect retail investors from speculative risks. The original accredited investor rule, introduced in 1980, was simple: if you had $1 million in assets (excluding your home), you were presumed sophisticated enough to evaluate complex investments. The rule was designed to streamline offerings for wealthy individuals who could afford to lose their money without destabilizing the broader market. But the early years were chaotic. Broker-dealers and issuers had little guidance on how to verify net worth claims. A 1985 SEC enforcement action revealed that some firms were accepting handwritten notes from clients declaring their wealth, with no documentation. The SEC responded by tightening definitions, but the lack of standardized valuation methods persisted. By the late 1990s, as private equity and hedge funds boomed, the gap between reported net worth and actual liquidity became a major compliance headache.The Early Signs
The first red flags appeared in the dot-com era, when startup founders inflated their personal net worth by including unvested stock options or pre-revenue business valuations. One infamous case involved a biotech CEO who claimed a $20 million net worth based on his company’s private valuation—only for the SEC to later determine that the shares were worthless after the company failed to secure FDA approval. The lesson? Calculating net worth for accredited investor purposes required more than a founder’s word; it needed third-party appraisals or liquidation scenarios. Meanwhile, family offices began structuring assets to meet accredited investor thresholds without triggering tax liabilities. A 2001 Wall Street Journal investigation found that some ultra-high-net-worth individuals were using offshore trusts to exclude certain assets from their net worth calculations, only to reclassify them when applying for private fund access. The SEC’s response was to clarify that offshore entities couldn’t be used to artificially suppress net worth for eligibility purposes—a rule still enforced today.The Turning Point
The 2008 financial crisis exposed the fragility of net worth calculations. High-net-worth individuals who had relied on leveraged real estate or private equity stakes saw their portfolios shrink overnight. The SEC’s Office of Compliance Inspections and Examinations (OCIE) began auditing broker-dealers more aggressively, focusing on whether firms were properly vetting accredited investors. A 2010 report found that 30% of rejected applicants had overstated their net worth by at least 20%, often due to incorrect valuation of illiquid assets. The crisis also highlighted the disparity between calculating net worth for accredited investor status and actual risk tolerance. A hedge fund manager recounted how a client with a $10 million net worth—mostly tied up in a struggling private jet company—asked to invest in a high-risk venture fund. The manager declined, citing the SEC’s requirement that accredited investors have the capacity to sustain losses. The incident led to internal policy changes, including mandatory liquidity stress tests for applicants."The problem isn’t just the numbers—it’s the story behind them. A $1 million net worth looks great on paper, but if that money is locked in a distressed real estate syndicate, you’re not an accredited investor; you’re a liability waiting to happen." — Compliance Director, Mid-Atlantic Private Equity Firm (2015)
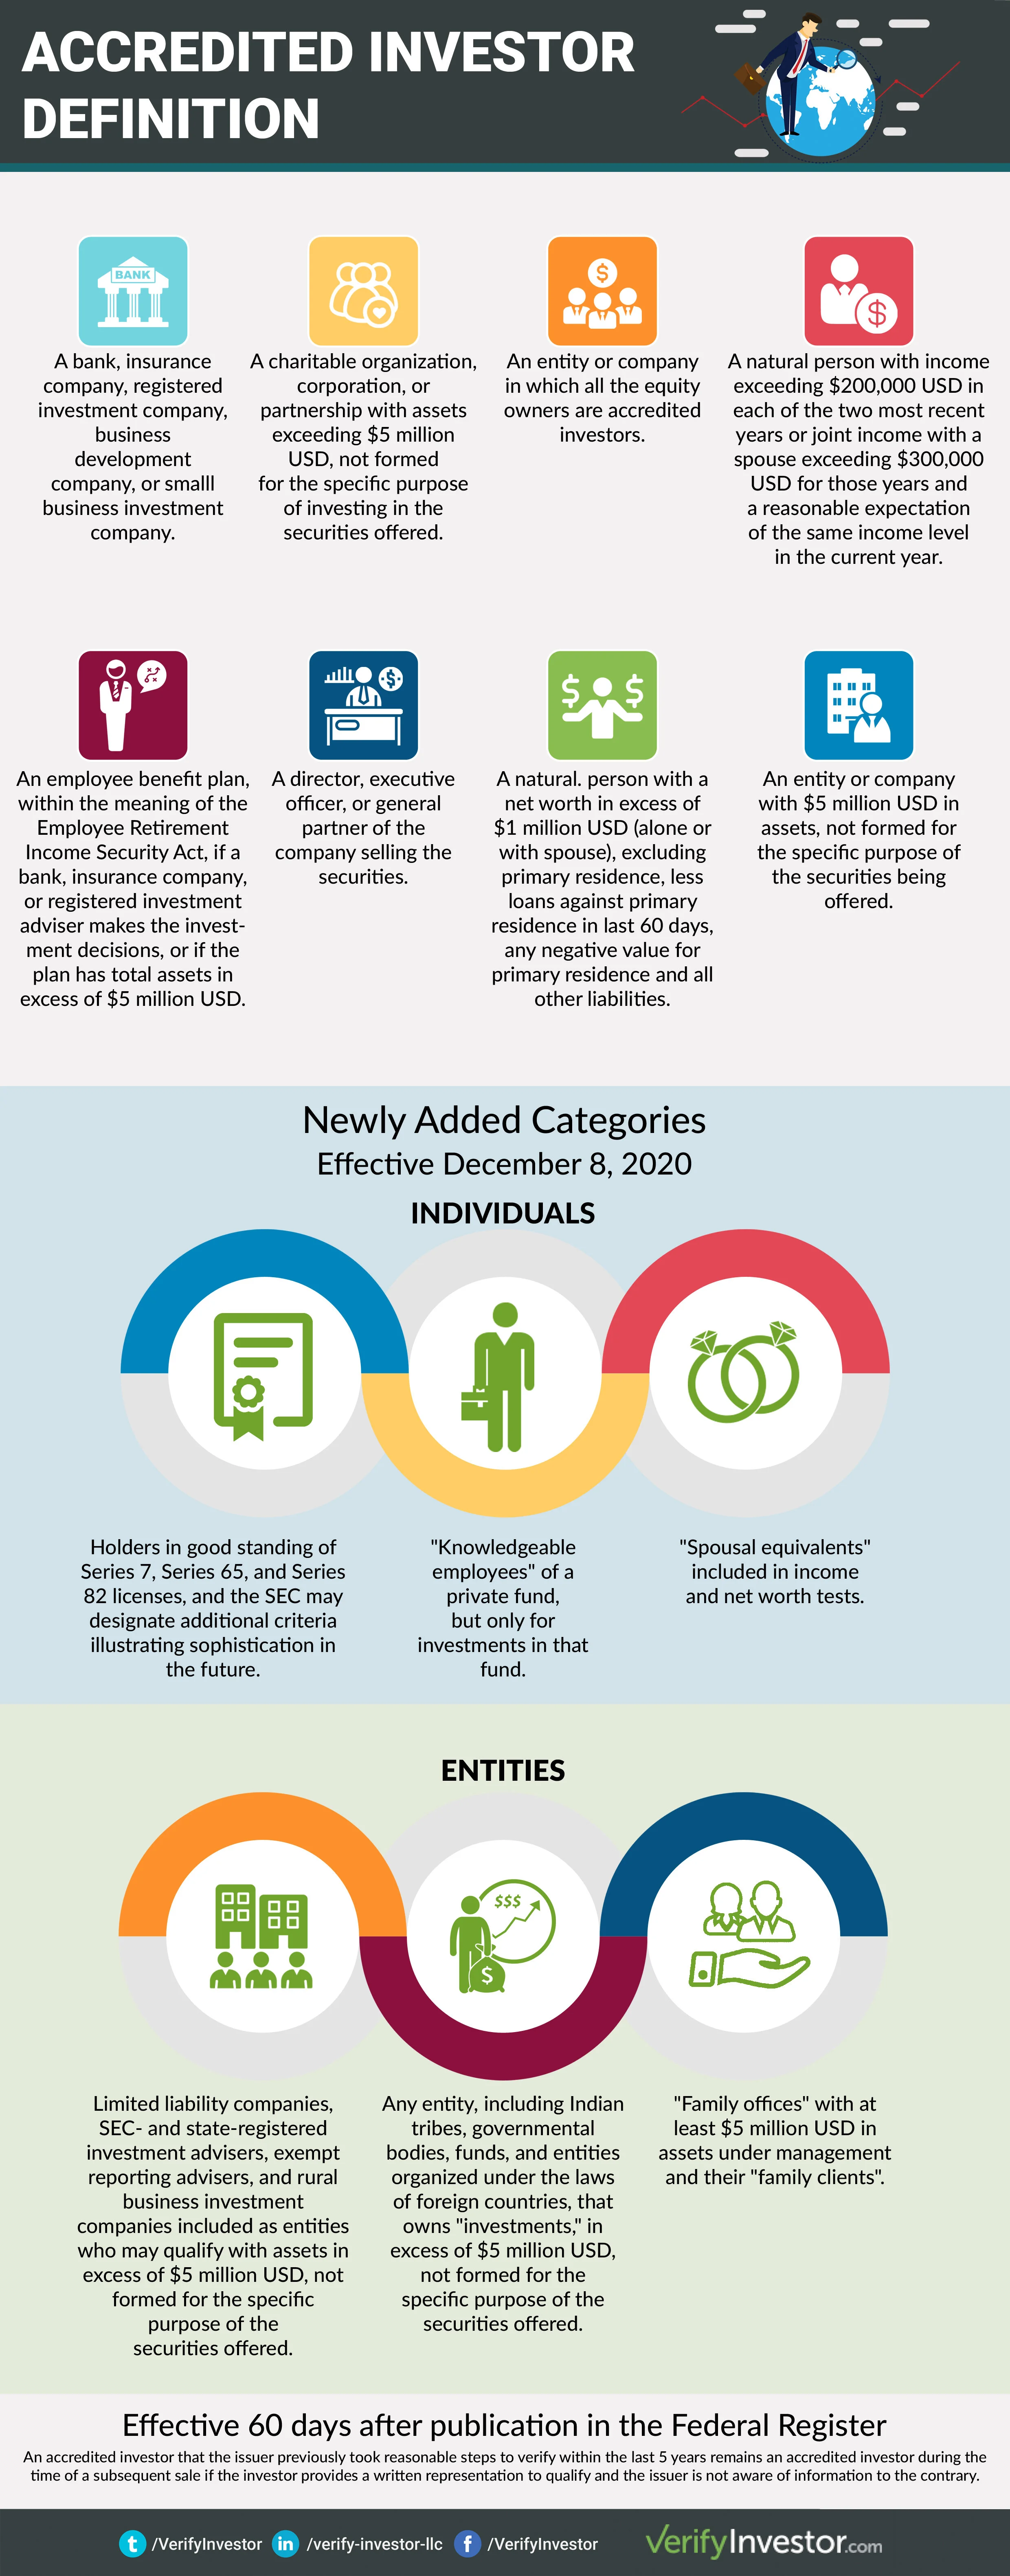
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1980–1995 | SEC establishes accredited investor rule ($1M net worth). Early cases of overstated valuations in tech and real estate. No standardized appraisal methods. |
| 1996–2005 | Dot-com boom leads to inflated startup valuations. SEC begins auditing broker-dealers for net worth verification. Offshore trusts used to manipulate eligibility. |
| 2006–2010 | Financial crisis exposes illiquid asset risks. OCIE reports 30%+ overstatements in accredited investor claims. SEC tightens offshore entity rules. |
| 2011–2015 | JOBS Act expands accredited investor pool. FINRA warns about brokerage account misrepresentations. Private fund managers adopt liquidity stress tests. |
| 2016–Present | SEC proposes rules for "natural persons" beyond income/net worth (e.g., knowledge/experience). Crypto and digital assets complicate valuations. AI tools emerge for automated net worth tracking. |
Lessons From the Journey
- Liquidity matters more than paper value. A $5 million private equity stake isn’t the same as $5 million in cash. Fund managers discount illiquid assets by 30–50% for eligibility purposes.
- Debt is a silent killer. Leveraged real estate or business loans reduce net worth in the eyes of issuers, even if the assets themselves are valuable.
- Offshore structures require disclosure. Hiding assets in trusts or foreign accounts can void accredited investor status if detected during due diligence.
- Retirement accounts are a gray area. While they count toward net worth, some fund managers exclude them from liquidity calculations.
- Professional certifications can substitute for net worth. Under proposed SEC rules, individuals with certain financial credentials (e.g., Series 7 license) may qualify even if their net worth dips below $1M.
- Documentation is non-negotiable. Bank statements, appraisals, and tax returns must align with your claimed net worth—or risk rejection.
Where Things Stand Today
Today, calculating net worth for accredited investor access is a hybrid of compliance, strategy, and psychology. High-net-worth individuals no longer just meet a threshold; they must demonstrate financial resilience. A 2023 report by the National Securities Markets Improvement Act (NSMIA) working group found that 60% of accredited investor rejections now stem from inconsistencies between reported assets and their market reality. For example, a client with a $2 million portfolio might be denied if their $1 million art collection is valued at the peak of a 2018 auction cycle rather than current market rates. The rise of digital assets has added another layer. While the SEC has yet to issue clear guidance on crypto valuations, most fund managers treat holdings like Bitcoin as illiquid—discounting them by 50% or more for net worth calculations. Meanwhile, family offices are increasingly using blockchain-based audits to prove asset ownership, reducing disputes over documentation.
Conclusion
The evolution of determining net worth for accredited investor eligibility reflects broader shifts in finance: from static definitions to dynamic, risk-adjusted assessments. What started as a simple $1 million rule has become a labyrinth of valuations, liquidity tests, and behavioral red flags. The key takeaway? Net worth isn’t just a number—it’s a narrative. And in the world of private investing, the best stories are backed by audits, not assumptions. For those navigating this terrain, the advice remains consistent: don’t overstate, don’t understate, and always assume someone will ask for proof. The accredited investor label isn’t just a passkey to exclusive deals; it’s a promise of financial sophistication. And in an era where compliance officers cross-reference your LinkedIn with your tax returns, that promise starts with the numbers.Comprehensive FAQs
Q: Does my primary residence count toward accredited investor net worth?
No. The SEC explicitly excludes the value of your primary residence from the $1 million net worth threshold. However, secondary properties or rental real estate are included at fair market value.
Q: How are private business stakes valued for net worth calculations?
Private company shares must be valued at fair market value, not book value or peak valuation. Fund managers often use a 30–50% discount for illiquidity, and some require third-party appraisals (e.g., from a certified valuation analyst).
Q: Can I use retirement accounts (e.g., 401(k), IRA) to meet the net worth requirement?
Yes, retirement accounts count toward net worth, but some fund managers may exclude them from liquidity calculations. If you’re relying on retirement funds to qualify, confirm the issuer’s policy in advance.
Q: What happens if my net worth drops below $1 million after applying?
Most private fund managers conduct post-application verification before investing. If your net worth falls below the threshold, you may be asked to withdraw or forfeit your investment. Some firms also impose "look-back" periods (e.g., 12 months) to ensure stability.
Q: Are there alternatives to meeting the net worth test?
Yes. The SEC’s proposed rules (as of 2023) allow "natural persons" with specific financial knowledge or professional certifications (e.g., Series 7 license, CFA designation) to qualify as accredited investors, even if their net worth is below $1 million.
Q: How often should I update my net worth for accredited investor purposes?
At least annually, or whenever there’s a material change (e.g., sale of a business, significant market downturn, new debt). Some high-frequency traders or crypto investors update monthly to avoid eligibility gaps.
Q: What’s the most common mistake people make when calculating net worth for accredited investor status?
Overvaluing illiquid assets. Founders often include unvested stock options or pre-revenue business valuations at face value, but fund managers discount these by 50% or more. The second biggest mistake? Assuming verbal assurances suffice—always provide documentation.
