The Complete Overview of Commercial Loan Guarantor Net Worth Enhancement
The term commercial loan guarantor net worth enhancement refers to the deliberate optimization of a borrower’s or guarantor’s financial profile to improve loan eligibility, reduce interest costs, or secure more favorable terms. Unlike traditional collateral-based lending, this approach targets the personal or corporate guarantor’s balance sheet—whether through asset restructuring, tax-efficient vehicles, or synthetic financial instruments—to bridge the gap between a lender’s risk appetite and the borrower’s actual cash flow capacity. The practice has gained traction as banks and alternative lenders increasingly rely on guarantor-based lending models, particularly for middle-market deals where collateral values are insufficient to justify risk. What distinguishes this strategy from conventional wealth-building is its transactional intent. A family office might enhance net worth organically by investing in private equity or real estate, but a guarantor focused on commercial loan guarantor net worth enhancement does so with a specific lending outcome in mind. For example, a guarantor holding illiquid assets—such as a controlling stake in a tech startup—might deploy a standalone collateralized loan obligation (CLO) to convert a portion of that equity into bank-eligible liquidity. The CLO’s proceeds then bolster the guarantor’s net worth on paper, satisfying lender covenants without requiring the sale of the underlying asset. This precision is critical: lenders don’t just want assets; they want assets that can be quickly liquidated at fair value in a distress scenario. The rise of guarantor-focused financial engineering also reflects broader shifts in credit markets. Post-2008, banks tightened underwriting standards, forcing borrowers to demonstrate not just debt service coverage but reserve buffers—often tied to guarantor net worth. Today, even non-bank lenders, from private credit funds to peer-to-peer platforms, use guarantor net worth as a proxy for risk assessment. The result? A borrower’s ability to enhance their guarantor’s net worth can mean the difference between a 7% loan and one priced at 12%. For businesses in capital-intensive sectors—manufacturing, healthcare, or energy—the stakes are even higher, as project financing often hinges on guarantor-backed structures.Historical Background and Evolution
The concept of leveraging guarantor net worth to secure commercial loans traces back to the 1980s leveraged buyout boom, when private equity firms routinely used personal guarantees from sponsors to de-risk acquisitions. At the time, the focus was on personal net worth as a form of insurance—if the deal soured, the guarantor’s assets would cover shortfalls. However, the 1990s saw a pivot toward asset-based lending, where collateral replaced guarantor reliance. This shift persisted until the 2008 financial crisis, when collateral values collapsed and lenders once again turned to guarantors as a stabilizing force. The post-crisis era marked the professionalization of guarantor net worth enhancement. As banks imposed stricter loan-to-value (LTV) ratios, borrowers and their advisors began treating guarantor net worth as a negotiable commodity. Techniques like asset securitization, synthetic guarantees, and tax-efficient holding structures emerged to artificially inflate net worth metrics without triggering regulatory red flags. By the 2010s, alternative lenders—including direct lending funds and fintech platforms—further institutionalized the practice by offering loans structured around guarantor creditworthiness rather than traditional collateral. Today, commercial loan guarantor net worth enhancement is less about hiding risk and more about optimizing it within lender parameters.Core Mechanisms: How It Works
At its core, commercial loan guarantor net worth enhancement involves three primary levers: asset reclassification, synthetic liquidity creation, and tax-efficient structuring. The first lever—asset reclassification—focuses on recategorizing assets to meet lender definitions of "net worth." For instance, a guarantor holding non-marketable securities (e.g., restricted stock in a private company) might transfer them into a regulated investment vehicle that qualifies as liquid under bank guidelines. This doesn’t increase the asset’s true value but makes it bankable for lending purposes. The second mechanism, synthetic liquidity creation, is where financial engineering plays a larger role. A guarantor might use derivatives, forward sales agreements, or collateralized borrowing to generate cash flow that appears as net worth on a balance sheet. For example, a guarantor with $10 million in illiquid real estate could enter into a total return swap with a hedge fund, converting a portion of that equity into a synthetic liquid asset. The swap’s notional value then appears as part of the guarantor’s net worth, satisfying lender covenants without requiring an actual sale. The key risk here is mark-to-market volatility—if the swap’s value declines, the guarantor’s net worth could plummet overnight. Tax-efficient structuring is the third pillar. Guarantors often deploy offshore holding companies, grantor retained annuity trusts (GRATs), or charitable remainder trusts to defer or eliminate capital gains while preserving asset values. A common tactic involves transferring appreciated assets into a GRAT, which removes them from the guarantor’s taxable estate while maintaining their market value for net worth calculations. Lenders view this as a permanent enhancement because the asset remains under the guarantor’s control but is now shielded from tax drag. However, this approach requires careful compliance with Subchapter S trust rules and anti-abuse provisions in tax law.Key Benefits and Crucial Impact
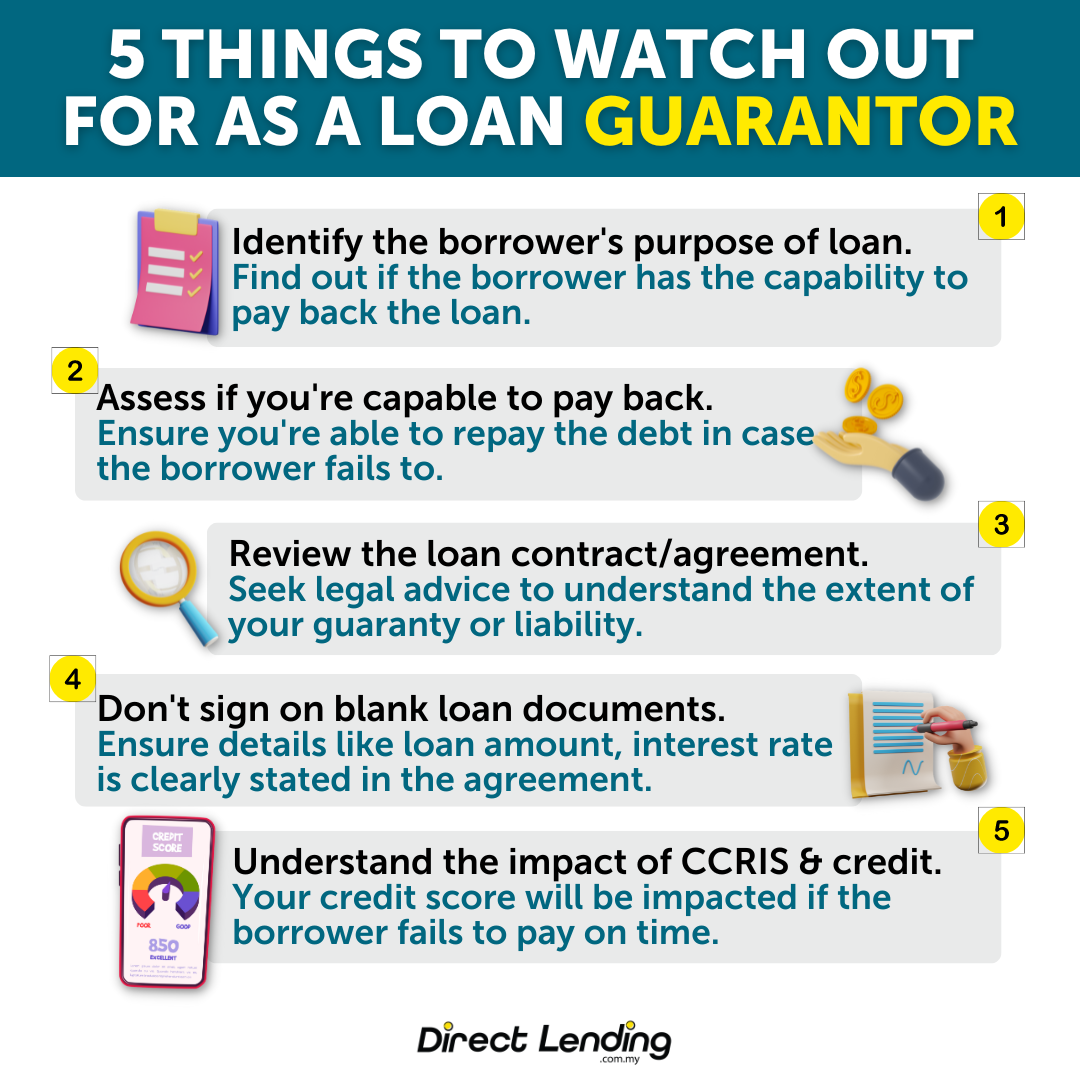
The primary advantage of commercial loan guarantor net worth enhancement is its ability to unlock credit when traditional collateral falls short. For businesses in sectors like healthcare, hospitality, or renewable energy, where asset values are volatile, this strategy provides a lifeline. A guarantor with a net worth of $50 million but only $10 million in liquid assets might still secure a $20 million loan if they can restructure their balance sheet to meet a lender’s net worth-to-loan ratio (often 120%–150%). The result? Lower interest rates, longer repayment terms, and access to capital that would otherwise be denied. Beyond immediate lending benefits, enhanced guarantor net worth can improve a borrower’s negotiating position. Lenders competing for deals will often adjust terms—such as waiving fees or extending covenants—in exchange for a stronger guarantor profile. This dynamic is particularly pronounced in private credit markets, where funds use guarantor net worth as a differentiator in a crowded deal space. For high-net-worth individuals, the strategy also offers estate planning synergies: by optimizing net worth for lending purposes, they simultaneously reduce taxable estates and improve inheritance structures. > "The most effective guarantors aren’t just wealthy—they’re architects of their own creditworthiness. They don’t wait for markets to reward them; they engineer the metrics that matter to lenders." > — Mark R. Wilson, Managing Director at CrossBorder CapitalMajor Advantages
- Access to capital when collateral values are insufficient or illiquid.
- Reduction in all-in borrowing costs by improving loan-to-value ratios.
- Flexibility to retain control of core assets while meeting lender covenants.
- Tax optimization that preserves asset values for both lending and succession planning.
- Enhanced negotiating leverage with lenders, leading to better terms on interest, fees, and covenants.
Comparative Analysis
| Traditional Collateral-Based Lending | Guarantor Net Worth Enhancement |
|---|---|
| Relies on hard assets (real estate, equipment) as primary security. | Uses guarantor balance sheet strength to supplement or replace collateral. |
| Loan terms tied to asset depreciation and market cycles. | Terms depend on guarantor liquidity and ability to restructure assets. |
| Lower risk for lenders but higher barriers for borrowers with weak collateral. | Higher risk for lenders (if guarantor net worth is synthetic) but broader access for borrowers with strong personal finances. |
Future Trends and Innovations
The next frontier in commercial loan guarantor net worth enhancement lies in AI-driven asset valuation and blockchain-based liquidity tracking. Lenders are increasingly using machine learning models to assess not just the static value of guarantor assets but their real-time liquidity potential. For example, a guarantor holding cryptocurrency might see their net worth fluctuate hourly—but an AI system could dynamically adjust loan covenants based on 24-hour trading volumes. This real-time recalibration could make guarantor net worth a more dynamic underwriting tool, reducing the need for manual enhancements. Another emerging trend is the tokenization of guarantor assets. By converting illiquid assets—such as private equity stakes or real estate—into security tokens, guarantors can create fungible, tradable instruments that appear as liquid net worth on balance sheets. Platforms like Securitize and Polymath are already enabling this, allowing guarantors to instantly enhance their net worth without selling underlying assets. The catch? Regulatory clarity around tokenized collateral remains a hurdle, particularly in jurisdictions like the U.S., where the SEC continues to scrutinize digital asset securities.
Conclusion
Commercial loan guarantor net worth enhancement is no longer a niche financial tactic—it’s a core component of modern lending strategy. As credit markets tighten and collateral values stagnate, the ability to restructure, reclassify, and optimize a guarantor’s balance sheet will determine who gets funded and on what terms. The most sophisticated borrowers and lenders are moving beyond static net worth metrics toward dynamic, real-time financial engineering, where assets aren’t just held but actively managed for lending purposes. For businesses and high-net-worth individuals, the takeaway is clear: guarantor net worth is a negotiable asset. Whether through synthetic liquidity, tax-efficient structuring, or AI-augmented valuation, the tools to enhance it are more accessible than ever. The challenge? Balancing enhancement with authentic risk management. Lenders are getting smarter about detecting overstated net worth, and regulatory scrutiny on financial engineering is only increasing. The future belongs to those who can enhance net worth without sacrificing substance—a delicate but achievable equilibrium.Comprehensive FAQs
Q: How does asset reclassification differ from outright asset sales in net worth enhancement?
A: Asset reclassification involves recategorizing existing assets (e.g., moving restricted stock into a liquid vehicle) to meet lender definitions of net worth without selling them. Outright sales generate cash but trigger taxable events and reduce future borrowing capacity. Reclassification preserves asset control while temporarily boosting net worth metrics for lending purposes.
Q: Are synthetic liquidity tools like swaps or forward contracts risky for guarantors?
A: Yes. While these tools can temporarily enhance net worth, they introduce market risk. If the underlying asset’s value declines or the synthetic instrument’s collateral requirements rise, the guarantor’s net worth could drop suddenly. Lenders may also impose haircuts or margin calls, forcing liquidations that undermine the enhancement strategy.
Q: Can tax-efficient structures like GRATs be used for commercial loan guarantees?
A: Yes, but with strict compliance requirements. GRATs and similar trusts remove assets from a guarantor’s taxable estate while keeping them on their balance sheet—useful for long-term net worth enhancement. However, lenders may scrutinize these structures under Subchapter S trust rules or bank secrecy laws, particularly in cross-border deals. Always consult a tax attorney before structuring.
Q: How do lenders verify enhanced guarantor net worth?
A: Lenders use third-party appraisals, audited financials, and due diligence on synthetic instruments. For illiquid assets, they may require forward-looking liquidity analyses or stress-test scenarios. Alternative lenders, especially in private credit, increasingly rely on continuous monitoring via blockchain or AI tools to detect discrepancies in reported net worth.
Q: What sectors benefit most from guarantor net worth enhancement?
A: Sectors with high asset volatility or illiquid collateral see the most benefit, including:
- Healthcare (clinics, medical practices with intangible assets).
- Hospitality (hotels with fluctuating occupancy rates).
- Renewable energy (projects with long payback periods).
- Private equity-backed roll-ups (where collateral is thin).
Q: Can a guarantor’s net worth enhancement backfire if markets decline?
A: Absolutely. If a guarantor’s enhanced net worth relies on overvalued assets, synthetic instruments, or aggressive tax structures, a market downturn can erode perceived liquidity overnight. Lenders may then accelerate loan repayments or demand additional collateral, forcing the guarantor into a liquidity crunch. The key is stress-testing enhancements under adverse scenarios before committing.
Q: Are there legal risks to structuring net worth for lending purposes?
A: Yes. Misrepresenting net worth can lead to fraud charges, while abusive tax structures may trigger IRS audits or penalties under anti-abuse rules (e.g., Section 482 for transfer pricing). Lenders also face regulatory exposure if they rely on overstated guarantor net worth, particularly under Dodd-Frank or Basel III requirements. Always work with advisors familiar with financial structuring law.
Q: How long does it typically take to enhance a guarantor’s net worth for a loan?
A: Timelines vary:
- Asset reclassification: 2–4 weeks (if documents are prepped).
- Synthetic liquidity tools: 1–3 months (due to regulatory approvals).
- Tax-efficient trusts: 3–6 months (settlement periods apply).
