The Complete Overview of Blockbuster’s Financial Dominance in 2000
Blockbuster’s financial story in 2000 is a study in retail empire-building—a moment when a company’s market power seemed untouchable, even as the foundations of its business were eroding. The chain’s reported net worth that year was a testament to its scale: assets exceeding $6 billion, liabilities that, while substantial, were manageable given its revenue streams. Its balance sheet reflected a company that had mastered the art of franchise economics, with individual store operators footing much of the expansion cost while Blockbuster reaped the benefits. Yet for all its success, the company’s financial health was a house of cards—dependent on a single product category (video rentals) and a consumer base that took its dominance for granted. The year also saw Blockbuster at the center of a media arms race. Its partnership with Hollywood studios ensured it had exclusive access to new releases, a strategy that locked in customers and deterred competition. Studios like Disney and Warner Bros. relied on Blockbuster to drive box office revenue through home entertainment sales. But this symbiotic relationship masked a growing tension: as DVDs replaced VHS, Blockbuster’s inventory costs soared, and its late fee revenue—once a cash cow—became a contentious issue in Washington, where lawmakers began scrutinizing predatory pricing. The company’s market capitalization peaked in 1999 at over $10 billion, but by 2000, it had begun a slow decline, a harbinger of the challenges ahead.Historical Background and Evolution
Blockbuster’s origins trace back to a single store in Dallas in 1985, but its transformation into a national phenomenon began in 1987 with its first franchise locations. The company’s strategic acquisitions—such as the 1994 purchase of Video Rentals Inc.—accelerated its growth, turning it into the largest video rental chain in the world by the mid-1990s. Its expansion into Canada and Europe in the late 1990s further cemented its global reach, though these markets proved less lucrative than its U.S. core. By 2000, Blockbuster operated under a dual-revenue model: franchise fees from store owners and corporate profits from inventory sales, late fees, and licensing deals. The shift from VHS to DVD in the late 1990s was a double-edged sword for Blockbuster’s net worth in 2000. While DVDs offered higher profit margins per unit, they also required massive upfront investments in new inventory and store upgrades. The company’s capital expenditures ballooned as it retrofitted locations to accommodate the larger, more expensive discs. Meanwhile, its customer acquisition costs rose as competitors like Hollywood Video and local mom-and-pop shops fought for market share. The year 2000 was thus a pivot point: Blockbuster was still the 800-pound gorilla of video rentals, but the gorilla was beginning to feel the ground shift beneath its feet.Core Mechanisms: How It Works
Blockbuster’s business model in 2000 was a high-volume, low-margin operation optimized for scale. The company’s franchise system allowed it to expand rapidly with minimal corporate overhead—store owners handled day-to-day operations while Blockbuster provided branding, inventory, and marketing support. This structure kept operating costs low, but it also created operational silos that hindered agility. For example, while corporate could push new DVD titles to stores, franchisees often struggled with inventory turnover, leading to overstocked shelves and wasted capital. The company’s revenue streams were equally telling. Late fees alone accounted for roughly 20% of its annual profits, a figure that would later become a PR liability. Its licensing agreements with studios ensured it had first dibs on new releases, but these deals also tied its hands—Blockbuster couldn’t easily pivot to alternative entertainment formats (like video games or music rentals) without renegotiating contracts. The model worked as long as consumers kept renting physical media, but it offered no built-in resilience against technological disruption. By 2000, Blockbuster’s financial dependency on late fees and new-release DVDs was becoming a liability, not an asset.Key Benefits and Crucial Impact
Blockbuster’s dominance in 2000 wasn’t just financial—it was culturally transformative. The chain didn’t just sell movies; it created a weekend ritual for millions of Americans. Its stores became social hubs, where families debated film choices, teenagers discovered indie cinema, and late-night rentals fueled the economy of small towns and cities alike. The company’s brand equity was so strong that it could charge premium prices for new releases, knowing customers would pay for the convenience of instant access. This consumer lock-in was the envy of retailers across industries, and for a time, it made Blockbuster’s net worth in 2000 seem untouchable. Yet the company’s impact extended beyond entertainment. Blockbuster’s supply chain innovations—like its centralized distribution hubs—set new standards for retail logistics. Its data analytics (primitive by today’s standards) tracked customer rental habits, allowing it to tailor promotions and inventory decisions. The chain’s franchise model also inspired other businesses to adopt similar structures, proving that decentralized retail could scale globally. But for all its achievements, Blockbuster’s greatest legacy was its blind spots—particularly its failure to recognize the threat of digital distribution, which would render its physical assets obsolete within a decade."Blockbuster was the Walmart of movies—everyone went there, but no one thought about what came next." — Industry analyst, 2001 (cited in Fortune archives)
Major Advantages
- Unmatched market share: Over 6,000 stores in 10 countries, making it the default choice for video rentals.
- Studio partnerships: Exclusive deals with Hollywood ensured Blockbuster had first access to new releases, locking in customers.
- Franchise scalability: The model allowed rapid expansion with minimal corporate risk, though it diluted control over operations.
- Late fee revenue: A $1 billion annual stream from penalties provided a stable, if controversial, income source.
- Cultural dominance: Blockbuster wasn’t just a business—it was a social institution, shaping how generations consumed media.

Comparative Analysis
| Blockbuster (2000) | Key Competitors |
|---|---|
| Revenue: ~$5 billion annually | Hollywood Video: ~$1.5 billion; local rentals: fragmented but numerous |
| Net Worth: Estimated at $8–10 billion (assets minus liabilities) | Hollywood Video: ~$500 million; Netflix (pre-IPO): ~$50 million |
| Store Count: 6,000+ globally | Hollywood Video: ~1,000; Netflix: 0 (mail-order only) |
| Profit Margins: ~5–7% (thin due to late fees and inventory costs) | Netflix: ~10% (higher due to lower overhead) |
| Biggest Threat: Rising DVD costs and digital disruption | Netflix: Physical media’s decline and broadband adoption |
Future Trends and Innovations
By 2000, the writing was on the wall for Blockbuster’s physical model, though few inside the company acknowledged it. The rise of DVD rental-by-mail services like Netflix—then a niche player—signaled a shift toward convenience over physical presence. Blockbuster’s digital lag became apparent when it failed to capitalize on early internet rental platforms, instead doubling down on store expansions. Meanwhile, broadband adoption was accelerating, making streaming a viable alternative. The company’s 2004 attempt to launch a streaming service came too late, and by then, its brand was already associated with obsolete technology. The irony of Blockbuster’s net worth in 2000 was that its greatest strength—its physical infrastructure—became its Achilles’ heel. While the company’s $8–10 billion valuation made it a retail giant, its inability to adapt to digital trends ensured that within a decade, it would file for bankruptcy. The lesson for other legacy businesses was clear: scale and dominance don’t guarantee survival in an era of rapid technological change. Blockbuster’s story remains a case study in how even the most entrenched industries can be upended by innovation—and how financial success in one era doesn’t translate to resilience in the next.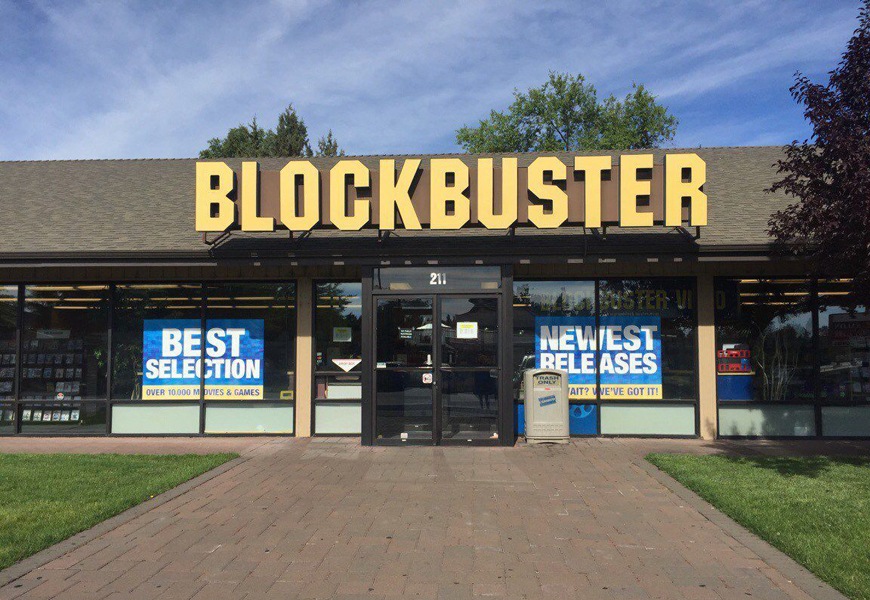
Conclusion
Blockbuster’s financial peak in 2000 was a fleeting moment, a snapshot of an era when physical retail still ruled supreme. The company’s net worth, its market share, and its cultural footprint made it seem invincible, yet its downfall was inevitable once the digital tide began to rise. Today, Blockbuster is remembered less for its financial might and more for its symbolic failure—a cautionary tale about the dangers of complacency in a changing world. Its story forces a reckoning with the fragility of even the most dominant businesses, especially those that mistake momentum for immortality. The legacy of Blockbuster’s net worth in 2000 is a reminder that wealth and influence are not the same as adaptability. The company’s rise was a masterclass in retail execution, but its fall was a masterclass in strategic blindness. As streaming services now dominate the entertainment landscape, Blockbuster’s tale serves as a mirror—reflecting not just the past, but the vulnerabilities of any business that fails to evolve with its customers.Comprehensive FAQs
Q: How did Blockbuster’s late fees contribute to its net worth in 2000?
Late fees were a critical revenue driver, accounting for roughly $1 billion annually—about 20% of Blockbuster’s profits at the time. These fees subsidized the company’s thin margins on DVD rentals and helped offset high inventory costs. However, they also created customer resentment and later became a legal and PR liability as regulators and competitors challenged their fairness.
Q: Was Blockbuster profitable in 2000 despite its high debt?
Yes, but marginally. The company reported net profits in the range of $200–300 million in 2000, though its operating margins were compressed by expansion costs and inventory write-offs. Its debt—reportedly over $3 billion—was manageable as long as revenue grew, but the debt load made it vulnerable to economic downturns or shifts in consumer behavior, both of which materialized in the early 2000s.
Q: Did Blockbuster’s stock price reflect its true net worth in 2000?
No. Blockbuster’s stock had peaked in 1999 at over $60 per share (adjusted for splits), but by 2000, it had declined to $10–15, reflecting market skepticism about its long-term viability. Analysts at the time noted that while the company’s revenue was strong, its profitability was dependent on late fees and new-release DVD sales—both of which were unsustainable trends. The stock’s decline foreshadowed the company’s eventual unraveling.
Q: How did Blockbuster’s international expansion affect its net worth?
Its global footprint—particularly in Canada and Europe—diluted profitability. While international stores contributed to revenue, they often underperformed compared to U.S. locations due to lower consumer spending on entertainment and higher operational costs. By 2000, Blockbuster had begun scaling back international operations, recognizing that its core profitability depended on its U.S. dominance. This retrenchment was a tacit admission that its global ambitions had outpaced its financial returns.
Q: What was the biggest financial mistake Blockbuster made in 2000?
The company’s failure to invest in digital alternatives was its fatal oversight. While it acquired streaming startups (like Movielink in 2003), its 2000 strategy focused solely on physical stores and late fees. Competitors like Netflix were already building subscription-based models that eliminated late fees and reduced overhead. Blockbuster’s $50 million acquisition of Movielink in 2003 came too late—by then, its brand was already associated with outdated technology, and its financial flexibility had eroded.
