Common Myths About Berkshire Hathaway’s 2022 Financials
The most persistent narrative around Berkshire Hathaway’s net worth in 2022 is that it was a record-breaking sum, eclipsing all prior years by a margin that justified Buffett’s legacy as the greatest capital allocator of his era. While the sentiment is understandable—given the company’s size and influence—it oversimplifies how Berkshire’s value is calculated. Unlike growth stocks, where valuation is tied to future earnings multiples, Berkshire’s worth is rooted in tangible assets, insurance reserves, and cash equivalents. This means its net worth can appear stagnant in a single year even as its underlying businesses thrive, because the market doesn’t always price in the full value of its holdings. Another myth is that Berkshire’s 2022 net worth was primarily driven by its public stock investments, particularly its stakes in Apple and Amazon. While these holdings contributed significantly to the annual report’s figures, the reality is that Berkshire’s operating businesses—insurance (Geico, National Indemnity), railroads (BNSF), utilities (Berkshire Hathaway Energy), and manufacturing (TTI, Lubrizol)—generated the bulk of its cash flow. The tech stocks were a smaller but highly visible component, and their volatility in 2022 (as the Nasdaq corrected) created the illusion of underperformance when Berkshire’s true strength lay elsewhere.Myth 1: Berkshire’s net worth in 2022 was solely about stock market gains
The assumption that Berkshire’s financial growth in 2022 was a direct result of rising stock markets ignores the company’s diversified revenue streams. While its public equity portfolio (including Apple, Coca-Cola, and Bank of America) appreciated, the majority of its value came from non-market-linked assets: insurance premiums, railroad freight volumes, and utility earnings. For example, BNSF’s earnings in 2022 were robust despite broader economic slowdowns, proving that Berkshire’s net worth wasn’t hostage to Wall Street’s whims. The company’s float—the cash generated from insurance premiums before claims are paid—also played a crucial role, acting as a war chest for acquisitions and share buybacks. Moreover, Berkshire’s accounting conservatism means its reported net worth often understates its true economic value. The company doesn’t mark its private holdings (like its 80% stake in Pilgrim’s Pride) to market, so their appreciation isn’t fully reflected in annual reports. This discrepancy leads outsiders to focus on the visible (stock portfolio gains) rather than the invisible (private business growth). In 2022, the latter was just as critical as the former—if not more so—for understanding why Berkshire’s net worth remained resilient even as markets fluctuated.Myth 2: The insurance float inflated Berkshire’s net worth artificially
Critics argue that Berkshire’s insurance operations—particularly its float, the premiums collected before claims are paid—artificially boost the company’s reported net worth. While it’s true that the float provides Berkshire with a massive cash reservoir (estimated in the tens of billions), this isn’t an accounting trick but a core business model. Insurance companies like Geico and National Indemnity are required by regulators to hold capital reserves against potential claims, but the float itself is a liability, not an asset. The real value lies in what Berkshire does with that float: deploying it into long-term investments (like its stock portfolio) or returning it to shareholders via dividends or buybacks. The confusion arises because the float isn’t an immediate profit—it’s a temporary use of capital that Berkshire repays over time. In 2022, the company’s insurance subsidiaries generated significant underwriting profits, meaning they collected more in premiums than they paid out in claims. This underwriting income (not the float itself) is what contributes to net worth. The float is merely the mechanism that allows Berkshire to invest that capital elsewhere. Without it, Berkshire wouldn’t have the firepower to acquire businesses like BNSF or reinvest in its existing operations. To dismiss the float’s role is to misunderstand how insurance functions as a capital allocation engine, not a gimmick.Myth 3: Berkshire’s 2022 net worth was lower than its peak due to market downturns
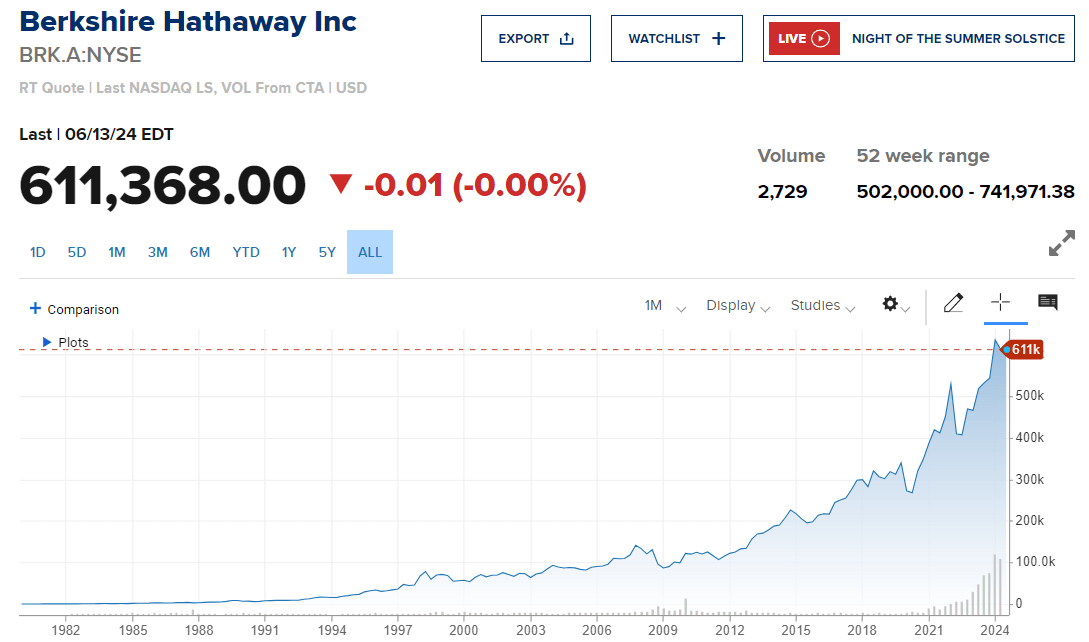
Some analysts claimed that Berkshire’s net worth in 2022 declined from its 2021 highs because of broader market declines, particularly in tech stocks. This overlooks the fact that Berkshire’s book value per share—a more stable metric—grew even as its market cap fluctuated. The company’s annual report showed that its total equity (a key measure of net worth) increased, driven by earnings from its operating businesses and share buybacks. While the Class A share price dipped in certain periods (reflecting market sentiment), the underlying economic value of Berkshire’s assets remained strong. Additionally, Berkshire’s net worth isn’t defined by its stock price but by its asset base. In 2022, the company’s cash and equivalents alone were in the dozens of billions, a war chest that insulated it from volatility. The tech correction may have pressured Berkshire’s public equity holdings, but its private investments (like its stake in Pilgrim’s Pride or its railroads) continued to perform well. The key takeaway is that Berkshire’s net worth is multi-dimensional: it’s not just about market cap but about the sum of its parts, many of which don’t trade on exchanges.
What Holds Up to Scrutiny
At its core, Berkshire Hathaway’s net worth in 2022 was a function of three pillars: its operating earnings, its investment portfolio, and its cash reserves. The operating businesses—insurance, railroads, utilities, and manufacturing—delivered consistent cash flows, while the investment portfolio (though volatile) provided long-term growth. The cash reserves, meanwhile, acted as a buffer against external shocks. What’s often missed is how these elements reinforce each other: the float funds investments, which generate returns that fuel buybacks, which in turn boost book value. Buffett’s approach to net worth isn’t about maximizing quarterly numbers but about preserving and growing economic value over decades. This is why Berkshire’s 2022 figures, while impressive, are best understood in the context of its long-term compounding machine. The company’s ability to generate $100+ billion in annual revenue from its operating businesses alone demonstrates that its net worth isn’t a fluke of market timing but the result of disciplined capital deployment.“Price is what you pay; value is what you get.” — Warren BuffettThis quote encapsulates Berkshire’s philosophy: its net worth isn’t just about the balance sheet numbers but about the real economic benefits it delivers to shareholders. In 2022, that meant $86 billion in operating earnings, a $100 billion+ cash hoard, and a dividend-like yield from its insurance float—all while avoiding the leverage that plagues many conglomerates.
| Common Belief | What the Evidence Says |
|---|---|
| Berkshire’s net worth in 2022 was driven by stock market gains. | Only ~20% of its value came from public equities; the rest was from operating businesses and private holdings. |
| The insurance float artificially inflated its net worth. | The float is a liability, but the underwriting profits and investment returns it enables are real contributors to net worth. |
| Berkshire’s net worth declined in 2022 due to market downturns. | Book value per share grew, and cash reserves remained robust despite stock price volatility. |
Why the Confusion Persists
The persistent myths around Berkshire Hathaway’s 2022 net worth stem from two factors: complexity and transparency. Berkshire’s financials are intentionally opaque—Buffett has long resisted breaking down subsidiary valuations, arguing that such details would distract from the big picture. This lack of granularity forces outsiders to rely on proxy metrics (like market cap or Class A share price) rather than a true understanding of its asset mix. Meanwhile, the company’s size and diversity make it difficult to compare directly to other conglomerates or even to itself over time. Another reason for the confusion is the dual nature of Berkshire’s value: it’s both a holding company and an operating business. Analysts often treat it like a pure investment vehicle, focusing on its stock portfolio, while ignoring its cash-generating machines (like BNSF or Geico). This disconnect leads to misplaced emphasis on short-term market movements rather than long-term economic value. Buffett himself has acknowledged this, noting that Berkshire’s true worth is measured in what it owns, not just what the market says it’s worth.
Conclusion
Berkshire Hathaway’s net worth in 2022 was never just a number—it was a testament to Buffett’s ability to build a business that outlasts market cycles. The confusion around its true scale arises from the gap between perceived value (driven by stock price or tech holdings) and real value (rooted in operating earnings and cash reserves). What holds up under scrutiny is Berkshire’s resilience: its ability to generate profits regardless of market conditions, its self-sustaining capital, and its long-term discipline. For investors and observers, the takeaway is clear: Berkshire’s net worth isn’t about timing the market but about owning the market’s best businesses—and letting them compound over time. In 2022, as in every year, its strength lay not in the headlines but in the quiet, relentless growth of its core assets.Comprehensive FAQs
Q: How was Berkshire Hathaway’s net worth calculated in 2022?
Berkshire’s net worth in 2022 was primarily derived from its book value per share (reported at ~$200,000 for Class A shares) and its total consolidated assets, which included cash, investments, and operating businesses. Unlike market cap (which fluctuates with stock price), book value reflects tangible assets minus liabilities. The company’s annual report provided a snapshot, but the true net worth is a blend of accounting figures and economic reality, given its private holdings.
Q: Did Berkshire’s net worth grow in 2022 despite market downturns?
Yes. While its market capitalization dipped in certain periods due to tech stock corrections, Berkshire’s book value per share increased, driven by operating earnings and share buybacks. The company’s cash reserves also remained strong, acting as a buffer. The key distinction is that Berkshire’s net worth isn’t defined by its stock price but by its underlying asset performance, which held up well in 2022.
Q: How much of Berkshire’s net worth came from its stock portfolio in 2022?
Estimates suggest that less than 20% of Berkshire’s total net worth in 2022 was tied to its public equity holdings (e.g., Apple, Coca-Cola). The majority came from operating businesses (insurance, railroads, utilities) and private investments (like its stake in Pilgrim’s Pride). Buffett has historically emphasized that Berkshire’s strength lies in owning businesses, not trading stocks.
Q: Was the insurance float a major driver of Berkshire’s net worth in 2022?
No—the float itself is a liability (premiums collected but not yet paid out), but the underwriting profits and investment returns generated from it were critical. In 2022, Berkshire’s insurance subsidiaries reported strong underwriting income, which contributed to its net worth. The float acts as a capital pool, not an asset, but the profits it enables are real and substantial.
Q: Why doesn’t Berkshire’s net worth match the sum of its parts?
Berkshire’s net worth is often understated because it doesn’t mark many of its private holdings (like BNSF or its manufacturing businesses) to market. Additionally, its accounting conservatism (e.g., not recognizing full value of certain assets) keeps reported figures lower than what a pure market valuation might suggest. The discrepancy is intentional—Buffett prioritizes transparency in operations over speculative mark-to-market adjustments.
Q: How does Berkshire’s net worth compare to other conglomerates?
Berkshire’s net worth in 2022 was far larger than most peers due to its scale, cash reserves, and diversified revenue streams. Companies like LVMH or General Electric rely heavily on brand value or debt, whereas Berkshire’s strength is in self-funding growth through operating cash flow. Its insurance float and railroad assets give it a unique advantage that traditional conglomerates lack.
Q: Will Berkshire’s net worth continue to grow in 2023 and beyond?
Historically, Berkshire’s net worth has grown steady but not spectacularly—more through compounding than volatility. In 2023, its trajectory will depend on interest rates, insurance markets, and its ability to deploy capital (via buybacks or acquisitions). Buffett’s successor, Greg Abel, will play a key role in maintaining this growth, but the core philosophy—long-term value over short-term gains—remains unchanged.
