
7 Things Worth Knowing About Berkshire Hathaway’s 2020 Financial Standing
The year 2020 forced investors to scrutinize Berkshire Hathaway’s financials with unusual intensity. While the conglomerate avoided the dramatic losses seen in some of its public equity holdings, the pandemic’s economic fallout tested Buffett’s long-standing strategies. Below are seven critical insights into how the company’s net worth held up—and what it says about its future.1. A Book Value Per Share That Defied Market Chaos
Berkshire Hathaway’s book value per share in 2020 remained one of the most closely watched figures in finance. At year-end, it hovered around $45,000 per share—a figure that, while lower than the peak of $50,000+ in 2019, reflected the company’s ability to absorb volatility without panic selling. The decline wasn’t due to poor management but rather the $23 billion write-down on its massive stake in Wells Fargo, a reflection of the bank’s own struggles amid regulatory pressures. For Buffett, this was a reminder that even blue-chip holdings aren’t immune to external shocks—but the write-down also highlighted Berkshire’s transparency, a rarity in corporate disclosures. What set Berkshire apart was its $137 billion cash hoard at the start of 2020. While critics questioned the wisdom of holding so much liquidity, the pandemic proved Buffett’s cash-first mentality prescient. When markets crashed in March, Berkshire didn’t just sit idle; it deployed capital strategically, including a $10 billion investment in airlines (Delta, Southwest, American) and a $25 billion stake in Bank of America. These moves weren’t just about profit—they were about preserving the company’s ability to act when others couldn’t.2. The Insurance Float: Berkshire’s Silent Profit Engine
Berkshire Hathaway’s insurance subsidiaries—Geico, National Indemnity, and others—generate what Buffett calls the "float," premiums collected from policyholders before claims are paid. In 2020, this float became even more critical as Berkshire’s investment portfolio faced headwinds. The float allowed the company to invest $120 billion+ in equities and bonds without diluting shareholders, a strategy that paid off when interest rates plummeted. While the float’s exact value isn’t disclosed, industry estimates suggest it contributed $5 billion–$7 billion in net earnings for the year, offsetting losses in other areas. The pandemic also tested the float’s resilience. Catastrophic events—like the Texas freezes or California wildfires—led to higher claims, but Berkshire’s underwriting discipline limited the damage. Unlike peers that struggled with reserve adequacy, Berkshire’s long-term pricing models absorbed the shocks. This is why analysts often cite the float as Berkshire’s "secret weapon"—a recurring revenue stream that funds Buffett’s buying sprees without shareholder dilution.3. The Public Equity Portfolio: A Mixed Bag of Winners and Laggards
Buffett’s public stock holdings took a beating in 2020. Apple, Berkshire’s largest equity stake, saw its share price drop ~10% from its 2019 high, though it still accounted for ~40% of the portfolio. Coca-Cola, another cornerstone, underperformed as consumer spending shifted away from traditional beverages. Even stalwarts like American Express faced headwinds as travel and spending slowed. By year-end, Berkshire’s public equity portfolio was down ~15%, a rare underperformance in Buffett’s 56-year tenure. Yet the losses weren’t uniform. Berkshire’s $23 billion investment in Amazon (acquired in 1998) appreciated significantly as e-commerce surged. Similarly, its stake in Bank of America rebounded as the bank benefited from government-backed lending programs. The contrast between Buffett’s long-term holds (like Apple and Coca-Cola) and his pandemic opportunism (like airlines and banks) showcased his adaptive approach. The 2020 portfolio wasn’t just a snapshot of past bets—it was a real-time stress test of Berkshire’s ability to pivot.4. The Railroads: A Steady Beacon in Turbulent Times
Berkshire’s ownership of BNSF Railway and Burlington Northern Santa Fe (BNSF) proved to be one of its most stable assets in 2020. While freight volumes dipped due to supply chain disruptions, the railroads’ fixed-cost structures and essential nature (transporting goods like food and medical supplies) shielded them from the worst of the downturn. BNSF’s operating income declined by ~5%, but the company maintained strong free cash flow, reinforcing its role as a cash-generating machine for Berkshire. What made the railroads unique was their dividend-like returns. Unlike traditional dividends, BNSF’s earnings flowed back to Berkshire as retained cash, which Buffett could then reinvest. In 2020, this $3 billion+ in earnings provided a buffer against losses elsewhere. The railroads also benefited from the shift to domestic manufacturing as global supply chains fractured—a trend that could last beyond the pandemic. For Buffett, BNSF wasn’t just an asset; it was a hedge against geopolitical and economic uncertainty.5. The Energy Sector: A High-Risk, High-Reward Gamble
Berkshire’s energy holdings—particularly its $10 billion stake in Occidental Petroleum (Oxy)—became a focal point in 2020. The deal, announced in 2019, was Buffett’s first major foray into the oil sector, a departure from his usual consumer and financial services focus. When oil prices collapsed to $20 per barrel, Oxy’s debt-laden balance sheet came under scrutiny. Berkshire’s $3.5 billion investment in Oxy’s preferred stock was called into question, though Buffett defended it as a long-term bet on energy resilience. The Oxy deal also highlighted Berkshire’s willingness to take on risk in pursuit of scale. While the investment underperformed in 2020, Buffett framed it as a multi-decade play, not a quarterly trade. The energy sector’s volatility forced Berkshire to navigate ESG pressures—something Buffett has historically sidestepped. Whether this was a strategic misstep or a calculated gamble remains debated, but it marked a rare instance where Berkshire’s net worth in 2020 was tied to an industry outside its core competencies."We’re in the business of buying businesses, not predicting the future. But if you’re going to own something for 20 years, you’d better believe in it." — Warren Buffett, 2020 Shareholder Letter
6. Shareholder Equity and the Dilution Debate
One of the most contentious topics in 2020 was Berkshire’s shareholder equity growth. While the company’s $840 billion+ market cap made it one of the world’s largest public firms, its book value per share stagnated due to limited acquisitions and the Wells Fargo write-down. This led to criticism that Berkshire was hoarding cash at the expense of shareholder returns. Buffett countered that growth isn’t the goal—capital preservation is. The company’s $100 billion+ in retained earnings over the past decade meant it didn’t need to issue new shares, avoiding dilution. However, as younger investors grew accustomed to dividends and buybacks, Berkshire’s "no-distribution" policy became harder to justify. The 2020 performance raised questions: Was Berkshire’s net worth in 2020 a sign of strength (cash reserves) or stagnation (lack of deployment)?7. The Succession Question: Greg Abel’s Rising Profile
Behind the financials, 2020 also marked a quiet shift in Berkshire’s leadership. Vice Chairman Greg Abel took on more responsibility as Buffett, then 89, showed signs of slowing down. Abel’s oversight of Berkshire’s non-insurance operations (including railroads and utilities) became more prominent, with his $1.5 billion+ compensation (mostly in Berkshire stock) drawing attention. The succession dynamic added a layer of uncertainty to Berkshire’s net worth in 2020. Would Abel continue Buffett’s cash-heavy, buy-and-hold strategy, or would he embrace more active management? The answer could shape Berkshire’s future—especially if Buffett’s health or market conditions forced a faster transition. For now, the company’s stability relied on Buffett’s unshakable presence, but 2020 was the first year many investors openly discussed what comes next.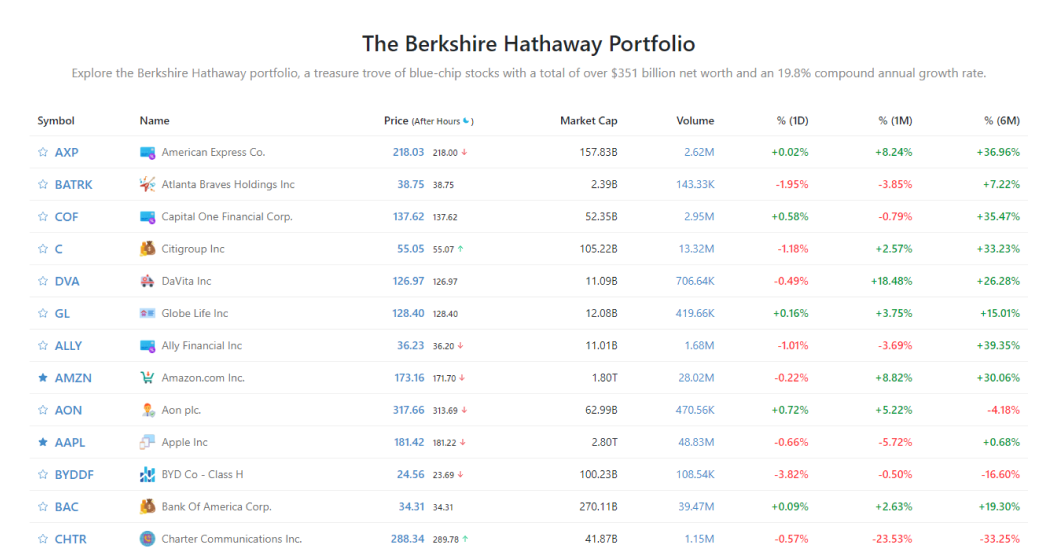
How These Facts Connect
Berkshire Hathaway’s 2020 net worth tells a story of two Buffetts: the conservative investor who hoarded cash and the opportunistic buyer who deployed it when markets faltered. The company’s ability to absorb losses in public equities while profiting from insurance float and railroads demonstrated why its diversified model remains robust. Yet the year also exposed fractures in the Buffett playbook—from the Oxy energy bet to the succession question—suggesting that Berkshire’s future may require adjustments. The most striking contrast was between stability and adaptation. Berkshire’s cash reserves and railroads provided a hedge against volatility, while its airline investments and Amazon stake showed Buffett’s willingness to embrace change. This duality is what made 2020 both a test and a transition year for the conglomerate. The question now isn’t just about Berkshire’s net worth in 2020, but how it will evolve under new leadership while staying true to its core principles.| Key Metric | 2019 Performance | 2020 Performance | Implications |
|---|---|---|---|
| Book Value Per Share | ~$50,000 | ~$45,000 (down ~10%) | Write-downs (Wells Fargo) and market losses, but no panic sales. |
| Cash Reserves | $110 billion | $137 billion (peaked at $147 billion in Q1) | Allowed strategic deployments (airlines, banks) during market downturns. |
| Public Equity Portfolio | Up ~20% (led by Apple) | Down ~15% (Apple, Coca-Cola lagged; Amazon, banks gained) | Mixed results—long-term holds underperformed, but opportunistic buys paid off. |
| Insurance Float | ~$60 billion in premiums | ~$55 billion (higher claims but disciplined underwriting) | Funded investments without shareholder dilution; acted as a profit buffer. |

Conclusion
Berkshire Hathaway’s net worth in 2020 was a masterclass in crisis management. While the pandemic disrupted markets, the conglomerate’s cash, float, and diversified assets shielded it from the worst outcomes. Buffett’s ability to buy when others were selling—whether in airlines or banks—reinforced his reputation as a contrarian investor. Yet the year also served as a reality check: even Berkshire isn’t immune to sector-specific risks (like energy) or generational shifts (like succession). The bigger lesson is that Berkshire’s strength lies in its flexibility. The company’s net worth isn’t just a reflection of past successes but a blueprint for navigating uncertainty. As Buffett steps back and Abel takes the helm, the challenge will be balancing tradition with innovation—without losing the discipline that made Berkshire Hathaway a fortress in 2020.Comprehensive FAQs
Q: How did Berkshire Hathaway’s stock price change in 2020?
A: Berkshire’s Class A shares (BRK.A) ended 2020 around $340,000, down roughly ~10% from their 2019 peak of $380,000+. The decline mirrored broader market losses but was less severe than the S&P 500’s ~7% drop. The stock’s resilience was due to its cash position and insurance float, which acted as cushions during volatility.
Q: Did Berkshire Hathaway buy back shares in 2020?
A: No. Berkshire has not repurchased shares since 1912, a policy Buffett attributes to avoiding shareholder dilution and ensuring capital is available for acquisitions. In 2020, the company’s $100 billion+ in retained earnings made buybacks unnecessary, though some analysts argue it could signal confidence if adopted.
Q: How much did Berkshire’s investment in airlines affect its net worth?
A: Berkshire’s $10 billion airline investments (Delta, Southwest, American) were a high-profile but small part of its overall portfolio. While the stakes appreciated as travel rebounded in late 2020, their impact on net worth was overshadowed by larger holdings like Apple and BNSF. The move was more about strategic positioning than financial materiality.
Q: Was Berkshire Hathaway’s 2020 performance worse than its peers?
A: Compared to diversified conglomerates like General Electric or 3M, Berkshire’s 2020 was stronger due to its cash reserves and insurance operations. However, against tech-focused firms (e.g., Microsoft, Amazon), Berkshire lagged as its traditional holdings underperformed. The key difference: Berkshire’s defensive posture preserved capital at the cost of growth.
Q: How does Berkshire’s net worth compare to other Fortune 500 companies?
A: In 2020, Berkshire’s market cap of ~$840 billion placed it among the top 10 largest U.S. public companies, alongside Apple, Microsoft, and Amazon. Its book value (~$500 billion) was larger than many peers’, reflecting its asset-heavy model. Unlike tech firms driven by intangible assets, Berkshire’s worth is tied to tangible holdings (railroads, insurance, cash), making it less volatile.
Q: What was the biggest risk to Berkshire’s net worth in 2020?
A: The biggest risk was Buffett’s health and the succession to Greg Abel. While financial risks (like Oxy or Wells Fargo) were manageable, the leadership transition posed an existential question: Would Berkshire’s net worth growth continue under a new CEO? The answer hinged on Abel’s ability to maintain Buffett’s investment discipline while adapting to a changing world.
Q: Did Berkshire Hathaway pay any dividends in 2020?
A: No. Berkshire has never paid a dividend, a policy Buffett justifies by reinvesting profits into acquisitions and shareholder value. In 2020, the company’s $6.1 billion in net earnings were retained, reinforcing its cash-first strategy. Some shareholders advocate for dividends, but Buffett has repeatedly stated that returning capital would reduce Berkshire’s financial flexibility.
Q: How did Berkshire’s energy investments (like Oxy) perform in 2020?
A: Berkshire’s Occidental Petroleum stake was its biggest underperformer in 2020. When oil prices collapsed, Oxy’s debt burden and dividend obligations became liabilities. While Buffett defended the investment as a long-term bet, it dragged down Berkshire’s energy-related earnings. The deal remains controversial, with critics arguing it was a distraction from Berkshire’s core competencies.
Q: What was Berkshire’s biggest acquisition in 2020?
A: Berkshire didn’t make any major acquisitions in 2020 beyond its airline investments and existing stakes. The year was instead about capital deployment—using cash to buy undervalued assets (like airline stocks) rather than acquiring entire companies. Buffett’s approach shifted from buying businesses to buying opportunities, a subtle but important change.
Q: How does Berkshire’s net worth growth compare to its historical average?
A: Historically, Berkshire’s book value per share has grown at ~20% annually since Buffett took over in 1965. In 2020, the ~10% decline was an outlier but not unprecedented—similar drops occurred in 2008 (financial crisis) and 2001 (dot-com bust). The key difference in 2020 was Berkshire’s speed of recovery: by mid-2021, its book value rebounded as markets stabilized, proving its long-term resilience.
