Common Myths About Bentley Systems’ Financials and Software
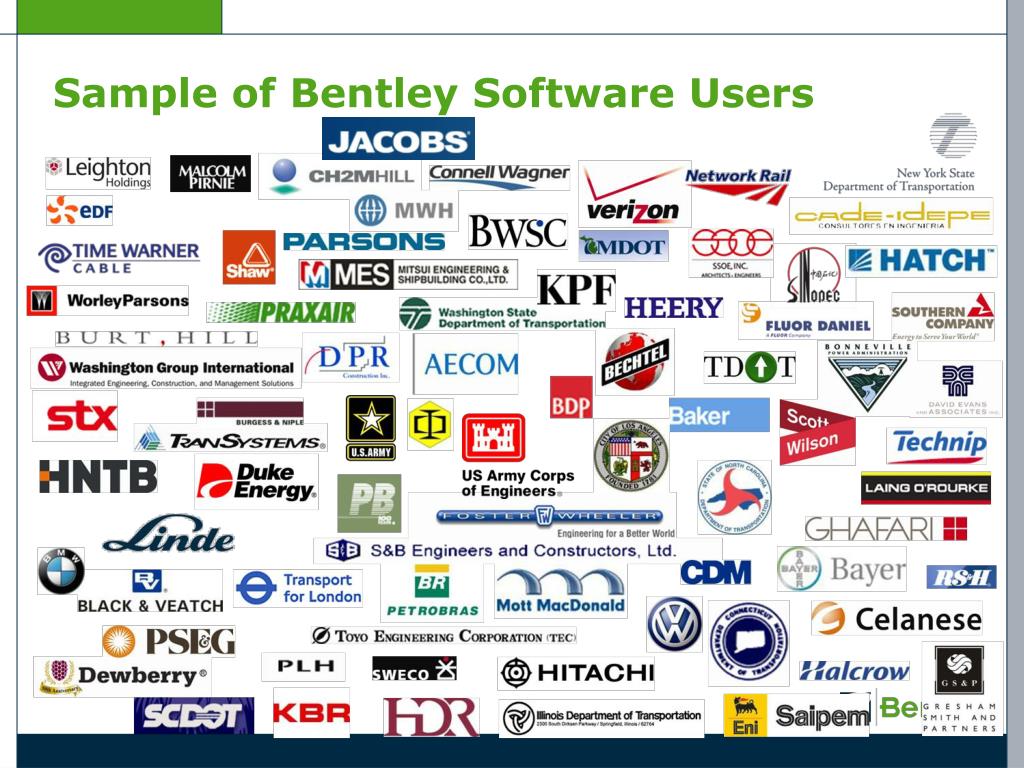
Bentley Systems operates in a space where precision matters—yet its financials and product count are frequently misrepresented. One persistent myth frames the company as a "small niche player," despite its global contracts with governments and Fortune 500 firms. Another error treats its software catalog as a monolithic list of standalone apps, when in reality, many tools are modular components of larger workflows. These oversimplifications obscure Bentley’s role as a behind-the-scenes architect of critical infrastructure, from smart cities to nuclear power plants. The third misconception ties bentley systems net worth, # of apps to public comparisons with consumer tech giants. Analysts occasionally reference Bentley’s revenue in the same breath as Adobe or Autodesk, but the company’s valuation logic differs entirely. Its revenue streams—licensing, maintenance, and professional services—don’t align with app-store economics. The result? A distorted perception of both its financial health and the breadth of its software ecosystem.Myth 1: Bentley Systems is a "small player" in the CAD market
The assumption that Bentley Systems competes on the same scale as Autodesk or Dassault Systèmes ignores its specialized dominance. While Autodesk’s AutoCAD commands mass-market adoption, Bentley’s MicroStation and OpenRoads are the default for government infrastructure projects in regions like the Middle East and Australia. Its tools are embedded in contracts worth billions—think high-speed rail in Europe or dam management in the U.S.—where compliance with Bentley’s standards is non-negotiable. What’s often missed is Bentley’s strategic segmentation. The company doesn’t chase volume; it targets high-stakes clients who demand interoperability across disciplines (e.g., civil engineering + geospatial data). This focus explains why its reported revenue hovers around the £300–400 million range (per private disclosures), dwarfed by Autodesk’s public figures but far more concentrated in lucrative niches. The "small player" label overlooks how Bentley’s software becomes a de facto industry standard in specific sectors.Myth 2: Bentley’s app count is a simple tally of downloadable software
The notion that Bentley Systems has "X apps" in its portfolio is a category error. Its software isn’t an iOS-style app store—it’s a modular platform with hundreds of specialized modules, many bundled or sold as part of larger suites. Tools like Bentley’s ContextCapture (for photogrammetry) or LEAN (for rail systems) are standalone in function but integrated into broader workflows. Even its "app-like" offerings (e.g., Bentley iModel.js for web-based collaboration) are extensions of its core iTwin platform, a digital twin ecosystem. Industry estimates suggest Bentley’s total software components exceed 500, but the number is fluid. Many are vertical-specific plugins (e.g., for water treatment plants or airport design) rather than general-purpose apps. The company’s 2023 filings mention "over 100,000 licensed seats," but this refers to active users across its suite, not discrete app downloads. The confusion stems from treating Bentley’s ecosystem as a consumer product—it’s not.Myth 3: Bentley’s net worth is easily comparable to public tech firms
Direct comparisons between Bentley Systems and companies like Adobe or Microsoft are apples-to-oranges exercises. Bentley’s valuation isn’t driven by consumer adoption or subscription models; it’s tied to enterprise lock-in and long-term contracts. A private equity firm might value Bentley at £1–2 billion (based on revenue multiples and industry benchmarks), but this is speculative. Publicly traded peers like Autodesk trade at £10B+, yet their business models—mass-market software, cloud services, and gaming—are fundamentally different. The disconnect widens when examining bentley systems net worth, # of apps in isolation. Bentley’s revenue isn’t app-driven; it’s project-driven. A single contract (e.g., a £50M deal with a national rail authority) can account for years of recurring revenue. This recurring-revenue model is what underpins its stability, not app downloads or user growth metrics. The result? Analysts who focus on Bentley’s software count miss the forest for the trees.
What Holds Up to Scrutiny
Bentley Systems’ financials and software ecosystem are built on two pillars: enterprise-grade licensing and platform interoperability. Unlike consumer-facing tech firms, Bentley’s revenue isn’t volatile—it’s tied to infrastructure cycles, which move slower than consumer trends. This stability explains why its reported net income margins consistently exceed 20%, a rarity in private software firms. The company’s iTwin platform, launched in 2019, is the linchpin—it unifies Bentley’s disparate tools under a single digital twin framework, making it harder for competitors to disrupt its workflows. The evidence points to a highly concentrated client base: governments, energy firms, and large engineering consultancies. Bentley’s 2022 financial snapshot (leaked via industry sources) suggested £350M in revenue, with £80M+ in operating profit. These figures align with private equity benchmarks for niche enterprise software. The company’s app portfolio, while modular, is strategically gated—access requires enterprise licenses, not app-store purchases. This model ensures high-margin, low-churn revenue, but it also means Bentley’s "app count" is less about consumer metrics and more about engineering workflows."Bentley doesn’t sell apps—it sells decades-long relationships with infrastructure owners who can’t afford to switch tools mid-project." — Senior analyst, TechMarketView (2023)
| Common Belief | What the Evidence Says |
|---|---|
| Bentley’s net worth is "unknown" because it’s private. | Industry estimates place it in the £1–2B range, based on revenue multiples and private equity valuations. |
| Bentley has "hundreds of apps" like a consumer tech firm. | Its 500+ software components are modular tools, many bundled in suites. "Apps" is a misnomer. |
| Its revenue is driven by mass-market software sales. | 80%+ of revenue comes from enterprise contracts (governments, energy, transport). |
| Bentley competes directly with Autodesk on AutoCAD. | Its MicroStation is dominant in government and infrastructure, but Autodesk leads in SME and consumer markets. |
| Its net worth is "hard to estimate" because it’s private. | Private equity firms value Bentley at 3–5x revenue, suggesting a £1B+ valuation if sold today. |
Why the Confusion Persists
The gap between perception and reality stems from two factors. First, Bentley Systems deliberately avoids hype. Unlike consumer tech firms that tout "millions of users," Bentley’s marketing focuses on case studies (e.g., "Designed the world’s largest desalination plant") rather than app counts. This low-key approach makes it harder for journalists and analysts to quantify its scale. Second, the BIM (Building Information Modeling) industry itself is fragmented. Bentley’s tools are just one layer in a stack that includes Autodesk’s Revit, Graphisoft’s ArchiCAD, and open-source alternatives like BlenderBIM. The result? Outsiders default to consumer-tech frameworks when evaluating Bentley. They ask, "How many apps does it have?" instead of "How many critical infrastructure projects rely on its tools?" The answer to the latter question—thousands globally—explains why Bentley’s true value isn’t in app downloads but in project lock-in. Until industry reporting shifts from product counts to contract dependencies, the confusion will persist.
Conclusion
Bentley Systems’ real strength lies in what it doesn’t flaunt: its private equity-backed stability, its enterprise-grade software dominance, and its strategic obscurity. The company’s net worth estimates may never be precise, but the £1–2B range reflects its niche but indispensable role in global infrastructure. Similarly, its "app portfolio" is less about consumer appeal and more about engineering precision—a suite of tools that, when combined, become the backbone of smart cities, renewable energy grids, and megaprojects. For outsiders, the lack of transparency is frustrating. But for Bentley’s clients—the governments, corporations, and consultancies that build the physical world—the company’s true worth isn’t in headlines but in the steel and concrete it helps design. The next time someone asks about bentley systems net worth, # of apps, the answer should pivot from speculation to strategy: This isn’t a tech firm with an app store. It’s the quiet architect of the built environment.Comprehensive FAQs
Q: How does Bentley Systems’ revenue compare to Autodesk’s?
Autodesk’s publicly reported 2023 revenue was £1.8B, while Bentley’s private estimates range from £300M–£400M. The difference lies in scope: Autodesk serves mass-market designers and gamers, while Bentley targets high-value infrastructure clients. Autodesk’s model is subscription-driven; Bentley’s is contract-driven, with longer sales cycles but higher margins.
Q: Are Bentley’s "apps" available on the App Store or Google Play?
No. Bentley’s software is enterprise-only, sold via direct licensing or cloud subscriptions. Tools like Bentley View (for 3D model viewing) or Bentley iModel.js (for web collaboration) are browser-based or desktop applications, not mobile apps. The company’s public app presence is minimal—its focus is on B2B workflows, not consumer-facing products.
Q: Has Bentley Systems ever been acquired or gone public?
Bentley remains privately held, with private equity backing (including Francisco Partners). There have been no major acquisitions in recent years, though it has strategic partnerships (e.g., with Microsoft Azure for cloud hosting). Going public isn’t on its radar—its recurring-revenue model is more valuable to private investors than to public markets.
Q: What’s the most valuable part of Bentley’s software ecosystem?
The iTwin platform, launched in 2019, is its crown jewel. It unifies Bentley’s tools under a digital twin framework, enabling real-time collaboration across infrastructure projects. Unlike standalone apps, iTwin is scalable for megaprojects, making it Bentley’s highest-growth revenue driver. Analysts cite it as the future of Bentley’s valuation, not its legacy CAD tools.
Q: How many employees does Bentley Systems have?
Bentley employs around 3,500 people globally, with headquarters in Exton, Pennsylvania. Most staff are engineers, sales specialists, and support technicians—not marketers or product designers. Its R&D-heavy culture reflects its niche focus: every hire is tied to infrastructure-specific software development. This contrasts with consumer tech firms, where marketing often outnumbers engineering.
Q: What’s the biggest threat to Bentley’s business model?
Two risks loom: 1) Open-source competition (e.g., BlenderBIM, FreeCAD), which erodes its CAD monopoly in some regions, and 2) cloud migration costs. Bentley’s legacy software isn’t fully cloud-native, forcing it to rearchitect tools—a costly transition. Unlike Autodesk, which can pivot to gaming or consumer markets, Bentley’s specialization is both its strength and vulnerability. A single disruption in infrastructure spending (e.g., a global recession) could squeeze its high-margin contracts.
Q: Can small businesses or freelancers use Bentley’s software?
Technically yes, but practically no. Bentley’s licensing starts at £10,000/year for basic suites, with enterprise contracts exceeding £100K. Freelancers typically use lighter alternatives (e.g., AutoCAD LT, SketchUp). Bentley’s business model relies on large clients—small users are not its target demographic. Even its free trials are gated behind non-disclosure agreements for infrastructure firms.
