
Breaking Down the Numbers
Wealth isn’t distributed like income. While income reflects annual earnings, average net worth by percentage of population accounts for assets (homes, investments, businesses) minus liabilities (debt, mortgages). This makes the divide sharper. The Federal Reserve’s Survey of Consumer Finances, the gold standard for U.S. data, shows that in 2022, the top 10% of households held roughly 70% of all net worth, while the bottom 50% held just 2.6%. That’s not a typo—less than 3% of the nation’s wealth sits with half the people. The net worth distribution by population percentile isn’t linear. It’s exponential. The jump from the 90th to the 99th percentile is staggering. A household in the 90th percentile might have a net worth of $1.1 million; in the 99th, it’s $10.1 million. Cross the threshold into the top 0.1%, and the figure balloons to $34 million or more. These aren’t outliers—they’re the rule for those who inherit wealth, own appreciating assets, or operate in industries where capital compounds. The median net worth of Black and Hispanic households remains a fraction of white households, a gap that persists even after controlling for income. What’s often overlooked is how net worth percentages by population segment interact with geography. In coastal cities like San Francisco or New York, the top 1% might hold 80% of local wealth, while in rural Appalachia, the bottom 40% could collectively own little more than their homes. This isn’t just urban vs. rural—it’s a reflection of how wealth begets wealth. A family with $500,000 in assets can pass it down; a family with $10,000 in savings is one medical emergency away from ruin. The numbers don’t lie, but they’re rarely told in full. When discussions about wealth in America or Europe surface, the focus often lands on the top 1%—the billionaires, the tech moguls, the legacy fortunes. Yet the real story lies in how average net worth by percentage of population shifts across the spectrum, from the bottom 20% to the top 0.1%. These figures aren’t just statistics; they’re a mirror reflecting systemic advantages, policy failures, and the quiet desperation of those left behind.The Verified Baseline
The most reliable snapshot comes from the Federal Reserve’s triennial Survey of Consumer Finances (SCF), last updated in 2022. The data is clear: the top 1% of U.S. households own nearly a third of all wealth, while the bottom 50% own just 2.6%. The median net worth for the bottom 20% is negative or near-zero, meaning their debts (student loans, credit cards, medical bills) exceed their assets. The middle class—roughly the 40th to 60th percentiles—has seen modest gains, but their net worth remains volatile, tied to home equity and retirement accounts. Internationally, the picture is similar but with national variations. In the UK, the top 10% hold 52% of net wealth, per the Wealth and Assets Survey. Germany’s wealth distribution is slightly more egalitarian, with the top 10% owning 45%, but the bottom 50% still hold just 3%. These aren’t just national quirks—they’re symptoms of tax policy, inheritance laws, and housing markets. In countries with strong social safety nets (like Nordic nations), the net worth percentage gaps by population tier narrow, but even there, the top 1% still outpace the rest. The data also reveals generational divides. Millennials, despite being the most educated generation, have net worth levels 20% lower than Gen X at the same age, adjusted for inflation. The reason? Stagnant wages, student debt, and the collapse of homeownership rates for younger adults. The percentage breakdown of net worth by age cohort shows that by 65, the top 10% of Baby Boomers had 10 times the wealth of the bottom 10%. For Millennials, that gap is widening.What the Estimates Suggest
Beyond verified data, estimates paint a picture of how average net worth by percentile could evolve—or deteriorate—under current trends. Economists at the Brookings Institution project that without policy intervention, the top 1% could hold over 50% of U.S. wealth by 2050, up from 35% today. The reasoning? Inheritance, capital gains, and the outsized returns on financial assets (stocks, private equity) that the wealthy already dominate. Meanwhile, the bottom 40% could see their net worth stagnate or decline as healthcare costs and housing prices outpace wage growth. In Europe, the European Central Bank’s wealth data suggests that net worth distribution by population segment is becoming more concentrated in Southern Europe, where youth unemployment and underemployment have eroded intergenerational wealth transfers. In Italy, for instance, the top 1% holds 30% of net wealth, but the bottom 50% holds just 1%. The estimates for France and Germany are slightly better, but the trend is unmistakable: wealth is pooling at the top, and the middle class is shrinking. What’s less discussed is how percentage-based net worth metrics interact with race. A 2021 study by the Urban Institute found that the median white family has 10 times the wealth of the median Black family, and 8 times that of a Hispanic family. Even when controlling for income, the gap persists. The reason? Historical redlining, predatory lending, and the inability to build generational wealth due to systemic barriers. These aren’t just statistical anomalies—they’re the result of policies that have disproportionately excluded entire demographics from wealth accumulation.
Case Study: A Closer Look
Consider Detroit, Michigan—a city where the net worth distribution by population percentile is among the most extreme in the U.S. In 2019, the median net worth of Black households in Detroit was $200, compared to $168,000 for white households. The disparity isn’t just about income; it’s about asset ownership. White families in Detroit are five times more likely to own their homes outright, while Black families are more likely to rent or hold mortgages with far less equity. The result? A wealth gap that persists even as wages converge. The city’s history of racial covenants, bank redlining, and industrial collapse explains part of the story. But the percentage breakdown of net worth also reflects modern challenges: predatory lending, lack of access to credit unions, and the inability to pass down wealth due to high debt burdens. A single foreclosure or medical debt can wipe out a family’s net worth entirely, trapping them in a cycle of liquidity poverty."Wealth isn’t just money—it’s the difference between a family that can weather a crisis and one that can’t. In Detroit, that difference is measured in generations." — Mark Rank, Professor of Social Welfare, Washington University| Factor | Estimated Impact on Net Worth Distribution | |--------------------------|-------------------------------------------------------------------------------------------------------------| | Homeownership Rate | Black households in Detroit: 30% homeownership rate; white households: 75%. Equity gap: $150K+. | | Student Debt | Black families carry $25K more in student debt on average, delaying asset accumulation. | | Inheritance | 90% of wealth transfers occur via inheritance; Black families receive $0 in most cases. | | Wage Stagnation | Real wages for Black workers have grown just 3% since 1970, while costs of living rose 120%. | | Predatory Lending | Black borrowers pay $3,500 more in interest over a 30-year mortgage than white borrowers with identical credit. | The Detroit case isn’t unique. Cities like Chicago, Cleveland, and St. Louis show similar patterns. The net worth percentages by population tier in these areas reveal a wealth apartheid: the haves and the have-nots, with little mobility in between.
What This Means Going Forward
The distribution of net worth by population segment isn’t just a snapshot—it’s a predictor. If current trends continue, the top 1% could control half of global wealth by 2030, according to Credit Suisse’s Global Wealth Report. The implications are profound. Political polarization deepens as the wealthy lobby for tax cuts that benefit them disproportionately. Social unrest rises as the middle class shrinks. And economic mobility—long the American dream—becomes a myth reserved for the already privileged. The data also forces a reckoning with net worth as a tool of power. Wealth isn’t just about consumption; it’s about influence. The top 1% don’t just have more money—they shape laws, education systems, and even cultural narratives. Meanwhile, the bottom 40% struggle with liquidity poverty, where a single emergency (car repair, medical bill) can derail years of progress. The percentage-based wealth divide isn’t just economic—it’s democratic.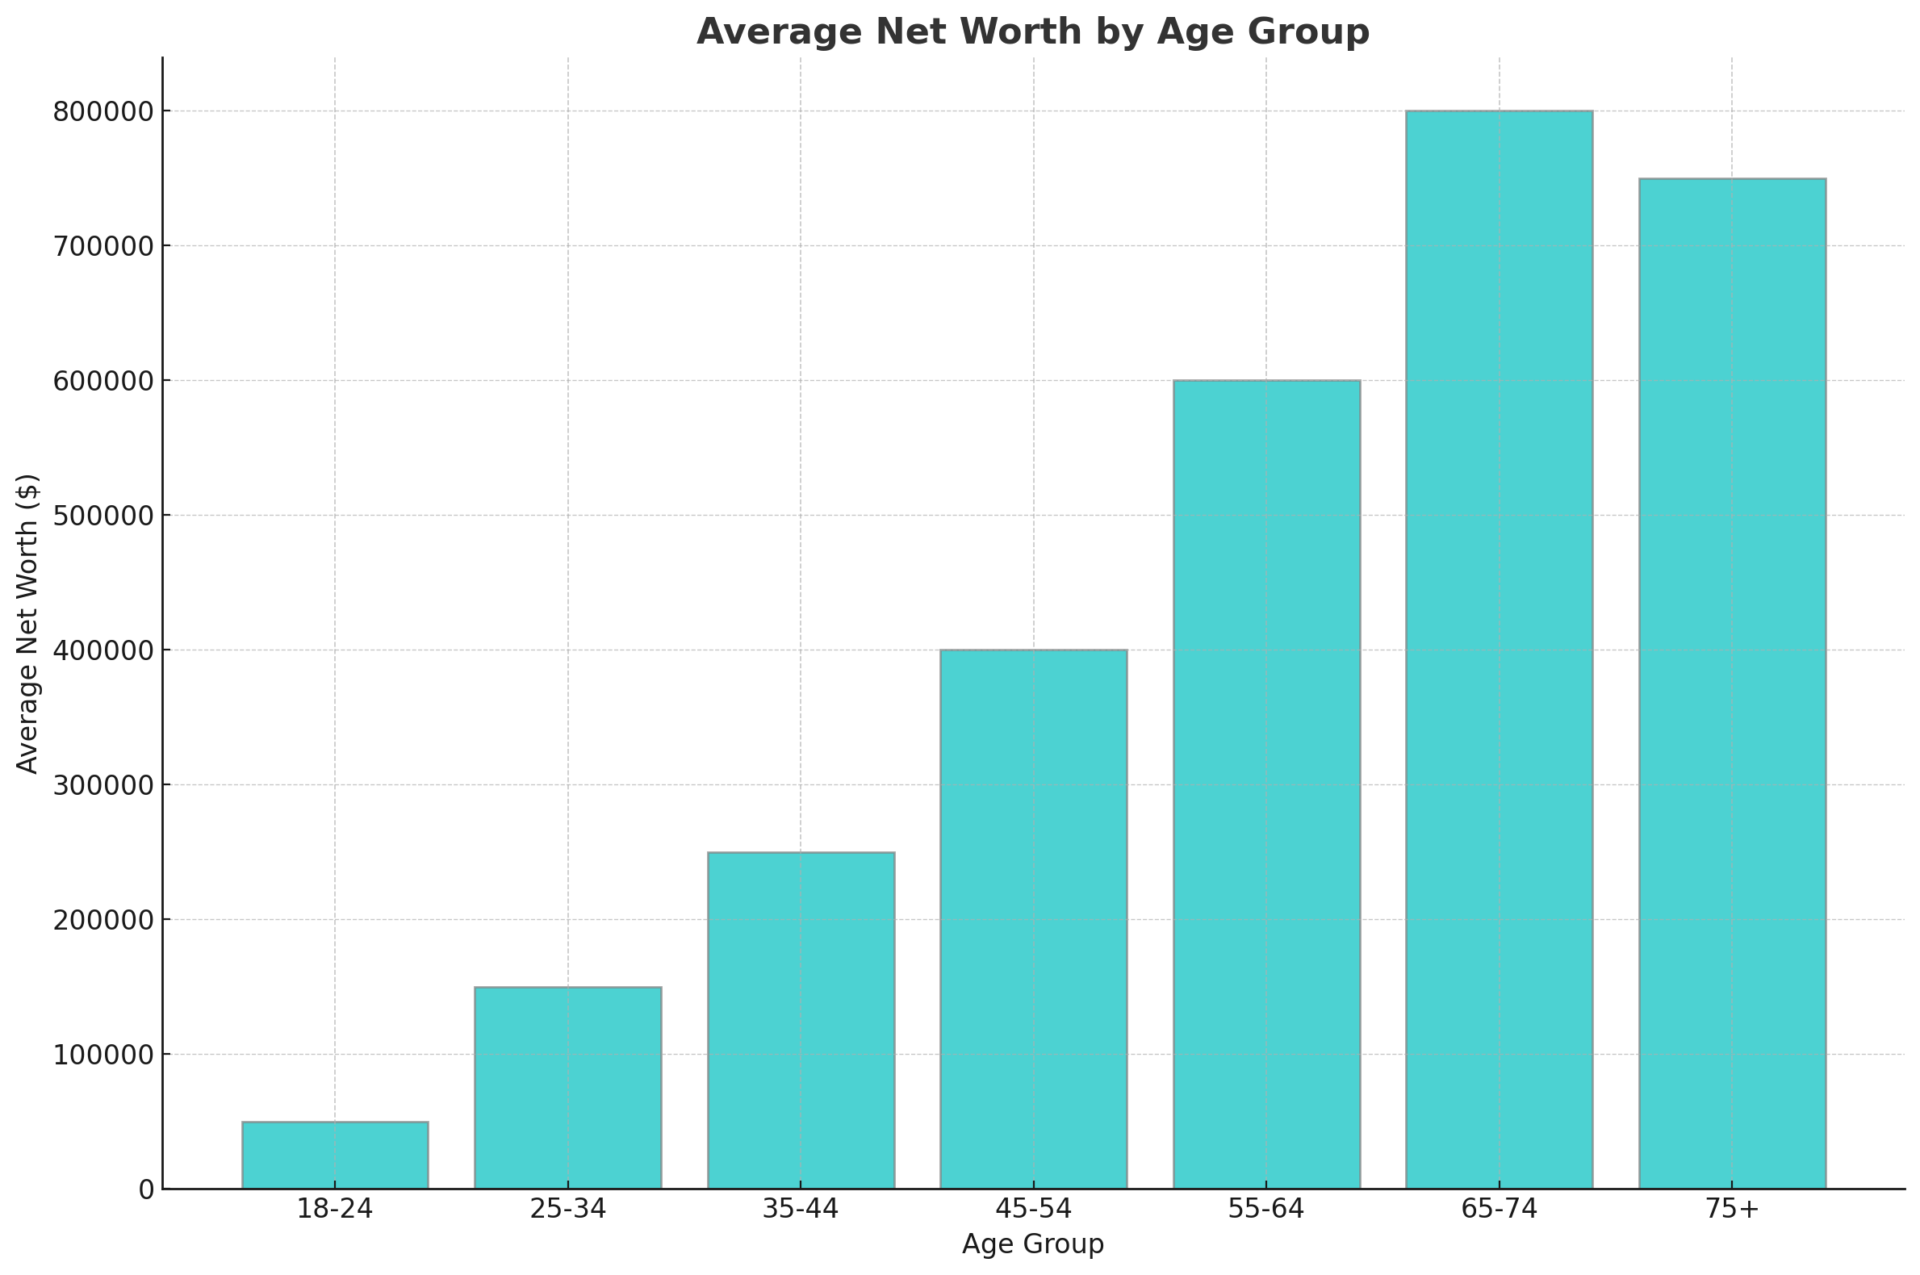
Conclusion
The numbers tell a story of two Americas, two Europes, two worlds. One where wealth compounds across generations, and another where debt and stagnation become a legacy. The average net worth by percentage of population isn’t just a statistic—it’s a measure of who gets to participate in the economy’s upside. Ignoring this divide is a choice, not an oversight. The question isn’t whether to address it, but how. Policy solutions exist: wealth taxes, baby bonds, expanded Social Security, and direct investments in Black and Latino communities. But political will is scarce. The data is clear. The net worth distribution by population percentile is worsening. The only question left is whether society will act before the divide becomes permanent.Comprehensive FAQs
Q: How does average net worth by percentage of population differ from median net worth?
The median net worth splits the population in half—half have more, half have less. But net worth by population percentile shows how wealth is concentrated. For example, the median U.S. net worth is around $130,000, but the top 10% holds $1.1 million+, while the bottom 20% often have negative or near-zero net worth. Median obscures the extreme disparities that percentiles reveal.
Q: Why does the percentage breakdown of net worth matter more than GDP growth?
GDP measures economic activity, but net worth distribution by population segment shows who actually benefits. A rising GDP can coexist with wealth hoarding by the top 1%, while the bottom 50% sees no gains. For example, the U.S. GDP grew 70% since 2000, but the median net worth of the bottom 90% grew just 20%. The percentage-based wealth gap determines who has economic security, not just who’s producing.
Q: How does race affect net worth by population percentile?
Racially, the net worth distribution by population tier is stark. White families have 10 times the wealth of Black families and 8 times that of Hispanic families, even at similar income levels. This stems from historical redlining, predatory lending, and wealth-stripping policies (e.g., mass incarceration, wage suppression). The percentage-based racial wealth gap is wider than the income gap, meaning wealth doesn’t just reflect current earnings—it reflects centuries of exclusion.
Q: Can average net worth by percentile improve without major policy changes?
Unlikely. Without structural shifts—like wealth taxes, inheritance reforms, or direct wealth transfers—the net worth distribution by population segment will continue skewing upward. Even strong economic growth benefits the wealthy first (e.g., stock market gains). The percentage-based wealth divide is self-reinforcing: the rich invest in assets that appreciate faster, while the poor lack the capital to do the same. Small tweaks (e.g., higher minimum wages) help, but systemic change is required to reverse the trend.
Q: What’s the biggest misconception about net worth percentages by population?
The biggest myth is that net worth by percentile is just about "laziness" or "poor choices." In reality, 90% of wealth is inherited, and the percentage-based distribution is shaped by tax policy, housing markets, and education access. A single family’s net worth trajectory is often determined by where they were born, their race, and whether their ancestors owned land. The average net worth by population segment isn’t a moral failing—it’s a structural outcome of how economies are designed.
