Where It All Began
Austin Russell’s obsession with lidar began in his teenage years, long before he ever considered dropping out of Stanford. At 16, he built his first lidar prototype in his parents’ garage, using off-the-shelf components and a Raspberry Pi. The project wasn’t just a hobby—it was a mission. He was convinced that traditional cameras and radar couldn’t replicate the human eye’s ability to perceive depth in complex environments. His early experiments, though crude, revealed a fundamental truth: lidar could see what other sensors couldn’t. The breakthrough came when Russell realized that the core challenge wasn’t just engineering—it was physics. Most lidar systems at the time relied on spinning mirrors or mechanical components, which limited their speed and accuracy. Russell’s insight was to eliminate those moving parts entirely. By 2012, at just 19 years old, he had developed a solid-state lidar design that could scan 1.3 million points per second—three times faster than anything on the market. The problem? No one was interested. Automakers were still skeptical of lidar’s viability, and venture capitalists saw it as a niche play. Undeterred, Russell founded Luminar in 2012 with $12 million in seed funding, including backing from Hyundai’s venture arm.The Early Signs
The first major validation came in 2015, when Luminar secured a $75 million Series B round, valuing the company at $250 million. The money wasn’t just for R&D—it was a signal. Investors were starting to take lidar seriously, but the road ahead was fraught with challenges. Competitors like Velodyne and Ouster had deeper pockets and longer track records. Luminar’s advantage, however, was its solid-state architecture, which promised lower power consumption and higher reliability. The catch? It required a complete redesign of the sensor’s optical and electronic systems. Russell’s leadership style was as unconventional as his technology. He eschewed the Silicon Valley playbook of rapid hiring and aggressive scaling, instead focusing on deep technical expertise. Early employees were recruited from MIT, Stanford, and DARPA programs, not because they fit a culture, but because they could solve the hardest problems. The company’s first major product, the IBEO LUX, launched in 2017, but it was a stopgap. The real prize was the HHD (Highly Scalable High Definition) lidar, a sensor that could operate at long range with unprecedented clarity. By 2019, Luminar had secured its first high-profile customer: Waymo, which began testing Luminar’s sensors in its robotaxis.The Turning Point
The inflection point arrived in 2021, when Hyundai Motor Group announced a $500 million investment in Luminar, valuing the company at $4.5 billion. The move wasn’t just financial—it was a strategic alliance. Hyundai’s decision to adopt Luminar’s lidar for its IONIQ 5 N electric vehicle marked the first time a mainstream automaker had committed to lidar as a standard feature. The market reacted instantly: Luminar’s stock (though private) was now being traded at valuations that rivaled public tech giants. Russell, who had spent years fending off doubts, suddenly found himself at the center of the autonomous vehicle revolution. The investment wasn’t just about revenue—it was about proving the scalability of lidar. Hyundai’s bet was that Luminar could mass-produce sensors at a fraction of the cost of earlier generations. The company’s HHD-32 sensor, launched in 2022, was designed to fit the price point of consumer vehicles, not just luxury models. The math was simple: if lidar could be affordable, it could become ubiquitous. The challenge, however, was execution. Manufacturing lidar at scale required a level of precision that few companies could match. Luminar’s factory in Orlando, Florida, became a test of whether Russell’s vision could translate into reality.“Lidar wasn’t just another sensor—it was the difference between a car that drives itself and one that just assists the driver. The moment we proved it could be cost-effective, the game changed.” — Austin Russell, 2022
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 2012–2014 | Founding of Luminar; first lidar prototypes; $12M seed round from Hyundai and others. Early skepticism from automakers. |
| 2015–2017 | Series B funding ($75M); launch of IBEO LUX sensor; focus shifts to solid-state design. Competitors like Velodyne dominate the market. |
| 2018–2019 | Waymo begins testing Luminar sensors; first revenue streams from automotive partners. Company valued at ~$1B. |
| 2020–2021 | Hyundai’s $500M investment; valuation jumps to $4.5B. HHD-32 sensor announced for mass production. |
| 2022–Present | IONIQ 5 N ships with Luminar lidar; expansion into defense and industrial markets. Rumors of potential IPO or acquisition. |
Lessons From the Journey
- Patience over speed. Russell’s refusal to rush into mass production—despite investor pressure—allowed Luminar to perfect its technology before scaling.
- Partnerships as validation. Hyundai’s early investment wasn’t just funding; it was proof that lidar could be trusted by automakers.
- The cost barrier was the biggest hurdle. Luminar’s success hinged on proving lidar could be affordable, not just high-performance.
- Defense contracts provided critical cash flow. While automotive was the long-term play, military applications kept Luminar afloat during lean years.
- Culture of deep expertise. Hiring engineers over salespeople ensured Luminar’s tech led the market, not its marketing.
Where Things Stand Today
As of 2024, Luminar’s net worth—when measured by private market valuations—remains one of the most closely watched in tech. The company’s revenue is estimated to have surpassed $100 million annually, driven by contracts with Hyundai, Toyota, and emerging players in robotaxis. The IONIQ 5 N’s success has positioned Luminar as the default lidar supplier for next-gen autonomous vehicles, but the real test will be scaling production to meet demand. Analysts suggest that if Luminar can reduce sensor costs below $500 per unit, it could trigger a wave of adoption across the industry. Russell himself has largely stepped back from day-to-day operations, though he remains the public face of the company. His net worth, while not publicly disclosed, is widely estimated to be in the hundreds of millions, largely tied to Luminar’s equity. The company’s next moves—whether an IPO, a strategic acquisition, or deeper automotive integration—will determine whether Russell’s gamble on lidar becomes a blueprint for future tech revolutions or a cautionary tale about overestimating market readiness.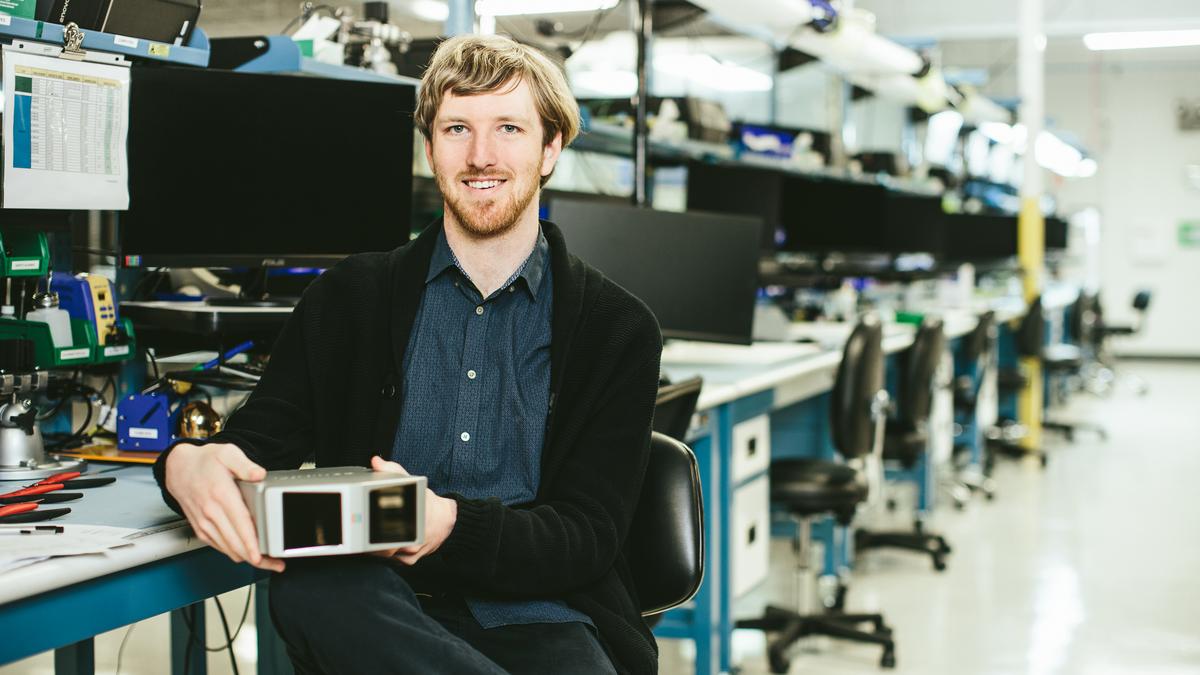
Conclusion
Austin Russell’s story is more than a rags-to-riches tale—it’s a case study in defying conventional wisdom. When most of Silicon Valley dismissed lidar as a dead-end technology, Russell bet everything on it. The payoff hasn’t just been financial; it’s a shift in how the world thinks about autonomous driving. Luminar’s net worth trajectory reflects a broader truth: sometimes, the most audacious bets are the ones that change industries. Yet, the journey isn’t over. The real test will be whether Luminar can deliver on its promise at scale—or if it becomes another cautionary tale about the gap between innovation and commercialization. For now, Russell’s legacy is secure. He didn’t just build a company; he redefined what’s possible in AI hardware. Whether Luminar’s net worth grows to $10 billion or plateaus at $5 billion, one thing is clear: the lidar revolution has only just begun.Comprehensive FAQs
Q: How did Austin Russell accumulate his wealth?
A: Russell’s wealth is primarily tied to his founder’s equity in Luminar Technologies, which has seen its valuation surge from $250 million in 2015 to over $4.5 billion by 2023. Early investments from Hyundai, Toyota, and defense contracts provided critical cash flow, while the company’s IPO-like valuation in 2021 cemented its status as a unicorn. Unlike many tech founders, Russell hasn’t taken a salary, reinvesting profits into R&D and scaling production.
Q: What is Luminar’s current valuation, and is an IPO likely?
A: As of 2024, Luminar’s private valuation is estimated at $4.5 billion to $5 billion, though exact figures aren’t disclosed. An IPO remains speculative—Hyundai’s 2021 investment included a put option allowing the automaker to sell its stake back to Luminar at a premium. Industry analysts suggest a public offering could happen by 2025, but only if Luminar achieves $200M+ in annual revenue and secures more automotive OEM contracts.
Q: How does Luminar’s lidar compare to competitors like Velodyne or Innoviz?
A: Luminar’s solid-state HHD sensors stand out for their longer range (up to 250 meters) and higher resolution (1.3M points/sec), but the key differentiator is cost. While Velodyne’s lidar remains the market leader in volume, Luminar’s HHD-32 is designed for mass-market affordability, targeting the $500–$1,000 price range. Innoviz, another Israeli competitor, focuses on shorter-range, lower-cost sensors, making Luminar’s tech a middle-ground solution for high-end autonomy.
Q: What role does defense play in Luminar’s business model?
A: Defense contracts have been critical to Luminar’s survival and growth, particularly in the early years. The U.S. Department of Defense and agencies like DARPA have funded lidar research for applications like drone navigation and battlefield mapping. These contracts provided steady revenue streams while Luminar waited for automotive adoption. As of 2024, defense accounts for ~20% of Luminar’s revenue, though the company is increasingly shifting focus to consumer and commercial markets.
Q: Could Luminar’s technology be used beyond autonomous vehicles?
A: Absolutely. Luminar’s lidar has applications in industrial automation, robotics, and even agriculture. For example, lidar can enable precision farming by mapping crop health and soil conditions. In robotics, it enhances 3D mapping and obstacle avoidance for drones and warehouse automation. The company has already explored partnerships in these sectors, though automotive remains the primary driver of growth.
Q: What’s the biggest risk to Luminar’s future success?
A: The biggest risk is scaling production without compromising quality. Lidar manufacturing requires extreme precision, and even minor defects can render sensors useless. Additionally, if competitors like Mobileye (Intel) or Tesla’s in-house solutions improve their camera-based alternatives, Luminar’s market share could shrink. Finally, regulatory hurdles—such as autonomous vehicle safety standards—could delay widespread adoption, impacting Luminar’s revenue timeline.
