Breaking Down the Numbers
ASML’s financials operate in two parallel universes: the public disclosures of its Dutch parent company, ASML Holding, and the private valuations of its U.S.-based subsidiary, ASML US. The latter, which handles most of the EUV business, operates under a different legal structure, allowing it to avoid full transparency. This duality creates a puzzle for investors and policymakers alike. While ASML Holding’s annual reports provide revenue figures—€25.6 billion in 2023, up from €23.3 billion the prior year—the ASML net worth in private markets remains a closely guarded secret. Industry estimates, however, place its enterprise value in the $300–350 billion range, making it the world’s most valuable private company by a wide margin. The company’s pricing power is its most formidable weapon. A single EUV lithography machine can cost $200 million or more, and ASML sells only a handful each year—deliberately limiting supply to maintain exclusivity. This strategy isn’t just about profit margins; it’s about preserving its monopoly. When TSMC announced a $39 billion order in 2021 (partially for ASML machines), it wasn’t just a procurement decision—it was a vote of confidence in ASML’s ability to sustain its ASML net worth through cyclical downturns. The company’s gross margins hover around 40–45%, far above typical capital equipment firms, reflecting its position as the sole provider of EUV tools for 3nm and below.The Verified Baseline
ASML Holding’s 2023 annual report confirms what insiders have long suspected: the company’s financials are decoupled from traditional tech cycles. While other semiconductor firms face boom-and-bust patterns tied to smartphone demand, ASML’s revenue grows steadily, driven by long-term contracts with foundries and IDMs. The 2023 report lists €25.6 billion in revenue, with €8.5 billion in net profit—a 33% margin, nearly double the average for industrial machinery companies. This profitability isn’t accidental; it’s the result of strategic supply constraints. ASML produces only about 15–20 EUV machines per year, despite demand that could easily absorb twice that volume. The company’s balance sheet is equally impressive. ASML Holding holds €12.3 billion in cash and equivalents as of 2023, a war chest that allows it to weather industry slowdowns without diluting shareholders. Its debt-to-equity ratio remains below 0.2, a rarity in capital-intensive industries. The real asset, however, isn’t listed on the balance sheet: ASML’s intellectual property. The company holds thousands of patents on EUV technology, many of which are essential patents—meaning no competitor can work around them without infringement. This IP moat is why ASML’s ASML net worth isn’t just about today’s revenue; it’s about the unassailable lead in next-gen lithography.What the Estimates Suggest
Private equity and industry analysts use a mix of DCF (discounted cash flow) models and comparable company analysis to estimate ASML’s ASML net worth. Given its lack of public trading, valuations rely on strategic multiples applied to its revenue and profit streams. One common approach compares ASML to publicly traded semiconductor equipment firms like Lam Research or Applied Materials, then adjusts for its monopoly position. Using this method, ASML’s enterprise value could range from $320 billion to $380 billion, depending on assumed growth rates and risk premiums. The geopolitical factor adds another layer. ASML’s machines are subject to U.S. export controls, meaning they can’t be sold to China without U.S. government approval. This implicit subsidy—the protection of Western governments—effectively increases ASML’s valuation by reducing competitive pressure. Some estimates suggest that without these controls, ASML’s ASML net worth could be 20–30% lower, as Chinese firms would develop alternatives. The company’s ability to leverage this geopolitical advantage is why its valuation remains decoupled from traditional market cycles.
Case Study: A Closer Look
No single event better illustrates ASML’s financial power than its 2021 $39 billion TSMC order. While the full breakdown wasn’t disclosed, industry sources confirmed that at least $20 billion of that sum was allocated to ASML’s EUV machines and related services. For ASML, this wasn’t just a sales record—it was a validation of its pricing strategy. The order allowed ASML to lock in multi-year revenue streams while ensuring TSMC remained dependent on its technology. This strategic lock-in is the cornerstone of ASML’s ASML net worth—because once a foundry commits to EUV, switching costs become prohibitive. The decision also highlighted ASML’s risk management. By requiring TSMC to pay upfront for machines that wouldn’t ship for years, ASML secured cash flow stability during the COVID-19 supply chain crisis. This pre-sales model is critical to understanding why ASML’s ASML net worth isn’t volatile like other tech firms’. While semiconductor stocks swing with every Fed rate hike, ASML’s revenue is backed by ironclad contracts. The trade-off? Limited scalability. ASML could theoretically sell more machines, but doing so would dilute its monopoly and risk inviting competitors into the EUV space."ASML doesn’t just sell machines—it sells access to the future of computing. That’s why its valuation isn’t about today’s revenue; it’s about the unassailable lead in a technology no one else can replicate." — Mark Lapedus, Editor-in-Chief, Semiconductor Engineering
| Factor | Estimated Impact on ASML Net Worth |
|---|---|
| EUV Monopoly | Adds $150–200 billion via pricing power and supply constraints. |
| U.S. Export Controls | Effectively subsidizes valuation by limiting Chinese competition, adding $50–80 billion. |
| TSMC/IDM Contracts | Multi-year orders provide $30–50 billion in locked-in revenue, reducing volatility. |
| R&D Lead in Next-Gen Lithography | Future-proofs valuation; high-frequency DUV/HMD could add $100+ billion if successful. |
What This Means Going Forward
ASML’s ASML net worth isn’t just a corporate metric—it’s a leading indicator for global tech trends. If AI demand surges, ASML benefits first, as foundries scramble to produce more advanced chips. If geopolitical tensions escalate, its machines become even more valuable as a tool of economic coercion. The company’s ability to charge premium prices while maintaining supply discipline ensures its ASML net worth will keep climbing, barring a technological breakthrough that disrupts its monopoly. The bigger question is what happens when ASML’s lead erodes. The company is already investing in high-numerical-aperture (HNA) EUV and high-power DUV, but these technologies won’t reach maturity for years. If China or a consortium of firms develops a workaround for EUV, ASML’s ASML net worth could face its first major correction. For now, however, the risks are asymmetric: ASML can fail, but no one else can succeed.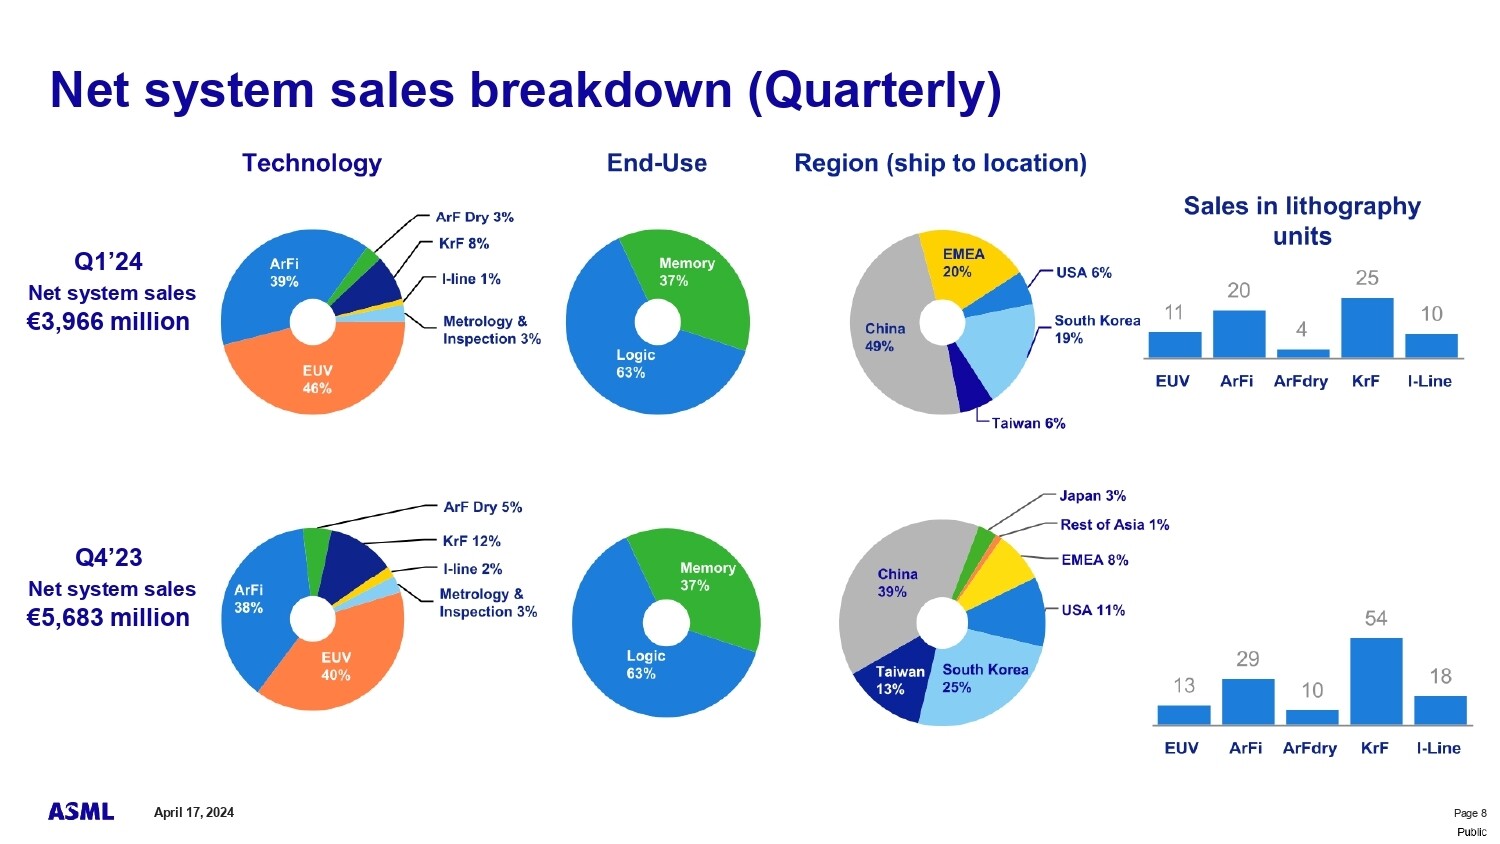
Conclusion
ASML’s financial dominance isn’t an accident—it’s the result of decades of strategic foresight, government backing, and ruthless execution. Its ASML net worth reflects more than just revenue; it represents control over the most critical node in the global tech supply chain. While other companies chase growth through scale, ASML thrives by limiting supply and raising prices. This model is unsustainable for most firms, but for ASML, it’s the only path to maintaining its monopoly. The company’s next challenge will be balancing growth with exclusivity. If it expands too quickly, it risks inviting competitors. If it stays too constrained, it may miss opportunities in emerging markets. Either way, ASML’s net worth will remain a bellwether for the semiconductor industry—because in the end, the firm that controls the machines controls the future.Comprehensive FAQs
Q: How does ASML’s valuation compare to other private companies?
ASML’s ASML net worth (~$300–350 billion) dwarfs other private tech firms. For context, SpaceX’s valuation is around $180 billion, and Rivian sits at ~$20 billion. ASML’s lead stems from its monopoly on EUV lithography, a position no other company holds.
Q: Why isn’t ASML publicly traded?
ASML’s Dutch parent, ASML Holding, is publicly traded on Euronext Amsterdam, but its most valuable subsidiary (ASML US) remains private to protect its monopoly. Going public could expose its pricing strategy to regulatory scrutiny or attract competitors. The company has no plans to IPO its core EUV business.
Q: How do U.S. export controls affect ASML’s valuation?
U.S. restrictions on selling ASML’s EUV machines to China artificially inflate its worth by limiting competition. Without these controls, Chinese firms (like Shanghai Micro Electronics) could develop alternatives, reducing ASML’s net worth by 20–30%. The U.S. effectively acts as a silent partner in ASML’s business model.
Q: What’s the biggest threat to ASML’s financial dominance?
The biggest risk isn’t competition—it’s irrelevance. If ASML fails to innovate beyond EUV (e.g., by missing the transition to high-numerical-aperture lithography), foundries may seek alternatives. A technological plateau could also hurt its ASML net worth if demand for advanced nodes slows.
Q: How does ASML’s pricing strategy work?
ASML deliberately limits supply while charging $150–200 million per EUV machine. It also requires multi-year contracts and upfront payments, locking in revenue even before production. This supply-side discipline ensures its ASML net worth remains insulated from industry downturns.
Q: Could China ever challenge ASML’s monopoly?
China has invested billions in semiconductor R&D, but breaking ASML’s EUV monopoly would require a decade-long effort. Even then, ASML’s patent wall and U.S. export controls make it nearly impossible. Short-term, China’s best bet is high-power DUV, but this won’t replace EUV for advanced nodes.
Q: What’s ASML’s biggest expense?
R&D accounts for ~15–20% of revenue (~€4–5 billion annually). Most spending goes toward next-gen lithography, including high-NA EUV and HMD. Unlike other tech firms, ASML’s R&D isn’t just an expense—it’s an insurance policy against obsolescence.
