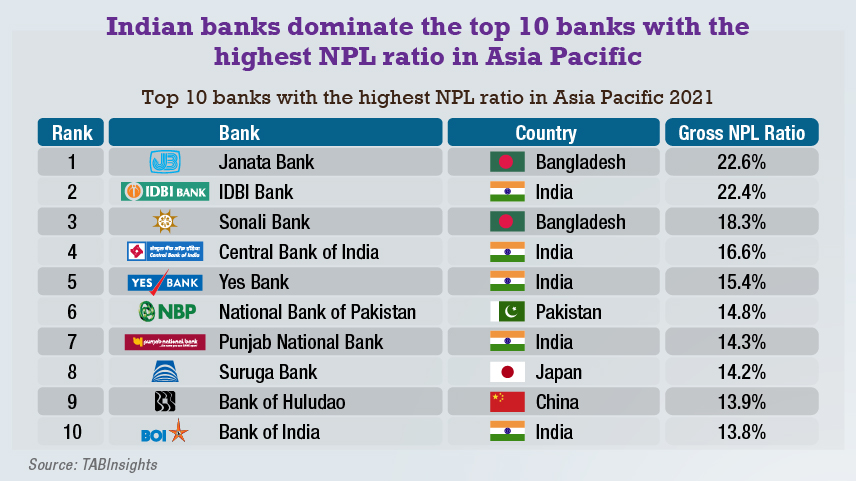
The Complete Overview of the Top 10 Banks in Asia
The top 10 banks in Asia operate in a landscape defined by three forces: regulatory divergence, digital transformation, and geopolitical realignment. Unlike their Western counterparts, these institutions navigate fragmented markets where China’s state-controlled banks coexist with Singapore’s private-sector innovators. The result? A patchwork of business models—from ICBC’s policy-driven lending to Standard Chartered’s niche in trade finance—each tailored to local priorities. Even within the same country, banks serve distinct roles: Japan’s Mitsubishi UFJ Financial Group (MUFG) dominates retail banking, while SMBC focuses on corporate finance and global markets. What unites them is ambition. The leading Asian banks aren’t content with regional dominance; they’re targeting global expansion. HSBC’s pivot to Asia decades ago is now being mirrored by Chinese banks like Bank of China, which has aggressively courted European and African clients. Meanwhile, South Korea’s KB Financial Group is leveraging its expertise in shipbuilding and semiconductors to secure loans for infrastructure projects in Southeast Asia. The stakes are clear: control the region’s financial flows, and you control its economic future.Historical Background and Evolution
The origins of today’s top 10 banks in Asia trace back to the post-WWII era, when Japan and South Korea’s industrialization demanded robust financial systems. Mitsubishi Bank (now MUFG) was instrumental in funding Japan’s zaibatsu conglomerates, while Korea’s Shinhan Bank emerged from the wreckage of the Korean War to become a pillar of Seoul’s chaebol system. These banks weren’t just lenders—they were extensions of state power, channeling capital into strategic sectors like steel, shipbuilding, and electronics. The 1997 Asian financial crisis acted as a crucible. Banks that had overextended—like Thailand’s Bangkok Bank—collapsed, while survivors like Singapore’s DBS and OCBC emerged stronger, adopting stricter risk management. The crisis also accelerated consolidation: Japan’s banking sector shrank from 150 institutions in the 1980s to a handful of megabanks today. China’s Big Four (ICBC, CCB, ABC, BOC) were later shaped by Beijing’s push for state-led capitalism, with ICBC’s 2006 IPO—the world’s largest at the time—symbolizing China’s financial ascendance.Core Mechanisms: How It Works
The leading banks in Asia operate under three interconnected frameworks: government alignment, digital infrastructure, and cross-border networks. Take ICBC: its lending priorities reflect Beijing’s Belt and Road Initiative, with loans funneled into energy projects in Pakistan and rail links to Europe. Meanwhile, Singapore’s banks like UOB and DBS have built ecosystems around their digital platforms, offering everything from AI-driven credit scoring to blockchain-based trade finance. Their success hinges on blending traditional banking with tech—something Western banks often struggle to replicate. What distinguishes these institutions is their regional interconnectivity. MUFG’s global network, for example, includes a dedicated unit for yen-denominated loans to Asian corporates, while Standard Chartered’s trade finance arm connects Indian exporters with African importers. The result is a financial plumbing system that moves trillions annually with minimal friction—critical for a region where 60% of trade is still settled in cash or letters of credit.Key Benefits and Crucial Impact
The top 10 banks in Asia don’t just move money—they move economies. Their balance sheets fund everything from Indonesia’s toll roads to Taiwan’s semiconductor plants. When ICBC lends $1 billion to a Chinese state-owned enterprise for a port in Sri Lanka, it’s not just a loan; it’s a geopolitical statement. Similarly, when DBS launches a digital bank in Vietnam, it’s not just competition—it’s a signal that Southeast Asia’s financial future lies in Singapore’s orbit. These banks also act as stabilizers in turbulent markets. During the 2020 pandemic, MUFG and SMBC provided $100 billion+ in liquidity to Japanese firms, while Indian banks like HDFC Bank extended moratoriums on loans to small businesses. Their ability to absorb shocks—thanks to conservative capital ratios and government backstops—makes them more resilient than many Western peers. > "Asia’s banks are the region’s immune system. They don’t just survive crises—they turn them into opportunities." > — Ravi Menon, former Managing Director of the Monetary Authority of SingaporeMajor Advantages
- State and private synergy: Banks like ICBC and MUFG benefit from implicit government guarantees, while private players like DBS and OCBC enjoy regulatory flexibility.
- Digital-first infrastructure: Singapore’s banks process 90% of transactions via mobile apps, outpacing Western incumbents in fintech adoption.
- Cross-border expertise: Standard Chartered’s trade finance arm handles 12% of global non-oil trade, a niche few Western banks can match.
- Low-cost funding: Chinese banks access capital at near-zero rates via the PBOC, giving them a perpetual edge in lending margins.
- Regional dominance: No single Western bank matches the footprint of MUFG or ICBC, which operate in 20+ countries each.
- Ecosystem integration: Banks like KB Financial Group in Korea partner with conglomerates (e.g., Samsung, Hyundai) to bundle financial and industrial services.

Comparative Analysis
| Bank | Key Strengths |
|---|---|
| Mitsubishi UFJ Financial Group (Japan) | Global markets leadership, yen-denominated lending, deep corporate relationships. |
| Industrial and Commercial Bank of China (ICBC) | State-backed lending, Belt and Road financing, largest balance sheet in Asia. |
| Mizuho Financial Group (Japan) | Asset management dominance, post-crisis restructuring expertise. |
| DBS Bank (Singapore) | Fintech innovation, Southeast Asia expansion, digital banking leadership. |
| Standard Chartered (UK/Asia) | Trade finance specialization, Indian/African market access, hybrid Anglo-Asian model. |
Future Trends and Innovations
The next decade will belong to the top 10 banks in Asia that master three shifts: AI-driven risk assessment, tokenized assets, and geo-financial sovereignty. Chinese banks are already testing digital yuan use cases with ICBC, while Singapore’s DBS has launched a blockchain-based bond issuance platform. Meanwhile, Japan’s MUFG is exploring CBDCs to streamline cross-border payments—a direct challenge to SWIFT’s dominance. Geopolitics will also reshape the landscape. As Western sanctions tighten, Asian banks are building alternative payment rails. The leading banks in Asia are positioning themselves as neutral hubs, whether through ICBC’s oil-trade financing in Russia or DBS’s push into the Middle East. The risk? Over-reliance on state mandates could stifle innovation—but the reward for those who balance autonomy and alignment could be unprecedented growth.
Conclusion
The top 10 banks in Asia are no longer followers in global finance—they’re architects. Their ability to blend tradition with disruption, local ties with global reach, and state influence with private-sector agility sets them apart. The Western banking model, built on universal principles, is being outmaneuvered by a region where finance is as much about geopolitics as it is about profit. For businesses and investors, the message is clear: Asia’s banks aren’t just competitors—they’re partners in shaping the future. Whether through ICBC’s infrastructure loans or DBS’s digital ecosystems, these institutions are rewriting the rules of finance. The question isn’t whether to engage with them—it’s how to leverage their networks before the next wave of consolidation begins.Comprehensive FAQs
Q: Which bank in the top 10 banks in Asia has the largest market capitalization?
A: As of recent data, Industrial and Commercial Bank of China (ICBC) holds the largest market cap among Asian banks, reflecting its status as the world’s largest bank by assets. However, valuations fluctuate with regulatory shifts and macroeconomic conditions.
Q: How do the leading banks in Asia compare to Western banks in digital banking?
A: Asian banks lead in mobile-first adoption—Singapore’s DBS and OCBC process over 90% of transactions via apps, while Western banks lag due to legacy systems. Chinese banks like ICBC are also faster in deploying AI for credit scoring, reducing loan approval times by up to 70%.
Q: Are the top 10 banks in Asia exposed to U.S. sanctions risks?
A: Yes, particularly banks with significant exposure to Russia or Iran. ICBC and Bank of China have faced secondary sanctions for trade with sanctioned entities, though they mitigate risks by using offshore entities or local currencies (e.g., yuan, ruble). Compliance costs have risen sharply for these institutions.
Q: Which bank in the list is best for SMEs in Southeast Asia?
A: DBS Bank and OCBC are the top choices for SMEs in Southeast Asia, offering digital lending platforms like DBS Digibank’s SME loans and OCBC’s Trade Finance Online. Both banks also provide government-backed guarantees in markets like Indonesia and Vietnam.
Q: How do the leading Asian banks handle currency risk in cross-border lending?
A: Most use dynamic hedging strategies, such as MUFG’s yen-denominated loans to Asian corporates or Standard Chartered’s multi-currency trade finance solutions. Chinese banks often rely on the PBOC’s FX interventions to stabilize lending in local currencies, while Singaporean banks hedge via offshore centers like Hong Kong.
Q: What’s the biggest threat to the top 10 banks in Asia?
A: Regulatory fragmentation is the most pressing threat. For example, China’s capital controls and Singapore’s strict AML laws create compliance burdens, while Japan’s aging population reduces domestic loan demand. Additionally, fintech disruptors (e.g., Ant Group in China) could erode traditional banking revenues if regulatory barriers fall.
