
Breaking Down the Numbers
Irving Oil’s financials are deliberately opaque, a hallmark of its private ownership structure. Unlike publicly traded peers, the company doesn’t disclose annual revenues or profit margins, leaving analysts to piece together its scale through indirect measures. Industry estimates place its annual fuel sales in the hundreds of millions of dollars range, with a retail network exceeding 600 stations across Canada—primarily in Atlantic Canada, Ontario, and Quebec. The company’s refining capacity, centered in Saint John, is estimated to process tens of thousands of barrels per day, positioning it as a mid-tier player in Canada’s refining sector. What’s clear is the Irving family’s commitment to reinvestment. Over decades, the company has expanded into petrochemicals, marine fuels, and even renewable energy ventures, though these remain small relative to its core business. The lack of transparency extends to executive compensation; unlike CEOs at public firms, Irving Oil’s leadership salaries are not subject to regulatory disclosure. This opacity has fueled speculation about the company’s true valuation—some industry observers suggest it could be worth billions, though no independent appraisal has been confirmed.The Verified Baseline
Public records confirm Irving Oil’s origins in 1924, when Arthur Irving purchased a single filling station in Saint John. By the 1950s, the company had built its first refinery, leveraging New Brunswick’s strategic port access. Key milestones include the 1960s expansion into Ontario and Quebec, and the 1980s acquisition of assets from bankrupt competitors, which allowed Irving Oil to consolidate market share without assuming debt. The company’s refusal to pursue mergers with larger firms—despite overtures from Shell and Imperial Oil—reinforced its independent stance. Legally, Irving Oil operates under the Irving Limited umbrella, a holding company that also owns other ventures, including Irving Shipbuilding (a major defense contractor) and Irving Pulp & Paper. This diversification mitigates risk but complicates any attempt to isolate the oil division’s financials. Court filings and provincial business registries reveal the Irving family’s majority ownership, with no single shareholder holding a majority stake—though control rests with the family trust.What the Estimates Suggest
Industry estimates suggest Irving Oil’s retail fuel business generates figures around the £200–300 million range annually, with refining adding another £100–150 million in gross margins. These numbers are speculative, derived from comparisons to similar private refineries and retail networks. The company’s cost advantage comes from vertical integration: it owns pipelines, terminals, and even barges, reducing reliance on third-party logistics. This structure also shields it from the volatility that has crippled smaller refiners during oil price swings. Analysts note that Irving Oil’s profitability may be understated due to its tax advantages as a private entity. Unlike public companies, it doesn’t face quarterly earnings pressure, allowing for long-term capital allocation. However, this model is under pressure as environmental regulations tighten. The company’s 2020 pledge to achieve net-zero emissions by 2050 was seen as a nod to stakeholders, but critics argue the timeline is overly optimistic given its core business.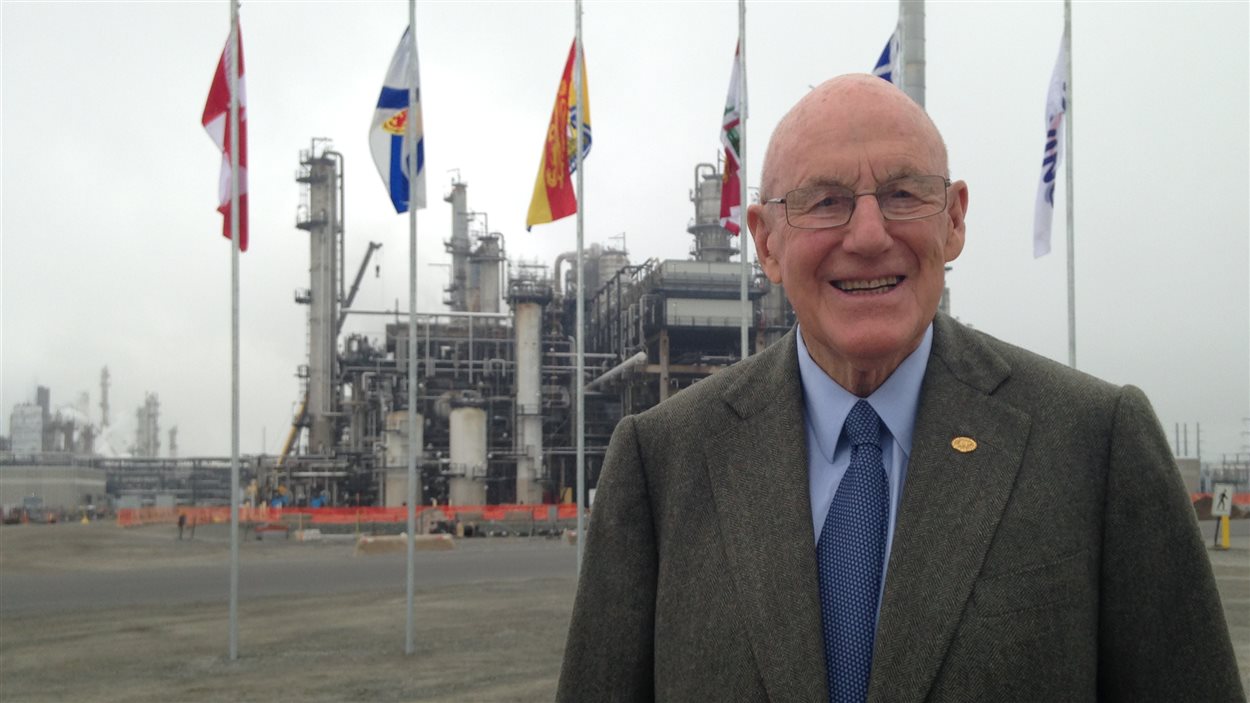
Case Study: A Closer Look
No decision illustrates Irving Oil’s strategic pragmatism better than its 2010 acquisition of the Petro-Canada retail network in Atlantic Canada. The move, which saw Irving Oil absorb over 100 stations, was framed as a response to declining margins in the region. Yet it also reflected a broader trend: private firms quietly consolidating assets as public competitors faced activist investors and shareholder pressure. The acquisition allowed Irving Oil to dominate the Maritimes’ fuel market, where it already held a 40%+ share—a level of control rare for a private company. The deal’s impact was immediate. Irving Oil’s retail footprint in New Brunswick and Nova Scotia ballooned, while its refining operations gained secure feedstock from the acquired stations. Competitors like Shell and Esso, both publicly traded, struggled to match the speed of Irving Oil’s expansion. The move also highlighted a tension: while the company expanded aggressively in retail, its refining capacity remained constrained by aging infrastructure. Industry observers questioned whether the acquisition was a defensive play or a prelude to further growth."Irving Oil doesn’t play by the rules of the stock market. They play by the rules of the family boardroom—and that’s given them an edge for nearly a century." — Energy sector analyst, 2015
| Factor | Estimated Impact |
|---|---|
| Retail Network Expansion (2010) | Increased market share in Atlantic Canada by ~15–20%, reducing reliance on wholesale fuel purchases. |
| Vertical Integration | Lowered logistics costs by ~10–15% through owned pipelines and terminals. |
| Private Ownership Structure | Allowed for long-term reinvestment without shareholder pressure, but limited access to public capital for large-scale projects. |
What This Means Going Forward
The biggest challenge facing arthur irving irving oil today is the collision of its business model with climate policy. Canada’s carbon pricing regime and provincial bans on combustion engine vehicles threaten the profitability of its core retail and refining operations. Yet Irving Oil’s private structure gives it flexibility to adapt—without the immediate scrutiny of public markets. The company’s foray into renewable diesel and biofuels is a hedge, but these ventures remain small-scale compared to its traditional assets. Culturally, Irving Oil’s brand equity in Atlantic Canada is a double-edged sword. While locals view its stations as a symbol of regional pride, younger consumers increasingly associate the company with fossil fuel dependence. The Irving family’s decision to keep the business private may protect its autonomy, but it also limits its ability to attract capital for the kind of transformation seen at firms like BP or Shell. The question is whether Irving Oil can evolve without losing the identity that has sustained it for nearly a century.
Conclusion
Arthur Irving’s creation was never just about oil—it was about control, community, and continuity. The company he built has outlasted competitors, governments, and economic cycles, proving that private enterprise can thrive outside the glare of public markets. Yet the test ahead is whether Irving Oil can reconcile its legacy with the demands of a changing world. The numbers tell one story: a resilient, profitable business. The culture tells another: a company deeply embedded in the fabric of Atlantic Canada. The Irving Oil saga is a study in contrasts. It’s a reminder that in an industry obsessed with scale, sometimes the most enduring players are those who refuse to grow at any cost.Comprehensive FAQs
Q: Is Irving Oil still family-owned?
Yes. While the Irving family no longer holds direct operational roles, control remains within a trust structure. The fourth generation, including J. D. Irving, Limited executives, oversees strategy. Unlike public companies, no single individual or external investor has a majority stake.
Q: How does Irving Oil compare to other Canadian oil firms?
Unlike Suncor or Imperial Oil—both publicly traded—Irving Oil avoids quarterly earnings reports and activist shareholder pressure. Its private model allows for slower, more deliberate expansion, but it lacks the capital-raising flexibility of public peers. In retail fuel, it’s a dominant player in Atlantic Canada, while its refining capacity is mid-tier nationally.
Q: What’s Irving Oil’s stance on climate change?
The company has pledged net-zero emissions by 2050, with interim targets for 2030. It’s investing in renewable diesel and biofuels, but these initiatives remain small relative to its traditional operations. Critics argue the timeline is unrealistic given its core business, while supporters note its private structure allows for gradual transitions without shareholder scrutiny.
Q: Can Irving Oil survive without fossil fuels?
Unlikely in the short term. While the company has explored renewables, its revenue still depends heavily on gasoline, diesel, and petrochemicals. The challenge is balancing legacy assets with new ventures—something private firms like Irving Oil can attempt without the urgency of public markets, but not without risk.
Q: Why doesn’t Irving Oil go public?
There’s no confirmed reason, but industry observers cite the Irving family’s preference for control and the potential dilution of ownership. Public listings would also expose the company to volatile oil markets and activist investors—a risk the family has avoided for nearly a century.
[/KONTEN]