The Short Answers
- Arizona probate typically takes 6–18 months for uncontested estates, but net worth property delays can extend timelines if appraisals or creditor claims arise.
- Property in probate is appraised at fair market value (not purchase price), with Arizona courts often relying on comparable sales or professional assessments.
- Heirs avoid probate entirely by using trusts, joint tenancy, or beneficiary designations—tools that bypass court oversight and preserve death probate net worth property integrity.
- Estate taxes in Arizona are minimal (federal thresholds apply), but property transfer taxes (e.g., documentary fees) can add 0.5%–1.5% to the sale value.
- Contested probates over high-value property often hinge on undisclosed debts, forged documents, or valuation disputes—common in cases involving Arizona death probate net worth property.
- Executors must file an Inventory and Appraisal within 3 months of appointment, listing all assets—including real estate, bank accounts, and intangible assets—with their probate values.

Deep Dive: The Full Picture
Arizona’s probate system operates under Arizona Revised Statutes Title 14, which governs how estates are administered after death. When an individual dies intestate (without a will) or with a will that triggers probate, their net worth property becomes subject to court supervision. This includes real estate, personal property, investments, and even digital assets—each requiring meticulous valuation. The court’s primary goal is to ensure fair distribution to heirs and creditors, but the process often exposes discrepancies between book value and liquidation value, especially in volatile markets like Arizona’s real estate sector. The net worth property equation grows more complex when the deceased owned multiple properties or assets in trusts. For example, a Phoenix-area estate might include a primary residence, rental properties, and undeveloped land—each with distinct appraisal challenges. Arizona courts may appoint a professional appraiser if heirs dispute valuations, adding time and cost. Meanwhile, creditors have 90 days to file claims, and unpaid debts can reduce the estate’s net worth property by forcing asset sales at depressed prices.The Context You Need
Arizona’s death probate net worth property landscape is shaped by three key variables: market conditions, legal precedents, and executor competence. The state’s no state estate tax policy (federal thresholds apply) reduces one layer of complexity, but property transfer taxes and probate fees (up to 4% of the estate’s value) still eat into inheritances. For instance, a Scottsdale estate worth $5 million could incur $200,000+ in fees if probate drags on, assuming no trusts were used. Another critical factor is Arizona’s homestead exemption, which protects up to $150,000 in equity in a primary residence from creditors. However, this exemption doesn’t shield the property from probate valuation—only from forced sale to satisfy debts. Executors must navigate this by ensuring the homestead is properly designated and that all liens or mortgages are accounted for in the net worth property assessment. Failure to do so can lead to undervaluation claims or disputes over which assets cover outstanding obligations.The Mechanics
The probate process in Arizona begins with the petition for probate, where the will (if any) is filed with the Superior Court. The court then appoints an executor, who must publish a Notice to Creditors and file an Inventory and Appraisal listing all assets—including real estate, vehicles, and financial accounts—with their probate values. This document is the foundation for net worth property calculations, as it sets the baseline for distributions and tax filings. Property valuation is where most disputes arise. Arizona courts prefer arm’s-length transactions as the gold standard, meaning appraisals should reflect what a willing buyer would pay in an open market. For Arizona death probate net worth property, this often involves: - Comparable sales analysis (recent transactions of similar properties in the same area). - Income capitalization (for rental properties, based on net operating income). - Cost approach (useful for unique properties like historic homes or land). Executors who underestimate these steps risk undervaluation penalties or overvaluation challenges from heirs seeking larger shares. In high-stakes cases, special administrators may be appointed to oversee appraisals, adding another layer of cost.Details That Change the Picture
Not all Arizona death probate net worth property cases unfold the same way. Hidden complexities—such as offshore accounts, cryptocurrency holdings, or undocumented business interests—can derail proceedings. For example, a Tucson estate might include a family-owned LLC with undeclared assets, forcing the executor to pierce the corporate veil to uncover true net worth property values. Similarly, joint tenancy properties (where ownership passes automatically) may still require probate if titles are unclear or co-owners have conflicting claims. Tax implications further complicate matters. While Arizona lacks a state estate tax, capital gains taxes apply when inherited property is sold. If an heir inherits a $1 million Scottsdale mansion but sells it for $1.2 million within a year, the $200,000 gain could trigger federal taxes—unless the executor structures the sale to defer liabilities. Meanwhile, property transfer taxes (e.g., documentary fees) can add $5,000–$20,000 to the transaction, depending on the county."In Arizona probate cases, the biggest mistake executors make is assuming ‘fair market value’ is the same as ‘insured value’ or ‘purchase price.’ Courts will scrutinize appraisals, especially for high-value property. A $2 million home might appraise for $1.8 million in a downturn—and that $200,000 difference can mean the difference between covering debts or triggering a sale at a loss." — Attorney David M. James, Arizona Probate Specialist
| Factor | Impact on Arizona Death Probate Net Worth Property |
|---|---|
| Probate Fees | Up to 4% of estate value; higher for contested cases or complex assets. |
| Property Transfer Taxes | 0.5%–1.5% of sale price (varies by county); applies even to inherited property. |
| Homestead Exemption | Protects up to $150K equity from creditors but doesn’t exclude property from probate valuation. |
| Appraisal Disputes | Can delay distributions by 6–12 months; professional appraisers cost $1,500–$5,000+ per property. |
| Contested Wills | Adds $50K–$200K+ in legal fees; common in cases with undisclosed assets or forged documents. |
Conclusion
Navigating Arizona death probate net worth property requires more than legal knowledge—it demands financial foresight. Executors who treat probate as a mere administrative hurdle often overlook how valuation methods, tax strategies, and asset structuring can preserve—or erode—an estate’s true worth. The best protection? Proactive planning. Trusts, beneficiary designations, and clear titling can sidestep probate entirely, ensuring heirs inherit assets without court delays. For those already in probate, transparency in appraisals and early creditor notifications can mitigate disputes. The bottom line: Arizona’s probate system is not the enemy of estate value—but poor execution can be. Whether dealing with a $500K ranch or a $10 million portfolio, the principles remain the same: document everything, challenge questionable valuations, and prioritize tax-efficient distributions. The desert doesn’t forgive sloppiness—and neither do Arizona courts.Comprehensive FAQs
Q: How long does Arizona probate take for property-heavy estates?
Arizona probate for net worth property-centered estates typically ranges from 6 to 18 months, but complex cases (e.g., multiple properties, disputed wills, or creditor claims) can extend to 2–3 years. Courts prioritize Inventory and Appraisal filings within 3 months, but delays in appraisals or title searches often push timelines.
Q: Can heirs sell inherited Arizona property before probate is finalized?
No. In Arizona, inherited property remains under probate control until the court issues a final distribution order. Selling without approval risks legal penalties, including voided transactions or liability for unpaid debts. Executors must obtain court permission for pre-probate sales, which is rare unless the estate is severely indebted.
Q: Does Arizona probate affect the value of inherited property for tax purposes?
Yes. While inherited property receives a step-up in basis (eliminating capital gains on the deceased’s original purchase), Arizona probate can introduce additional costs: - Probate fees (up to 4% of estate value). - Property transfer taxes (county-specific, 0.5%–1.5%). - Appraisal costs if valuations are contested. These reduce the net worth property available to heirs, especially in high-value cases.
Q: What happens if an executor undervalues property in Arizona probate?
Undervaluation is a legal risk in Arizona probate. If heirs or creditors allege fraudulent undervaluation, the executor may face: - Personal liability for the difference. - Removal from the role by the court. - Criminal charges in cases of intentional deception. Courts often rely on comparable sales data or professional appraisals to verify accuracy.
Q: How can I avoid Arizona probate for real estate?
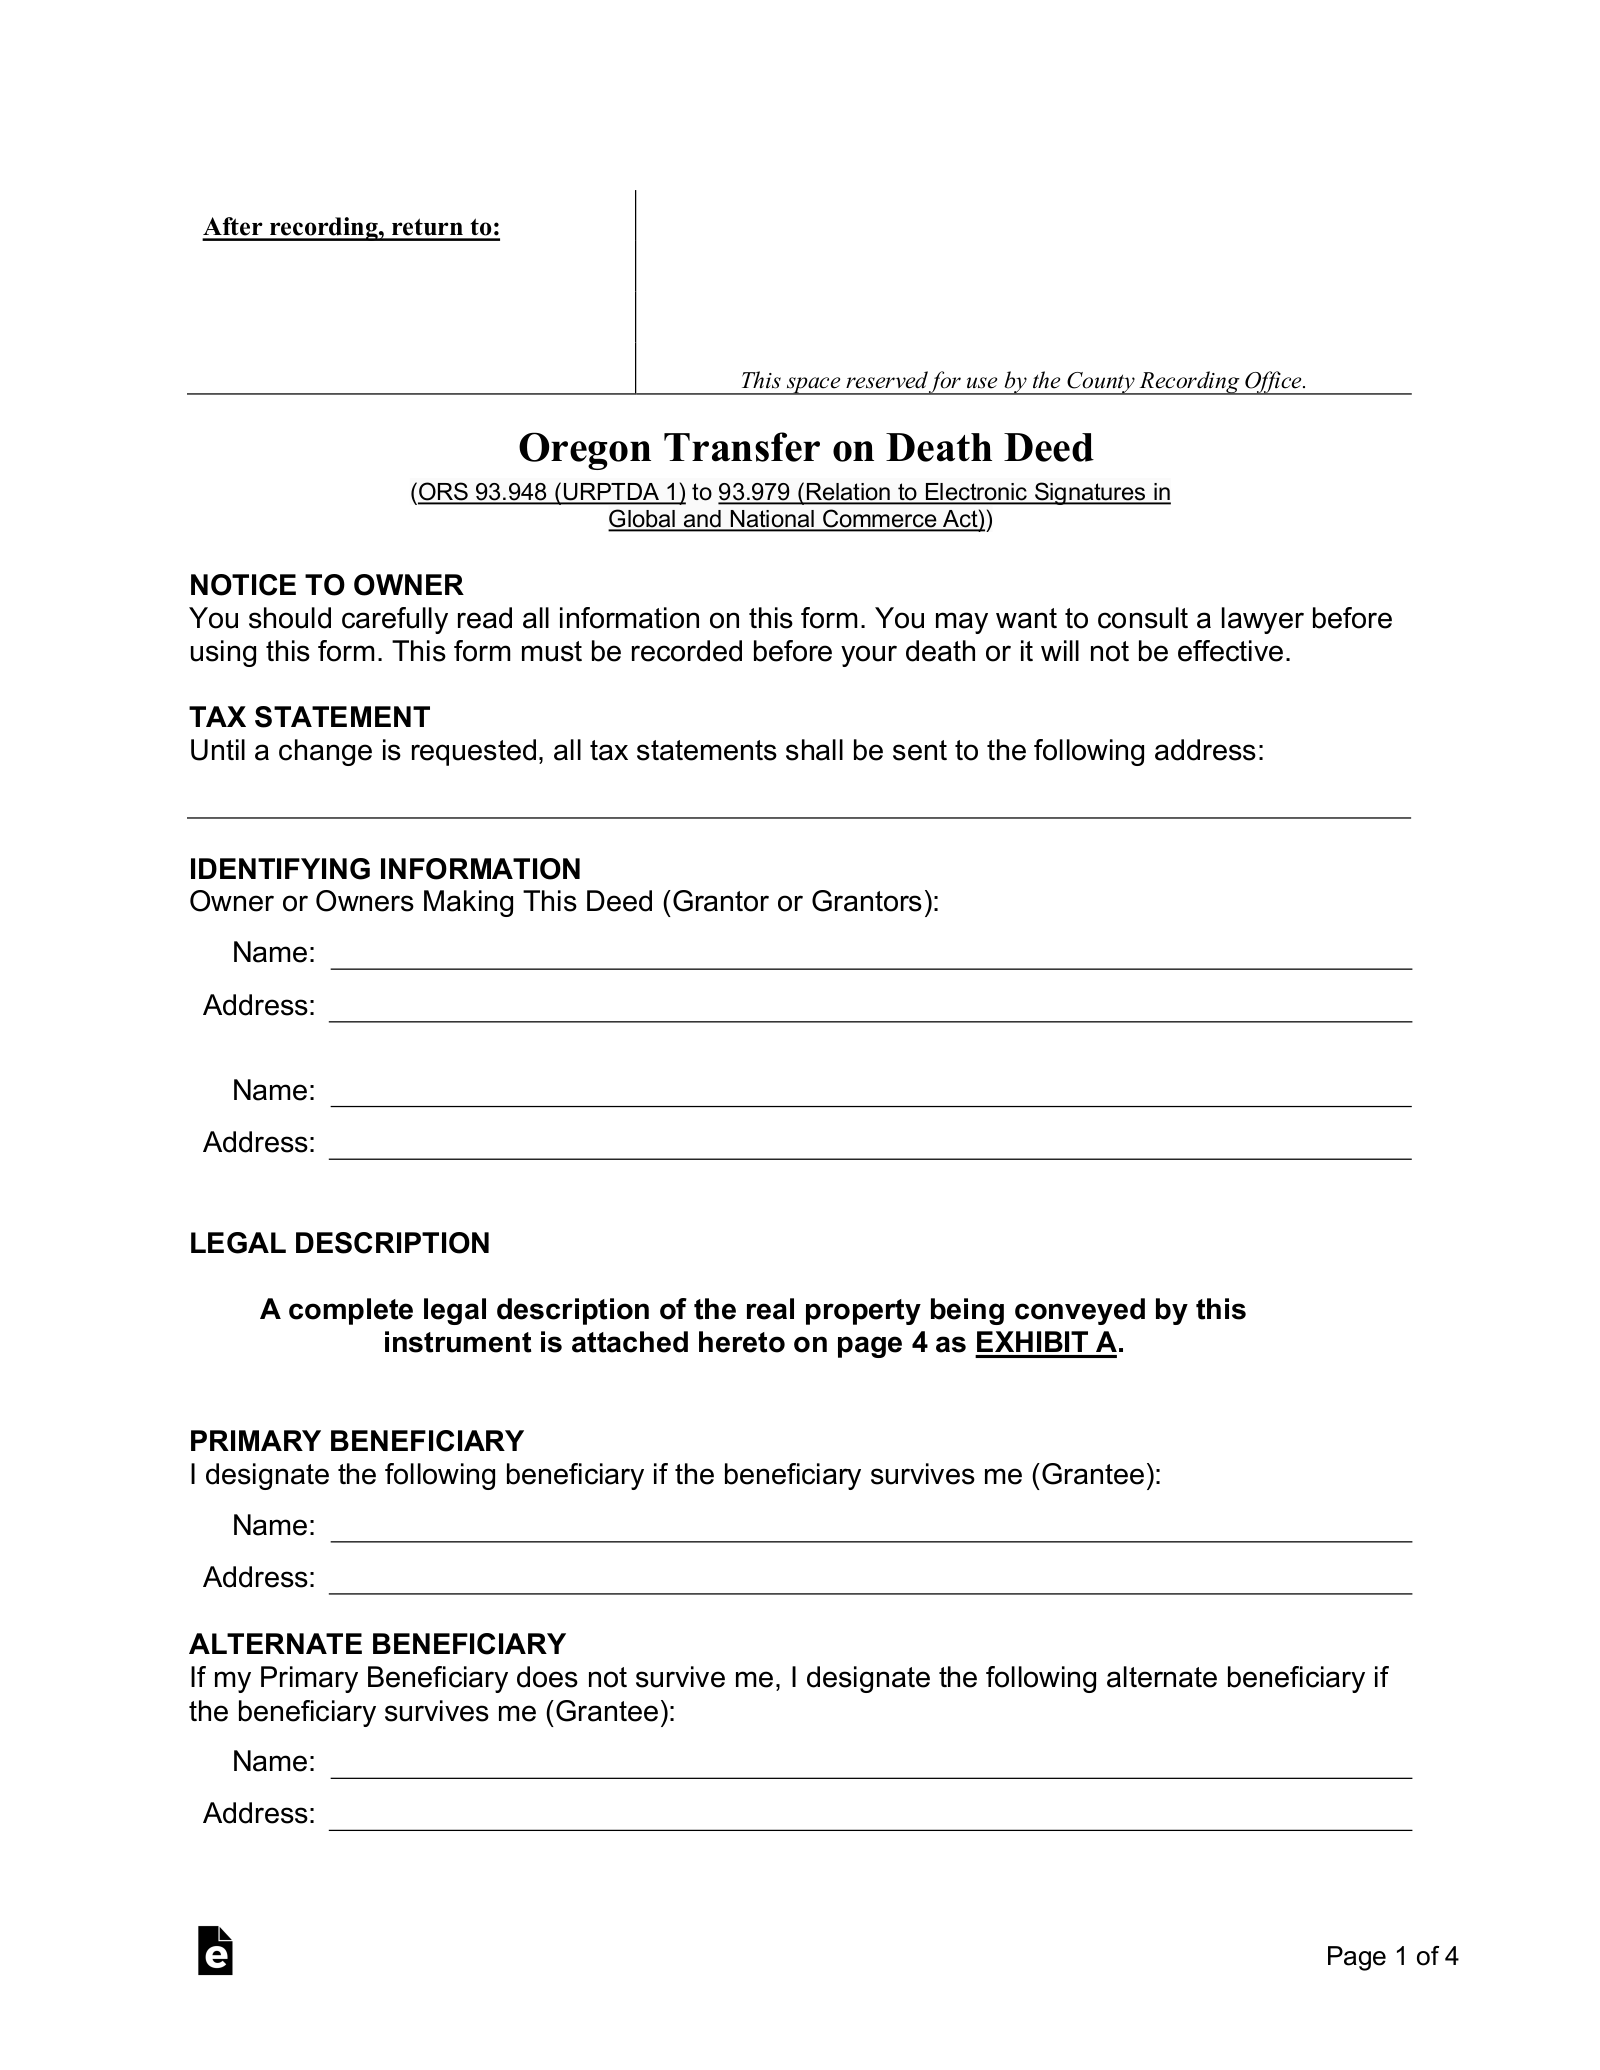
Arizona probate for real estate can be avoided through: - Joint tenancy with right of survivorship (property passes automatically). - Transfer-on-death (TOD) deeds (for residential property). - Living trusts (hold title outside probate). - Beneficiary designations (for investment properties in LLCs). Note: Joint tenancy may have tax implications (e.g., gift tax if unequal contributions are made). Consult an estate attorney to align strategies with net worth property goals.
Q: What’s the most common reason for contested probate in Arizona?
The #1 trigger for contested Arizona probate is disputes over will validity, often tied to: - Undue influence (e.g., a caregiver pressuring a vulnerable testator). - Forgery or coercion in will execution. - Undisclosed assets (e.g., hidden bank accounts or offshore property). In net worth property cases, valuation disputes (e.g., claiming a $3M home is worth $5M) are the second most common source of conflict.
