5 Things Worth Knowing About $1000 Bills and Their Circulation
The story of the $1000 bill isn’t just about its absence from wallets. It’s about why it was created, why it was removed, and why it still matters in ways that go beyond economics. Here’s what you need to know.1. The $1000 bill was never meant to be common currency
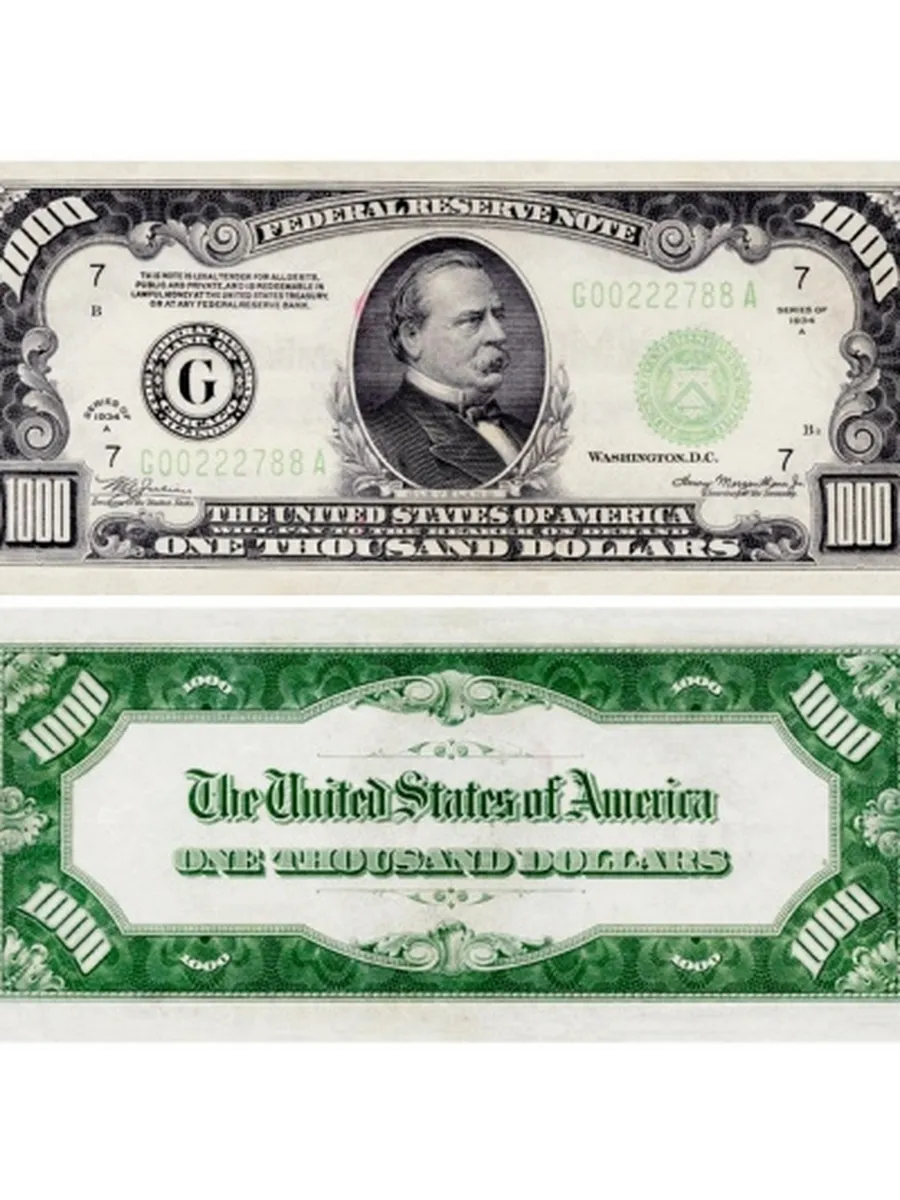
When the $1000 bill was introduced in 1862, it wasn’t designed for everyday use. The U.S. was in the midst of the Civil War, and the government needed a way to finance the conflict without relying solely on coins or smaller denominations. The bill was part of a series of high-denomination notes—$500, $1,000, $5,000, and $10,000—that were intended for large transactions between banks, businesses, and the federal government. These weren’t meant to be carried in pockets; they were tools for institutional finance. By the early 20th century, the role of these bills had shifted slightly. They still weren’t common in retail, but they appeared in high-stakes transactions, such as real estate deals or international trade. The $1000 bill, in particular, became a symbol of wealth and large-scale commerce. Its design—featuring figures like Grover Cleveland, Woodrow Wilson, and eventually Lincoln—reinforced its status as a bill for the elite. The idea that $1000 bills are still in circulation today is less about their everyday use and more about their survival in niche markets where cash still dominates.2. The Federal Reserve stopped printing them in 1946—but didn’t ban them
The official end of $1000 bill production came in 1946, as part of broader efforts to simplify the currency system. The Federal Reserve Act of 1933 had already limited the denominations of new bills to $1, $5, $10, $20, $50, and $100, but existing high-denomination notes remained legal tender. The reasoning was practical: these bills were still in circulation, and removing them entirely would require a massive recall effort that wasn’t deemed necessary. What changed was the production of new ones. The Fed ceased printing $1000 bills, but it didn’t destroy the ones already in existence. This created a gray area: $1000 bills are still in circulation in the sense that they haven’t been formally withdrawn, but their presence in the economy is negligible. The decision reflected a broader trend of reducing cash dependency in favor of checks and electronic transfers—a shift that accelerated in the decades following WWII.3. Most $1000 bills are held by collectors, not spent in transactions
If you’re wondering whether $1000 bills are still in circulation in any meaningful way, the answer lies in two places: private collections and the occasional underground transaction. The vast majority of surviving $1000 bills are not changing hands in everyday commerce. Instead, they’re stored in bank vaults, collected by numismatists, or held by individuals who acquired them decades ago. The market for these bills is small but active. A 1933 $1000 bill, for example, can sell for hundreds of thousands of dollars at auction, not because of its face value but because of its rarity and historical significance. Even the more common series from the 1920s and 1930s can fetch prices well above $1000 for collectors. This dynamic means that while $1000 bills are still in circulation in a technical sense, their movement is more about preservation than utility.4. The black market and conspiracy theories keep the myth alive
One of the reasons the question "Are $1000 bills still in circulation?" persists is the persistent (and largely unfounded) belief that they’re used in illicit transactions. The idea that criminals prefer high-denomination bills isn’t new—it’s a trope that dates back to the Prohibition era and beyond. In reality, the Fed’s own data shows that most large cash transactions today involve smaller denominations bundled together. The $1000 bill is simply too rare to be practical for anything but the most specialized operations. That said, the bill’s association with secrecy and large sums has given rise to conspiracy theories. Some claim that the government secretly prints them for under-the-table deals, while others suggest that they’re used in offshore accounts or by foreign actors. None of these claims hold up under scrutiny, but they contribute to the bill’s mystique. The truth is far less dramatic: $1000 bills are still in circulation in the sense that they haven’t been recalled, but their role in the economy is minimal at best."The $1000 bill is a relic of a time when cash was king in ways it isn’t anymore. It’s not that people are hiding them; it’s that they’re hoarding them—or ignoring them entirely." — Federal Reserve historian, speaking anonymously on the subject.
5. The Fed has no plans to revive the $1000 bill—but it won’t retire them either
The Federal Reserve has been clear: it has no intention of bringing back the $1000 bill. The reasons are practical. High-denomination bills are cumbersome for everyday use, and their absence hasn’t created any significant economic disruptions. The last time the U.S. considered reintroducing them was in the 1990s, when some argued that inflation might necessitate larger denominations—but the idea was quickly dismissed. At the same time, the Fed has no legal mechanism to force the retirement of existing $1000 bills. They remain valid, and banks are required to accept them. However, the likelihood of encountering one in a transaction is vanishingly small. The question "Are $1000 bills still in circulation?" is less about their active use and more about their symbolic existence—a remnant of a financial system that no longer relies on such large cash payments.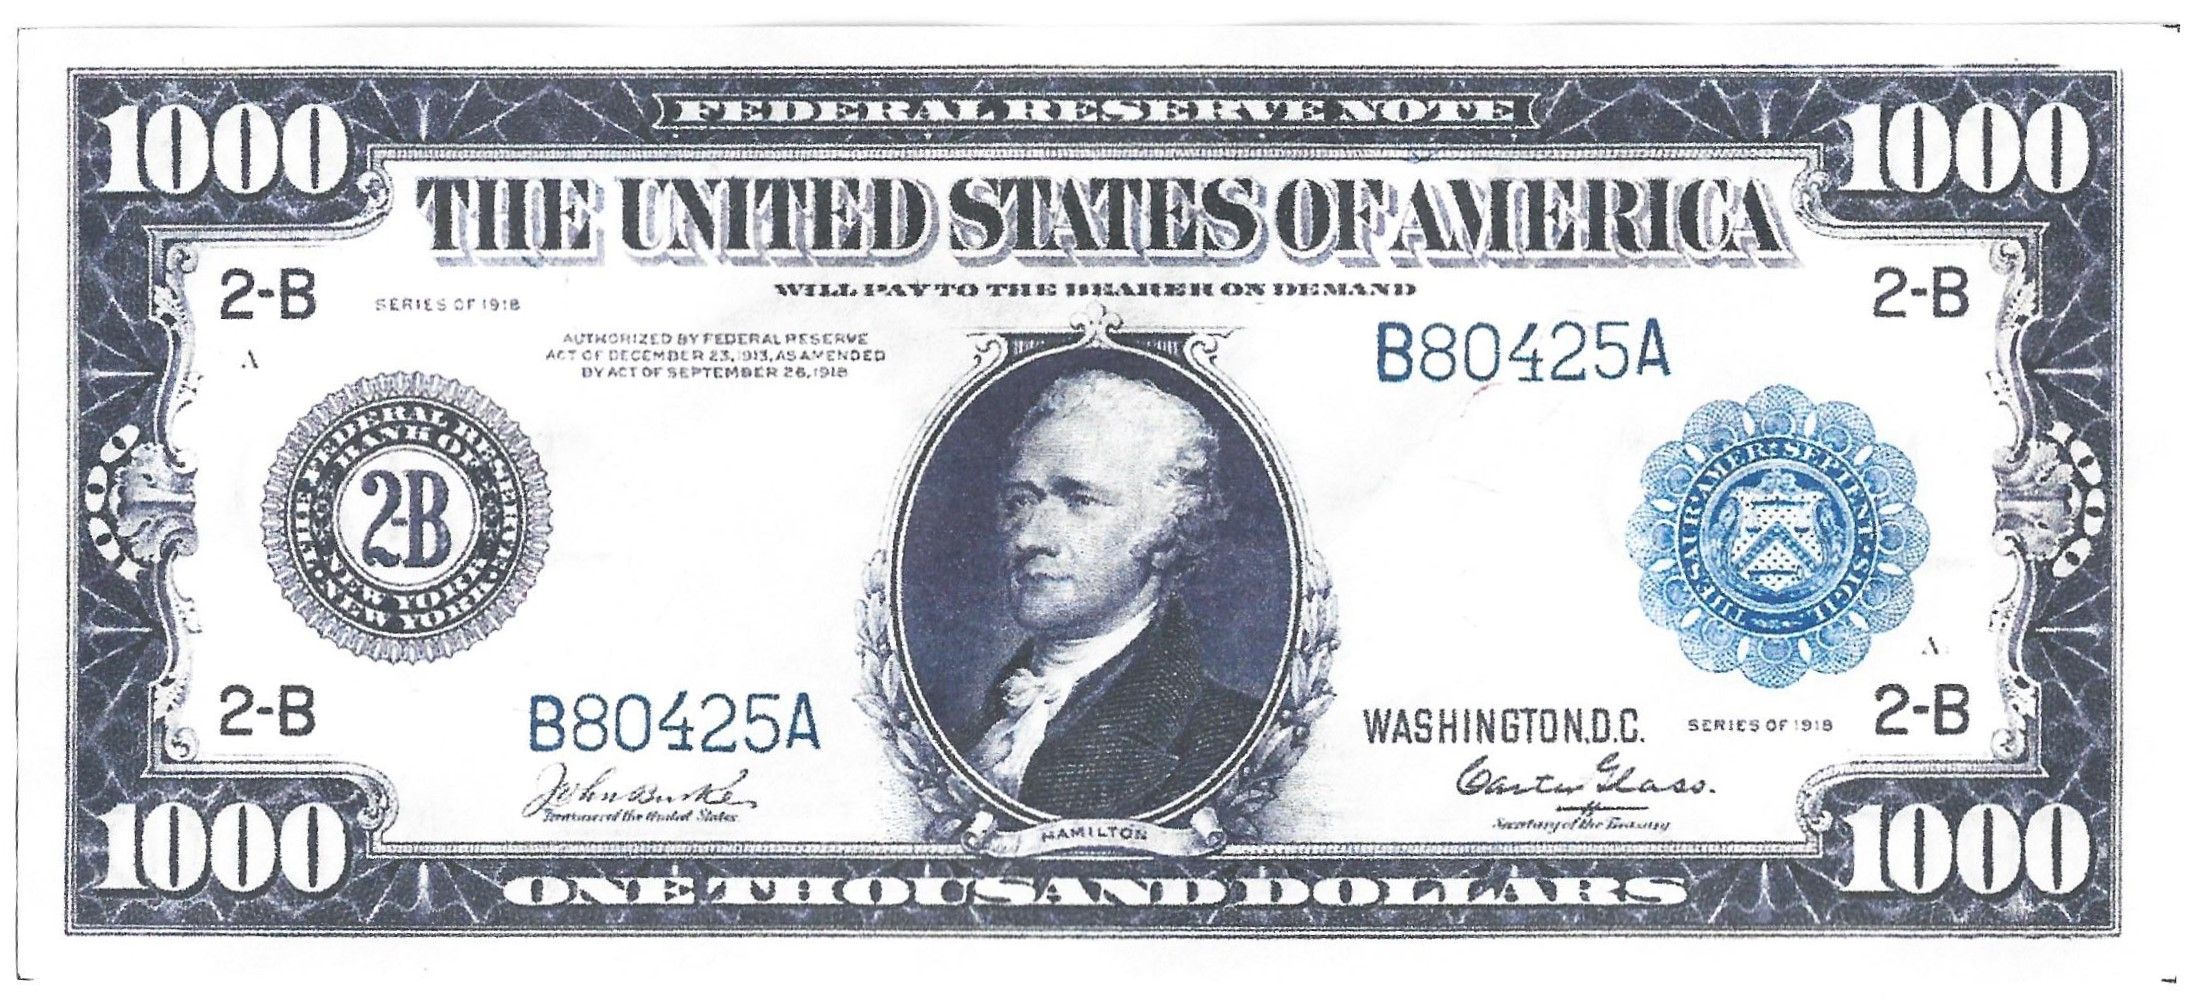
How These Facts Connect
The story of the $1000 bill is one of intentional obscurity. It was never designed for mass circulation, and its withdrawal from production wasn’t about eliminating it entirely but about phasing it out of common use. The fact that $1000 bills are still in circulation today is less about their economic function and more about the inertia of legal tender laws. Once a bill is issued, it remains valid unless explicitly recalled—a principle that applies to $1000 notes just as it does to any other denomination. What’s fascinating is how the bill’s rarity has turned it into a cultural artifact. Collectors, conspiracy theorists, and financial historians all engage with it differently, but their interest stems from the same place: the idea that something so large, so historically significant, could simply disappear from everyday life. The persistence of the question reflects a broader curiosity about money’s role in society—how it’s created, how it’s controlled, and how it’s remembered long after its practical use has faded. | Fact | Why It Matters | Current Reality | Public Perception | |-----------------------------------|-----------------------------------------------------------------------------------|-------------------------------------------------------------------------------------|-----------------------------------------------| | Designed for institutions, not retail | Explains why it was never common currency. | Still legal tender, but not produced since 1946. | Seen as a "banker’s bill." | | Stopped printing in 1946 | Shift toward electronic payments and smaller denominations. | Existing bills remain in circulation, but rarely change hands. | Often assumed to be "gone" or "banned." | | Mostly held by collectors | High value for numismatists, not face value. | Market exists, but transactions are rare. | Myth of criminal use persists. | | Black market myths | Associative link to secrecy and large transactions. | No evidence of widespread illicit use. | Fuel for conspiracy theories. | | No plans to revive | Fed prioritizes practicality over nostalgia. | Will remain valid indefinitely unless recalled. | Seen as a "lost" piece of history. |
Conclusion
The $1000 bill is a perfect example of how money can outlive its usefulness while remaining a subject of fascination. $1000 bills are still in circulation in the sense that they haven’t been formally retired, but their role in the economy is negligible. They’re not disappearing—they’re already gone from most people’s lives, preserved in vaults, collections, and the occasional transaction that no one talks about. What’s left is the myth, the curiosity, and the occasional headline about someone stumbling upon one. The bill’s legacy isn’t in its daily use but in its ability to spark conversations about money, power, and the way financial systems evolve. For now, the $1000 bill remains a footnote—a reminder of a time when cash still carried the weight of empire, and its absence is just as interesting as its presence ever was.Comprehensive FAQs
Q: Can I still spend a $1000 bill at a bank or store?
A: Yes, but it’s highly unlikely you’ll find anyone who accepts one regularly. The Federal Reserve requires banks to accept all legal tender, including $1000 bills, but most businesses and financial institutions don’t handle them. If you try to deposit or spend one, the bank will take it—but they won’t issue new ones in exchange. Think of it as a rare coin rather than cash.
Q: Are $1000 bills used in illegal transactions?
A: There’s no evidence that $1000 bills are commonly used in criminal activity. While high-denomination bills are sometimes associated with secrecy, the Fed’s data shows that most large cash transactions involve smaller bills bundled together. The rarity of $1000 notes makes them impractical for anything but the most specialized operations—and even then, alternatives like digital payments or smaller cash stacks are far more common.
Q: How many $1000 bills are still in existence?
A: The Federal Reserve has never released an exact count, but estimates suggest that fewer than 165,000 $1000 bills remain in circulation as of recent data. Most were issued between 1928 and 1946, and their numbers have dwindled over time due to wear, loss, or destruction. The vast majority are held by collectors, banks, or individuals who acquired them decades ago.
Q: Could the U.S. ever issue $1000 bills again?
A: It’s possible, but highly unlikely. The Federal Reserve has stated no plans to revive the $1000 bill, citing practical concerns like counterfeiting risks and the impracticality of large cash payments in modern economies. Even if inflation made higher denominations necessary, the Fed would likely explore digital solutions before reintroducing physical bills of this size. For now, the $1000 bill remains a historical curiosity rather than a potential return.
Q: What’s the most valuable $1000 bill ever sold?
A: The record for a $1000 bill sold at auction belongs to a 1933 note featuring Grover Cleveland, which fetched over $2 million in 2015. Its value wasn’t due to its face amount but to its rarity, condition, and historical significance. Most $1000 bills from this era sell for far less—often in the hundreds or low thousands—but the top-tier specimens command prices that reflect their status as numismatic treasures rather than currency.
