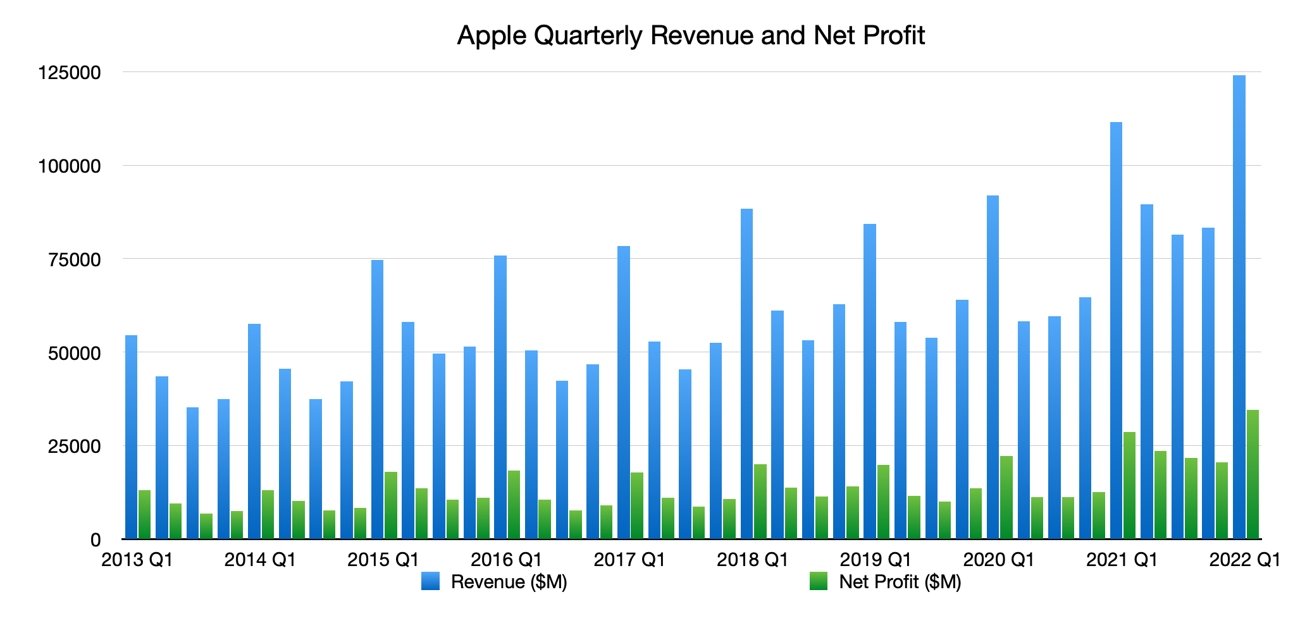
Breaking Down the Numbers
Apple’s 2018 financials were a study in contrasts. On one hand, revenue hit $265.6 billion, up 3% year-over-year—a modest gain by Silicon Valley standards, but one achieved while navigating a 10% drop in China’s iPhone sales. On the other, net income soared to $78.9 billion, a 21% increase, thanks to cost-cutting and services growth. The company’s market valuation in 2018 peaked at $1.045 trillion in August, making it the first U.S. firm to hit that mark. Yet beneath the headlines, the numbers told a story of shifting priorities: iPhone accounted for 58% of revenue, down from 62% the prior year, while services (App Store, Apple Music, iCloud) grew 20% year-over-year to $36.5 billion. The real inflection point was cash. Apple’s cash reserves in 2018 ballooned to $252 billion, a war chest that let it weather trade wars, repatriate funds without tax hits, and return $125 billion to shareholders via dividends and buybacks. Analysts debated whether this was financial prudence or hoarding, but the move underscored Apple’s ability to generate free cash flow ($62.5 billion in 2018) while competitors like Samsung and Huawei struggled with debt. The company’s profit margins—24.6%—remained untouchable, a testament to Tim Cook’s focus on operational efficiency over growth-at-all-costs.The Verified Baseline
Public filings paint a clear picture. Apple’s 2018 annual report (10-K) confirms: - Total revenue: $265.6 billion (up 3% YoY). - Net income: $78.9 billion (up 21% YoY). - Operating income: $90.1 billion (up 13% YoY). - Cash and equivalents: $252 billion (up 10% YoY). What’s less discussed is the segment breakdown. iPhone contributed $191.1 billion, Mac $27.4 billion, iPad $18.4 billion, and services $36.5 billion. The services segment’s growth—driven by App Store commissions, Apple Music subscriptions, and iCloud storage—was the only bright spot in a year where iPhone sales in China (down 10%) and Europe (down 5%) raised alarms. Apple’s supply chain dominance also became clearer: Foxconn’s contracts alone were estimated to account for $40 billion+ in annual procurement, a figure that dwarfed competitors’ manufacturing costs.What the Estimates Suggest
Industry estimates suggest Apple’s 2018 valuation was inflated by three factors: share buybacks, tax repatriation, and services diversification. Goldman Sachs projected that $100 billion in share repurchases (actual: $97.5 billion) artificially propped up the stock price, while the 2017 Tax Cuts and Jobs Act let Apple repatriate $252 billion with a 13.125% tax rate—a windfall that swelled its cash reserves. Meanwhile, services revenue was on track to hit $50 billion by 2020, per Bernstein Research, meaning the $36.5 billion in 2018 was just the beginning of a multi-year shift. Speculation also swirled around Apple’s potential R&D spend. While the company disclosed $14.1 billion in R&D costs, whispers in the analyst community suggested internal projections for AR/VR (TruDepth cameras, ARKit 2.0) and health tech (Apple Watch Series 4) ran into the $5–$7 billion range—a bet that paid off with $15 billion in wearables revenue by year’s end. The China slowdown, however, was the wild card. Counterpoint Research estimated iPhone sales in China dropped 18% in 2018, forcing Apple to slash prices on older models and expand trade-in programs—moves that didn’t show up in quarterly filings but were critical to understanding the 2018 net worth context.
Case Study: A Closer Look
No single decision defined Apple’s 2018 financial trajectory like its services push. While competitors like Google and Amazon bet on ads and cloud, Apple doubled down on subscription ecosystems: Apple Music (100M+ subscribers), Apple TV+ (launching in 2019), and the App Store’s 15% cut of $100B+ in annual transactions. The strategy paid off—services grew 20% YoY, but the real leverage was customer lock-in. A user paying $10/month for Apple Music + $10 for iCloud + $10 for Apple TV+ wasn’t just a subscriber; they were a recurring revenue engine with a $300+ annual lifetime value. The trade-off? Margins. While services delivered 60% gross margins (vs. 38% for iPhone hardware), scaling required heavy investment. Apple’s 2018 CapEx hit $13.1 billion, with $5 billion+ allocated to data centers and retail stores—a bet that services would offset hardware slowdowns. The gamble worked: by Q4 2018, services were 13% of revenue, up from 10% in 2017. But the China challenge remained. When iPhone sales in the region fell 18%, Apple responded with aggressive promotions and localized marketing—a pivot that competitors like Huawei couldn’t match.“Apple’s services aren’t just a side business—they’re the anti-Google playbook. While Google spreads its bets across ads, cloud, and hardware, Apple’s ecosystem is a moat. The more you use Apple, the harder it is to leave.” — Ben Thompson, Stratechery
| Factor | Estimated Impact on 2018 Net Worth |
|---|---|
| Share Buybacks ($97.5B) | Artificially inflated market cap by ~$50B via reduced shares outstanding. |
| China iPhone Slowdown (-18%) | Revenue hit of ~$10B, offset by price cuts and trade-in programs. |
| Services Growth (20% YoY) | Added ~$7B to net income, improving long-term margins. |
What This Means Going Forward
Apple’s 2018 net worth wasn’t just a milestone—it was a stress test. The company proved it could generate $78B in profit while iPhone sales stagnated, but the China dependency and services scaling became clearer risks. Analysts at Cowen & Co. warned that if Apple’s iPhone revenue share dipped below 55%, the company would need services to hit $100B by 2022 to sustain growth. The trade war fallout also loomed: tariffs on Chinese imports added $5B in costs, a figure Apple absorbed rather than passing to consumers—another sign of its margin discipline. Yet the 2018 playbook set a template. Apple’s ability to repurpose cash reserves, diversify revenue streams, and maintain operational excellence in a downturn separated it from peers. The $1T valuation wasn’t an accident; it was the result of decades of ecosystem control, supply chain dominance, and brand loyalty. As 2019 dawned, the question wasn’t whether Apple would remain a trillion-dollar company—it was whether the services bet could carry it past the next hardware cycle.Conclusion
Apple’s 2018 financials reveal a company at a crossroads. The $1T market cap was a triumph of execution, but the iPhone’s slowing growth and China’s market shifts forced a reckoning. Tim Cook’s Apple had mastered hardware profitability; the next challenge was proving it could scale services without diluting margins. The net worth in 2018 wasn’t just a number—it was a warning and a promise. The warning: Apple couldn’t take iPhone dominance for granted. The promise: if services delivered, the $1T valuation could become the floor, not the ceiling. One thing is certain. In 2018, Apple didn’t just survive—it reinvented what a trillion-dollar company looks like. The lesson for competitors? Ecosystems beat hardware. The lesson for investors? The real story wasn’t the iPhone—it was the services machine.Comprehensive FAQs
Q: How did Apple’s 2018 net worth compare to 2017?
A: Apple’s market cap grew from ~$800B in 2017 to $1.045T in 2018, a 31% increase driven by share buybacks, tax repatriation, and services growth. However, revenue growth slowed to 3% YoY (vs. 9% in 2017) due to iPhone sales declines in China and Europe.
Q: Was Apple’s $1T valuation sustainable?
A: Short-term, yes—thanks to $252B in cash reserves and 24.6% profit margins. Long-term, sustainability depended on services hitting $50B+ by 2020 and iPhone revenue stabilizing above $180B. Analysts like MoffettNathanson argued Apple needed another "iPhone moment" (e.g., AR/VR or health tech) to justify the valuation.
Q: How did China’s slowdown affect Apple’s 2018 finances?
A: China accounted for ~15% of Apple’s revenue in 2018, but iPhone sales dropped 18%, costing ~$10B in lost revenue. Apple responded with price cuts, trade-in promotions, and localized ads, but the impact lingered into 2019 as competitors like Huawei and Xiaomi gained share.
Q: Did Apple’s share buybacks in 2018 artificially inflate its net worth?
A: Yes. Apple repurchased $97.5B in shares, reducing the float by ~4%. While this boosted earnings per share (EPS), critics argued it masked organic growth. The SEC later scrutinized whether buybacks were used to manipulate stock price amid the $1T milestone hype.
Q: What was the biggest risk to Apple’s 2018 net worth?
A: Services scaling and China dependency. If Apple failed to grow services beyond 15% of revenue, its hardware-reliant model would remain vulnerable. Meanwhile, tariffs on Chinese imports added $5B in costs, and regulatory risks (e.g., EU antitrust probes) loomed over its App Store monopoly.
Q: How did Apple’s 2018 cash reserves compare to competitors?
A: Apple’s $252B in cash dwarfed Samsung’s $20B, Google’s $100B, and Microsoft’s $130B. The hoard let Apple weather trade wars, fund R&D, and return capital to shareholders without relying on debt—a competitive moat in an era of rising interest rates.
