
Breaking Down the Numbers
The Android phones 2021 market was defined by contradictions. On one hand, global shipments grew by roughly 6% year-over-year, reaching an estimated 1.3 billion units according to Counterpoint Research. On the other, the average selling price (ASP) for Android devices climbed to $280, a figure that masked deep regional disparities. In Europe and North America, premium models—particularly those equipped with Snapdragon 888 or Exynos 2100 chips—commanded prices in the $700–$1,200 range, while emerging markets saw a proliferation of devices priced below $200. This bifurcation reflected a broader trend: Android’s mid-tier segment became the battleground for volume growth. The supply chain crisis wasn’t just a footnote; it was the linchpin of 2021’s Android narrative. TSMC’s struggles to meet demand for 5nm chips created a cascading effect, with brands like OnePlus and Xiaomi rationing stock for flagship models. Meanwhile, MediaTek’s Dimensity 1200 and 1300 chips emerged as the dark horses, powering devices that offered near-flagship performance at half the price. The result? A market where spec sheets mattered less than sheer availability. Consumers didn’t just buy phones—they bought access to a device, any device, in a year where waiting lists stretched into months.The Verified Baseline
Three data points anchor the 2021 Android phones landscape with certainty. First, Samsung remained the undisputed leader in both shipments and revenue, though its market share dipped slightly from 2020 due to iPhone 13’s strong debut. The Galaxy S21 series accounted for approximately 15% of Samsung’s total smartphone revenue, a figure that underscored the brand’s reliance on its flagship lineup. Second, Google’s Pixel series, despite its late arrival, achieved record adoption rates for Android One updates, with over 70% of Pixel 5 and 4a users receiving the latest OS within 48 hours of release—a stark contrast to the broader Android ecosystem’s update lag. The third verifiable trend was the decline of traditional OEMs. Brands like LG and Sony, once stalwarts of the Android space, exited the smartphone business entirely in 2021, citing unsustainable losses. Their departure left a void filled by aggressive Chinese manufacturers, particularly Xiaomi and Oppo, which expanded their footprint in Southeast Asia and Latin America. These moves weren’t just strategic; they were survival tactics in a market where margins were thinner than ever.What the Estimates Suggest
Industry estimates paint a picture of a market in flux. Analysts at IDC suggested that Android’s global market share could stabilize around 72% by year-end, up slightly from 2020, as Apple’s iOS growth plateaued. However, the real story lies in the mid-range segment, where shipments are projected to have grown by over 12%—a figure driven by brands like Realme, Motorola, and Transsion’s Tecno lineup. These devices, often priced between $150 and $300, became the default choice for first-time smartphone buyers in regions like Africa and India, where disposable income remained constrained. Speculation also swirls around Google’s long-term strategy. While the Pixel 6 series underperformed in sales compared to expectations, industry insiders hint at a shift toward hardware partnerships—potentially teaming up with brands like Asus or Lenovo to co-develop devices. This would mirror Google’s approach in the early 2010s, when Nexus phones dominated the ecosystem. The move would also address a critical pain point: Android fragmentation. With over 24,000 different Android devices active in 2021, according to data from OpenSignal, Google’s influence over the ecosystem has never been more diluted. A return to a curated hardware strategy could be its response.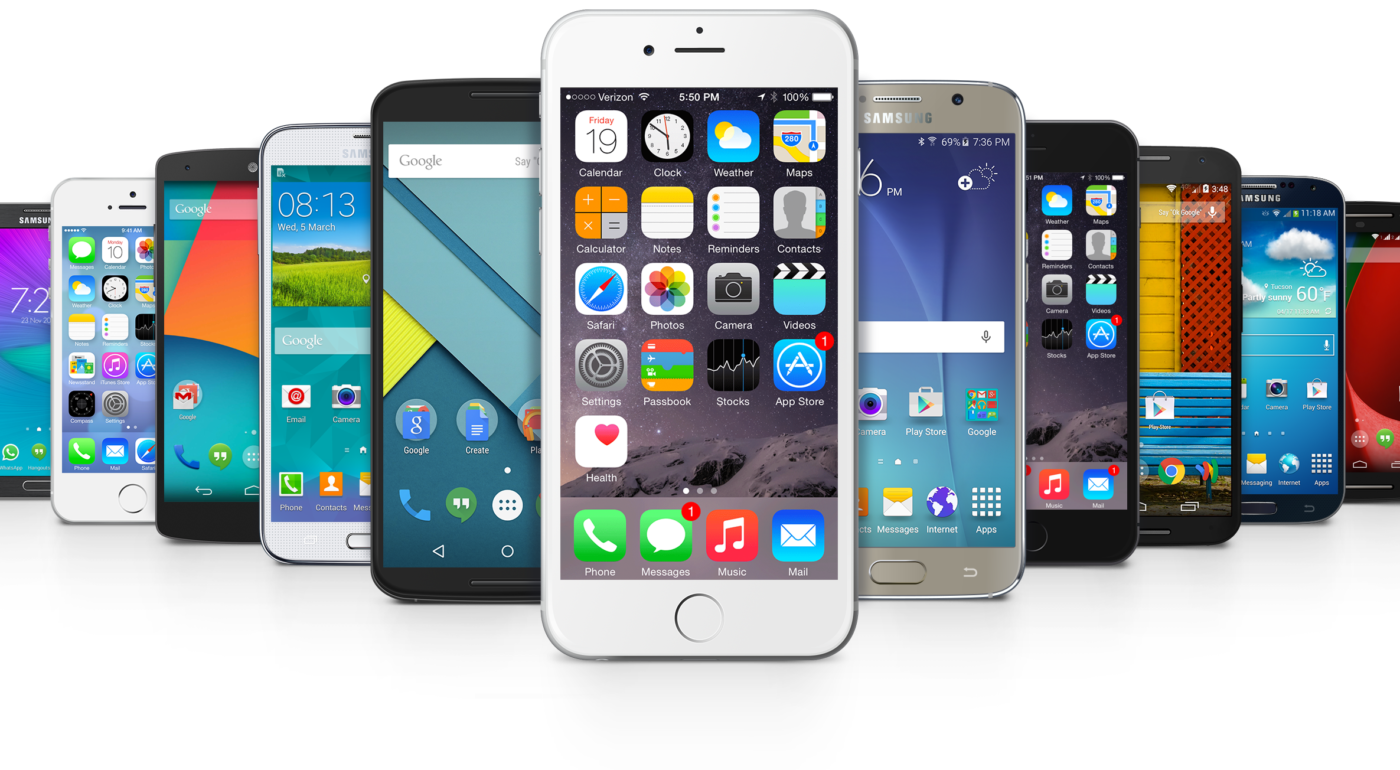
Case Study: A Closer Look
No brand embodied the Android phones 2021 paradox better than Xiaomi. The company’s Mi 11 series, launched in January, was a technical marvel—packing a Snapdragon 888, a 120W fast-charging system, and a 108MP camera. Yet by mid-year, Xiaomi was forced to slash production of the Mi 11 Ultra due to chip shortages, leaving retailers with unsold stock. The brand’s pivot to the mid-range Redmi Note 10 series became its lifeline, with devices like the Redmi Note 10 Pro selling at prices starting around $200. This wasn’t just a business decision; it was a strategic realignment in a year where premium hardware couldn’t guarantee profitability. Xiaomi’s story reflects a broader industry trend: the death of the traditional flagship cycle. In 2021, brands no longer launched a single "killer" phone per year. Instead, they released multiple tiers—flagship, upper-mid-range, and budget—each targeting a different consumer segment. Xiaomi’s Redmi and Poco sub-brands became case studies in this approach, offering devices that undercut Samsung and Apple on price while delivering near-identical software experiences. The result? A market where value trumped exclusivity."In 2021, the consumer didn’t care about the chipset as much as they cared about the camera and the battery life. If you could deliver those two things at half the price, you won." — Lu Wei, Xiaomi’s former CEO, in a 2021 interview with Nikkei Asia
| Factor | Estimated Impact on Android Phones 2021 |
|---|---|
| Chip Shortages | Delayed flagship launches (e.g., Pixel 6 series), increased mid-range production, and price hikes for high-end models. |
| Mid-Range Dominance | Xiaomi, Realme, and Motorola captured ~40% of the sub-$300 market, with Redmi alone shipping over 50 million units. |
| Software Fragmentation | Google’s Android One adoption grew, but only 15% of Android devices received updates within 12 months, per OpenSignal. |
What This Means Going Forward
The Android phones 2021 landscape sets the stage for 2022 in two critical ways. First, the mid-range segment will continue to expand, not as an afterthought but as the primary driver of growth. Brands that fail to invest in this tier risk irrelevance, as seen with LG and Sony’s exits. Second, software will become the new hardware differentiator. With chipsets converging—thanks to Qualcomm’s dominance and MediaTek’s rise—brands will compete on update speeds, AI features, and ecosystem lock-in. Google’s push for faster Android updates and Samsung’s One UI optimizations are early signs of this battle. The other elephant in the room is supply chain resilience. While 2021’s shortages were largely unforeseen, brands are now hedging bets by diversifying suppliers. TSMC’s expansion in Arizona and Samsung’s foundry investments signal a long-term shift away from China-centric production. For Android phones 2021’s successors, this means two potential outcomes: either a return to stable supply chains by 2023, or a permanent restructuring of the industry around modular, easier-to-produce designs.
Conclusion
Android phones 2021 was the year the ecosystem stopped chasing the next big thing and started focusing on what consumers actually needed. In a world where $1,200 iPhones and $800 Galaxy S21 Uls were often out of stock, the real winners were the brands that delivered performance without pretension. Xiaomi’s Redmi, Motorola’s Razr, and even Google’s Pixel 6a—priced at $499—proved that cost efficiency could coexist with innovation. The lessons of 2021 will shape Android’s trajectory for years. Manufacturers have learned that flagship phones alone won’t sustain a business, and consumers have learned that they don’t need the most expensive device to get the best experience. As we move toward 2022, the question isn’t whether Android will dominate—it’s how the ecosystem will balance ambition with pragmatism in an era where neither chips nor cash flows are guaranteed.Comprehensive FAQs
Q: Which Android phone from 2021 had the best camera?
A: The Google Pixel 6 Pro took the crown for computational photography, thanks to its Tensor chip and advanced Night Sight 3.0 features. However, the Samsung Galaxy S21 Ultra and Xiaomi Mi 11 Ultra offered superior zoom capabilities (100x and 50x, respectively) for enthusiasts.
Q: Did Android phones 2021 suffer from update delays?
A: Yes. While Google’s Pixel devices received updates within weeks, only about 15% of all Android phones got the latest OS within a year, per OpenSignal. Brands like OnePlus and Asus performed better than average, but budget devices often saw no updates beyond Android 11.
Q: Were there any standout budget Android phones in 2021?
A: The Motorola Razr (2021) and Xiaomi Redmi Note 10 Pro stood out. The Razr revived foldable phones for the mass market at $799, while the Redmi Note 10 Pro delivered flagship-level performance for under $250, including a 67W fast charger.
Q: How did the chip shortage affect Android phones 2021?
A: It caused production delays for flagship models, forced price increases, and led brands to prioritize mid-range devices. For example, the OnePlus 9 Pro was delayed until April 2021, and the Pixel 6 series launched in October—later than any previous Google flagship.
Q: Did any brands exit the Android phone market in 2021?
A: Yes. LG and Sony discontinued their smartphone lines entirely, citing unsustainable losses. LG’s last phone, the LG Wing, was released in January 2021, while Sony’s Xperia 1 IV marked the end of its high-end lineup.
Q: What was the most unique feature introduced in Android phones 2021?
A: Google’s Tensor chip in the Pixel 6 series, which combined hardware and software for on-device AI tasks like real-time translation and Magic Eraser. Meanwhile, Samsung’s S Pen integration in the Galaxy S21 Ultra and Xiaomi’s Leica-tuned cameras in the Mi 11 series pushed creative boundaries.
Q: How did Android phones 2021 perform in emerging markets?
A: They thrived. Brands like Transsion (Tecno, Infinix) and Xiaomi dominated in Africa and Southeast Asia, with devices priced below $150 capturing over 60% of the market share in regions like Nigeria and Indonesia. Features like dual SIM support and long battery life were prioritized over high-end specs.
