Common Myths About American Airlines’ Financial Standing
The first misconception is that American airline net worth can be gauged solely by its stock performance. While the ticker (AAL) is a visible barometer, it’s a snapshot of investor sentiment, not the full ledger. The airline’s enterprise value—market cap plus debt minus cash—often exceeds $50 billion, but this figure ignores the time-value of assets like aircraft or the deferred costs of union contracts. A second myth frames American as perpetually "broke," a narrative fueled by headlines about quarterly losses or restructuring charges. Yet the airline’s core profitability (excluding one-time items) has been resilient, thanks to its hub-and-spoke dominance and alliances like Oneworld. The confusion stems from conflating operational cash flow with net income, or ignoring how American’s scale mitigates risks that smaller carriers face. Another persistent myth is that American’s net worth is propped up by government bailouts—a remnant of the 2020 COVID-19 aid packages. While the airline did receive $5.8 billion in Payroll Support Program funds, this was repaid in full by 2022, and the company’s subsequent bond issuances (including a $1.25 billion deal in 2023) reflect its ability to access capital on its own terms. The real leverage lies in asset monetization: American’s fleet modernization strategy, which includes orders for 600+ Airbus and Boeing planes, isn’t just a growth play—it’s a way to revalue its balance sheet by replacing older, less efficient aircraft. Yet outsiders often overlook how these long-term investments defer immediate profitability, creating a lag between spending and perceived net worth.Myth 1: American Airlines is "overleveraged" because of its debt
The narrative that American’s debt-to-equity ratio is unsustainable ignores how aviation finance works. Airlines typically carry higher debt loads than other industries because aircraft are capital-intensive assets that depreciate rapidly. As of late 2023, American’s net debt (total debt minus cash) was reported around $30 billion, but this figure must be contextualized: roughly half of that was tied to aircraft leases or operating leases, which are often off-balance-sheet in accounting treatments. More critically, the airline’s interest coverage ratio—a measure of debt servicing ability—has remained stable, thanks to fixed-rate debt instruments and hedging strategies. The real test isn’t whether American can service debt, but whether its revenue streams (like premium cabin growth or cargo) can outpace interest costs over time. What’s often missed is that American airline net worth isn’t just about debt levels but debt structure. The airline has aggressively refinanced short-term borrowings into longer-term bonds, reducing refinancing risk. Its 2023 bond offerings, for example, included 10-year notes at yields below 5%, a sign of investor confidence in its ability to generate free cash flow. The leverage ratio alone tells an incomplete story; the airline’s operating leverage—its ability to spread fixed costs over a large volume of passengers—is what truly underpins its financial resilience. Yet headlines about debt ratios persist because they’re easier to cite than the nuanced metrics that matter.Myth 2: The airline’s net worth is declining because of labor costs
Labor expenses are indeed a major line item, but framing them as the sole driver of declining net worth oversimplifies the picture. American’s workforce-related costs (including pensions and healthcare) have been rising, but so have productivity gains from automation and route optimization. The airline’s unit labor cost—a key metric—has remained competitive within the industry, partly due to its union contracts being less generous than those at legacy competitors like Delta or United. The bigger issue isn’t labor costs per se, but the mismatch between wage increases and revenue growth. When fuel prices spike, as they did in 2022, labor costs become a smaller percentage of total expenses, offsetting some of the perceived pressure. The confusion arises from conflating operating income with net worth. Even if labor costs rise, American’s ability to pass through higher fares (thanks to its dominant hubs in Dallas, Chicago, and Miami) can absorb some of the impact. The airline’s pre-tax margin has fluctuated between 12% and 18% in recent years, a range that suggests it’s managing costs better than many assume. The real vulnerability isn’t labor costs alone, but the interaction between labor, fuel, and capacity discipline. When American cuts unprofitable routes or adjusts schedules dynamically, it’s not just reacting to labor pressures—it’s recalibrating its entire network to protect net worth.Myth 3: American’s net worth is tied to its loyalty program
The AAdvantage program is a crown jewel, but its contribution to American airline net worth is often exaggerated. While the program drives ancillary revenue (through fees for upgrades, checked bags, and elite benefits), its direct impact on the balance sheet is indirect. The value of AAdvantage isn’t in its assets (which are minimal) but in its customer lifetime value: frequent flyers who spend more on tickets, hotels, and partnerships. The program’s true worth lies in its network effects—the more members it has, the more valuable it becomes to partners like Marriott or Hertz. Yet this intangible asset isn’t reflected in traditional net worth calculations, leading to an overemphasis on its perceived financial importance. What’s often overlooked is that American’s net worth is more directly tied to its physical assets: the fleet, gates, and real estate. The airline’s decision to lease rather than own aircraft, for instance, reduces capital expenditures but also means it doesn’t fully capture the appreciation (or depreciation) of planes on its books. Similarly, its slot portfolio at major airports—like its 40% share at New York’s LaGuardia—is a non-financial asset that generates revenue but isn’t quantified in standard net worth metrics. The loyalty program is a multiplier, but the base value comes from the airline’s core operations.
What Holds Up to Scrutiny
At its core, American airline net worth is a function of three verifiable pillars: asset base, revenue quality, and cost structure. The airline’s fleet, valued at over $60 billion in gross book value, is its largest tangible asset, though its net carrying value is lower due to depreciation. Revenue quality—measured by yield (average fare per mile) and load factor (seat occupancy)—has been strong, with American consistently ranking among the top U.S. carriers in both metrics. Its cost structure, while high in absolute terms, is efficient relative to peers, thanks to scale economies and vertical integration (e.g., owning its own maintenance operations). These factors don’t guarantee profitability, but they do provide a foundation for resilient net worth in a cyclical industry. The airline’s ability to monetize intangibles is another often-underappreciated strength. Its brand equity, route network, and alliances (like Oneworld) create barriers to entry that smaller carriers can’t replicate. For example, American’s partnership with British Airways and Japan Airlines opens up premium transatlantic and Asia-Pacific markets, generating revenue that wouldn’t exist in a standalone operation. These strategic assets aren’t reflected in traditional net worth calculations, but they’re critical to understanding why American can sustain higher valuations than competitors with similar balance sheets."American’s net worth isn’t just a number—it’s a reflection of its ability to balance legacy obligations with future growth. The airline’s strength lies in its dual role as both a mature, cash-generative business and a dynamic player in an industry undergoing rapid transformation." — Industry analyst, 2023
| Common Belief | What the Evidence Says |
|---|---|
| American’s debt is unsustainable. | Debt levels are typical for airlines; interest coverage ratios remain stable, and refinancing risks are mitigated by long-term bonds. |
| Labor costs are dragging down net worth. | Unit labor costs are competitive; the bigger risk is revenue growth keeping pace with wage increases. |
| The loyalty program is the main driver of value. | Program value is ancillary; core net worth depends on fleet, routes, and cost discipline. |
| American’s net worth is volatile because of fuel prices. | Fuel hedging and dynamic pricing soften the impact; the airline’s scale provides insulation against price spikes. |
Why the Confusion Persists
The opacity around American airline net worth stems from two industry-specific challenges: accounting complexity and sectoral volatility. Aviation finance is governed by rules that differ from corporate standards—aircraft leases, for example, can be treated as operating expenses rather than debt, distorting leverage metrics. Additionally, the industry’s cyclicality means that what appears as a liability in downturns (like high debt) can become an asset in recoveries (as fixed costs are spread over higher passenger volumes). This push-pull dynamic makes it difficult for outsiders to pin down a "true" net worth, as the figure is always in flux. Another factor is the information asymmetry between insiders and observers. American’s leadership and investors have access to granular data on route profitability, fuel hedges, and labor negotiations that aren’t public. Meanwhile, analysts rely on quarterly filings and stock price movements, which are lagging indicators. The result is a feedback loop: headlines about debt or losses become self-fulfilling prophecies, influencing investor behavior and, in turn, shaping the airline’s ability to raise capital. This cycle reinforces the perception of instability, even when the underlying fundamentals are sound.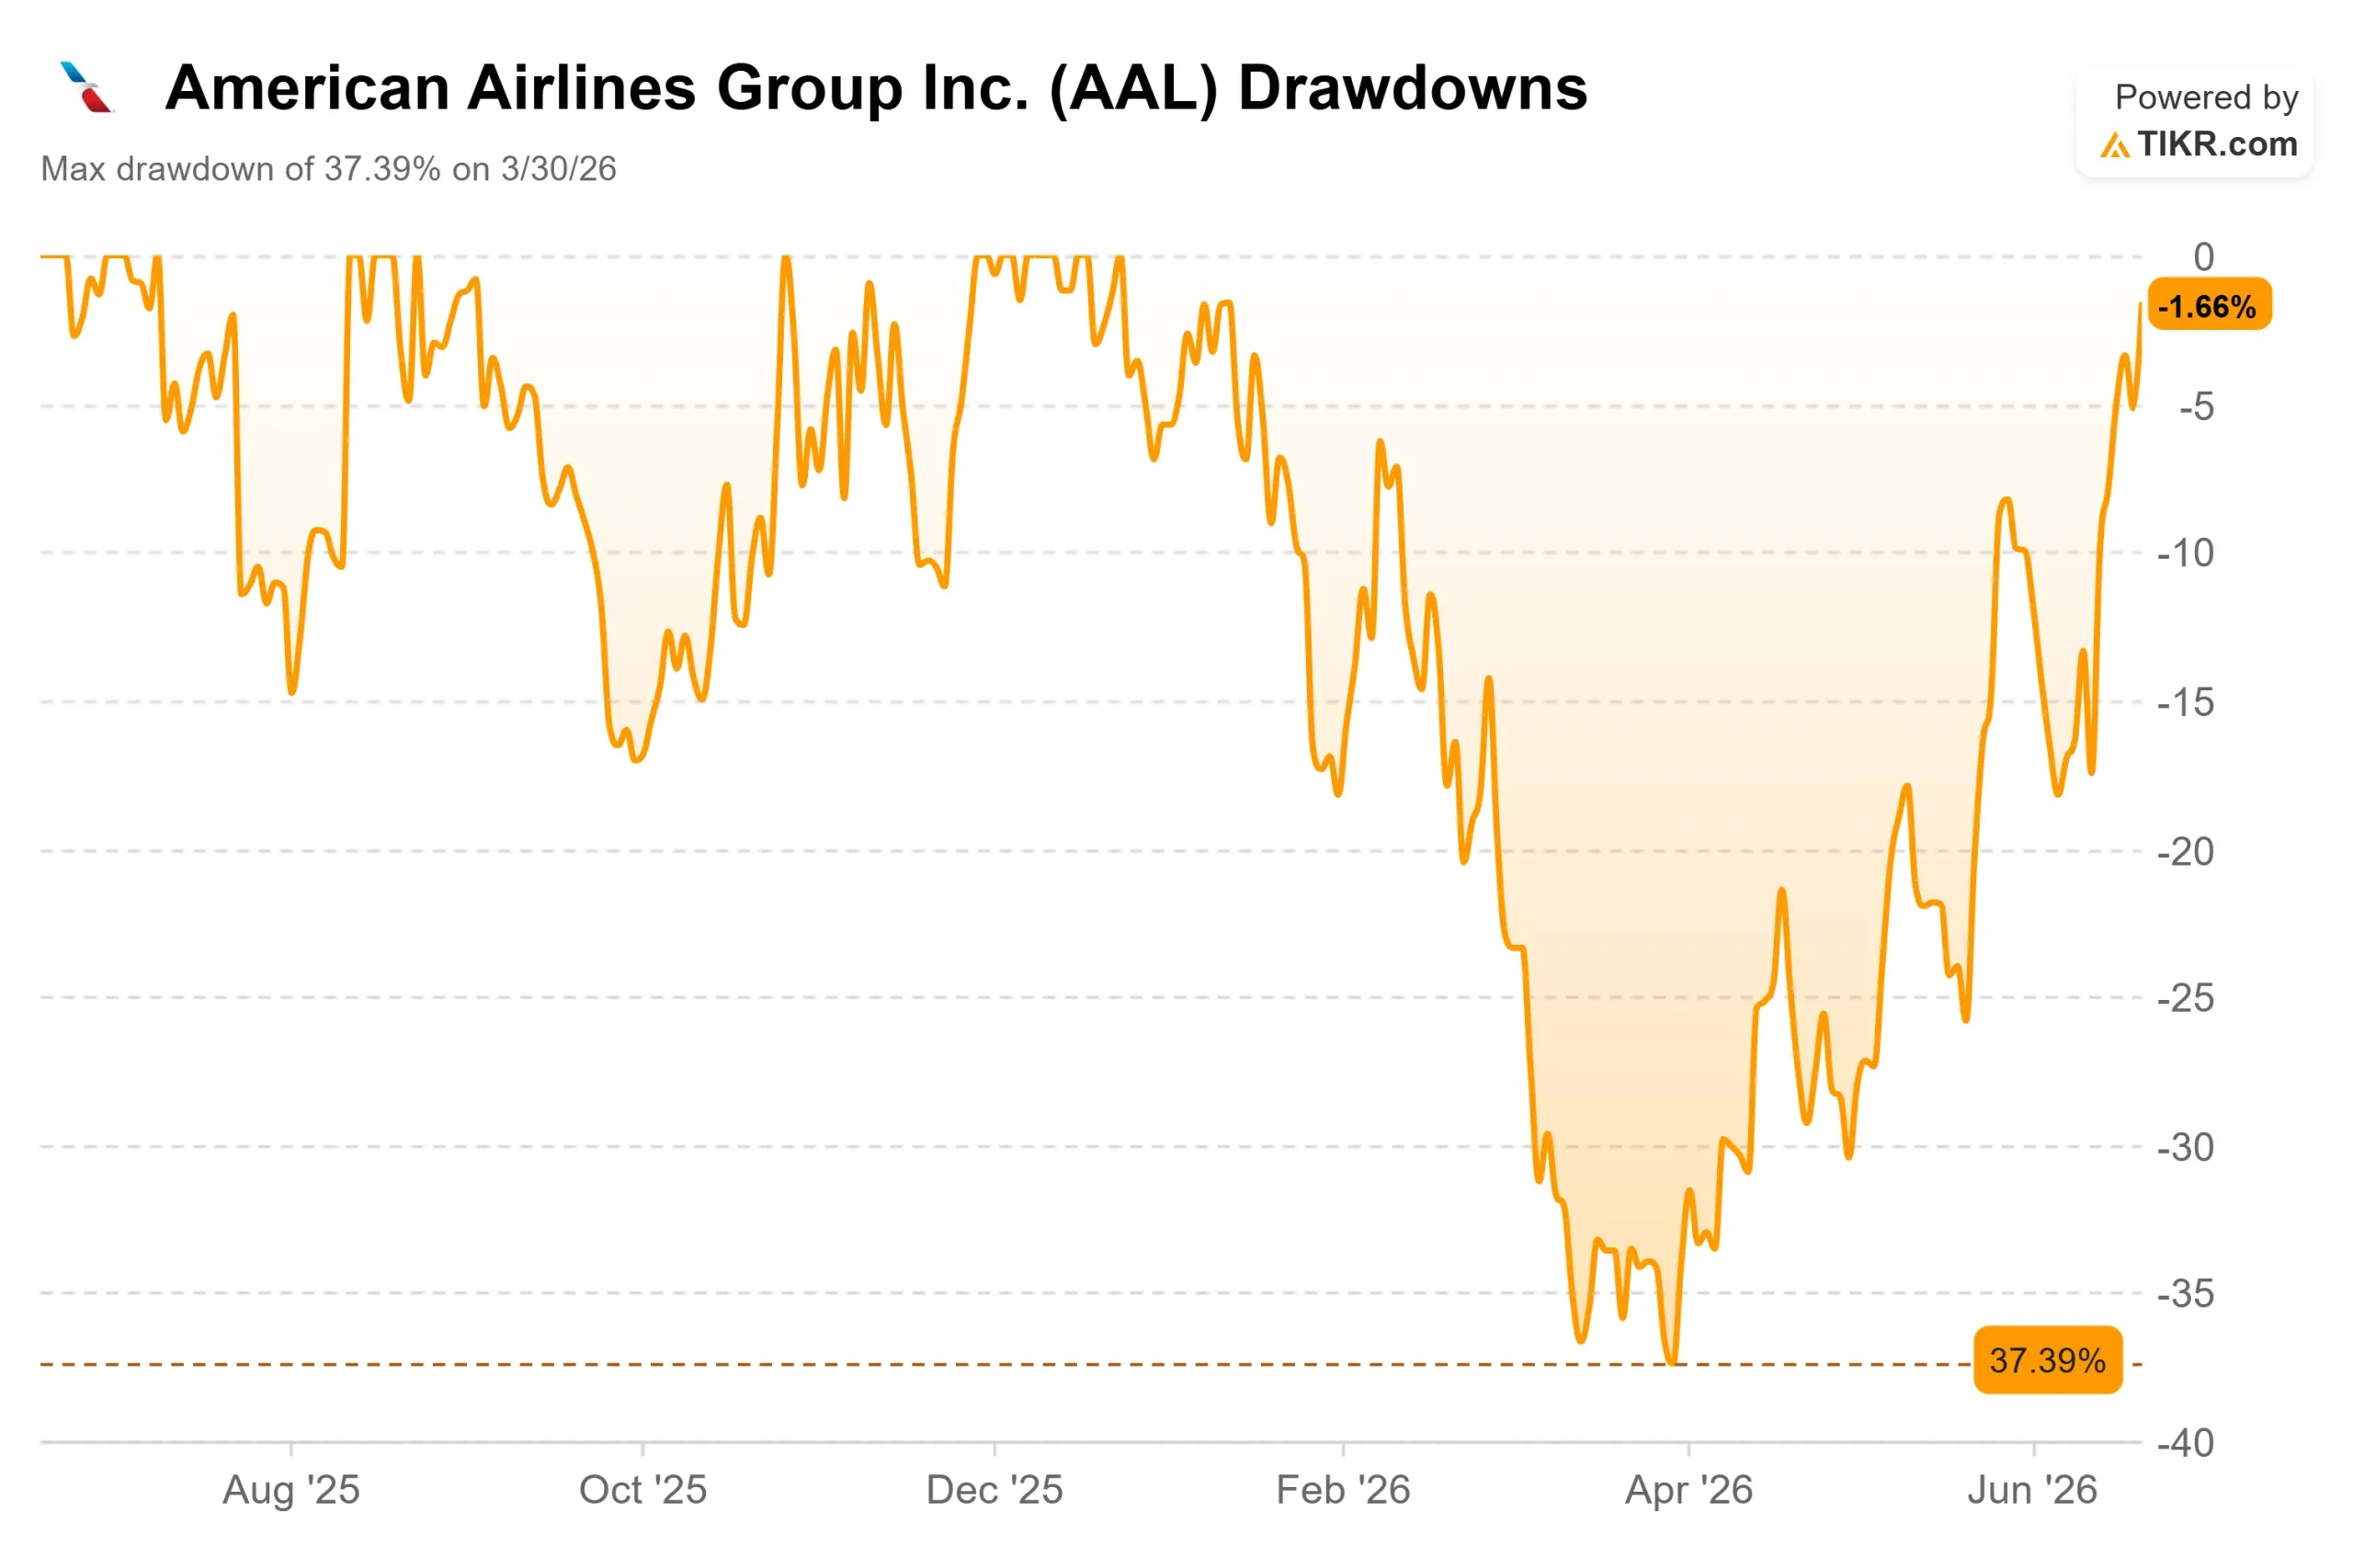
Conclusion
The story of American airline net worth is less about a single number and more about the interplay of tangible and intangible forces. The airline’s financial health isn’t defined by a static balance sheet but by its ability to adapt—whether through fleet modernization, cost management, or strategic partnerships. While debt levels and labor costs will always be points of scrutiny, the bigger picture is one of operational resilience. American’s net worth isn’t just a reflection of its past performance but a predictor of its ability to navigate future disruptions, from fuel price swings to labor negotiations. For investors, the takeaway is clear: American’s valuation is a function of its asset-light flexibility and network dominance. For travelers, it’s a reminder that the airline’s stability underpins the reliability of routes and service. And for analysts, it’s a lesson in how to read beyond the headlines—because in aviation, the most valuable assets aren’t always the ones that show up on the balance sheet.Comprehensive FAQs
Q: How is American Airlines’ net worth calculated?
American’s net worth is derived from its book value (assets minus liabilities) adjusted for market conditions. Key components include the net carrying value of aircraft (after depreciation), cash reserves, debt obligations, and intangible assets like brand equity. Unlike publicly traded tech firms, aviation net worth is heavily influenced by off-balance-sheet items (e.g., aircraft leases) and cyclical factors (fuel prices, capacity). The airline’s enterprise value (market cap + debt – cash) is often a more relevant metric for investors.
Q: Why does American Airlines’ net worth fluctuate so much?
Fluctuations stem from three primary drivers: fuel costs (which swing between 20% and 30% of operating expenses), labor negotiations (contracts can add or subtract billions in liabilities), and capital expenditures (fleet orders or sales). Unlike steady-state industries, airlines operate in a high-volatility environment where a 10% change in oil prices can shift net income by hundreds of millions. Additionally, accounting treatments (e.g., lease classifications) and one-time charges (like restructuring) create noise that obscures the underlying trend.
Q: Is American Airlines’ net worth higher than Delta’s or United’s?
Comparing net worth directly is challenging due to differences in fleet age, debt structure, and route networks. As of recent filings, American’s market capitalization has often trailed Delta’s but led United’s, reflecting investor perceptions of its cost discipline versus Delta’s premium positioning. However, enterprise value (a broader measure) can vary widely based on debt levels. American’s larger scale gives it a higher gross asset base, but its net worth is more sensitive to operating leverage—meaning it must fill more seats to achieve profitability than a leaner carrier like Southwest.
Q: How does American Airlines’ net worth compare to its competitors globally?
Globally, American’s net worth ranks among the top five airlines by enterprise value, behind only Emirates, Delta, and Lufthansa Group in some estimates. However, profitability metrics paint a different picture: Middle Eastern carriers like Emirates or Qatar Airways often report higher margins due to government subsidies and lower labor costs. American’s strength lies in its transatlantic and domestic dominance, which provides revenue diversification that single-market carriers lack. The key difference is that American’s net worth is asset-heavy (planes, slots) while carriers like Emirates rely more on liquidity and government backing for stability.
Q: Can American Airlines’ net worth be accurately predicted?
No—predicting net worth with precision is impossible due to black swan events (e.g., pandemics, geopolitical crises) and management decisions (e.g., fleet orders, labor strikes). Even sophisticated models rely on assumptions about fuel prices, interest rates, and passenger demand. However, long-term trends can be inferred: American’s net worth is likely to grow if it maintains cost efficiency, expands premium cabin capacity, and avoids overcapacity in key routes. The airline’s hedging strategies (for fuel and FX) also provide a floor under volatility, but no model can account for unforeseen disruptions like the 2020 shutdowns.
