The Complete Overview of America’s Wealth and Demographic Landscape in 2017
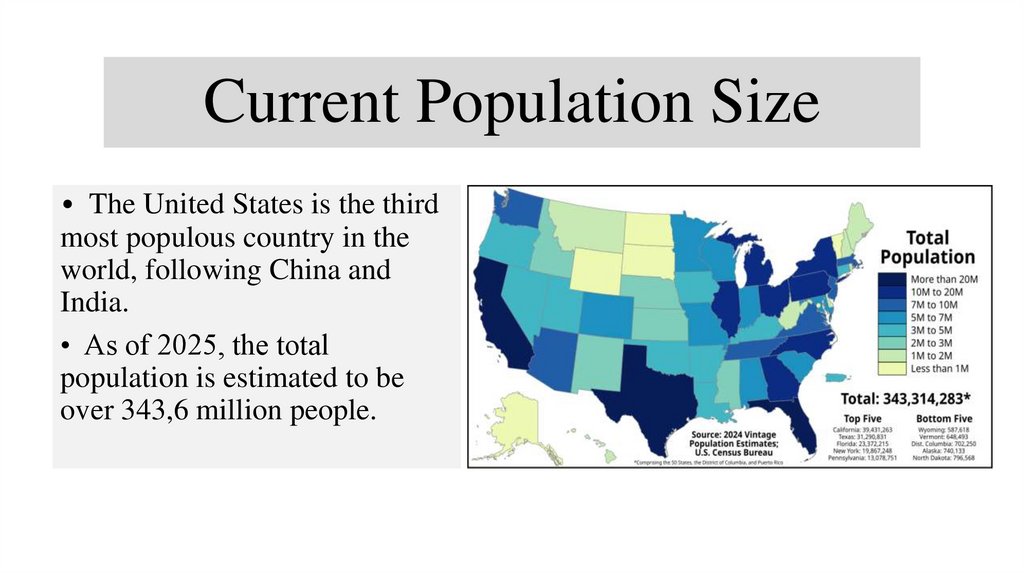
The America population versus net worth 2017 dynamic was defined by two competing forces: a growing headcount and a shrinking middle-class share of national wealth. By 2017, the U.S. population had risen to 324.5 million, yet the median net worth—$97,300—had barely budged from 2016 levels, adjusted for inflation. The disconnect was glaring: while the economy expanded, the benefits accrued disproportionately to those already wealthy. The Federal Reserve’s data showed that the bottom 40% of households had negative net worth when including mortgages and debts, meaning their liabilities exceeded their assets. This wasn’t a new phenomenon, but 2017 crystallized it. The Great Recession’s aftermath had left lasting scars: home values recovered, but wages didn’t. The S&P 500 surged 19.4% in 2017, yet the average worker saw only 2.5% wage growth. The result? A wealth-to-population ratio that favored the top tiers while the majority struggled with student debt, medical expenses, and stagnant housing markets. Even as unemployment dipped to 4.4%, the labor force participation rate remained depressed, signaling a workforce that was either underemployed or sidelined. The America population versus net worth 2017 equation also exposed regional disparities. States like California and New York saw population booms but also skyrocketing costs of living, pushing net worth down for many residents. Meanwhile, Texas and Florida attracted migrants with lower taxes but offered little in the way of wealth-building opportunities. The South, historically the poorest region, saw net worth growth of just 1.2% for Black households, compared to 4.7% for white households nationwide. The data wasn’t just numbers—it was a geographic wealth map where ZIP code determined financial destiny.Historical Background and Evolution
The roots of America’s wealth inequality by 2017 trace back to the 1980s, when deregulation, tax policy shifts, and the decline of unionization began reshaping income distribution. The Reagan-era tax cuts favored capital gains over wages, while Wall Street’s rise created a class of financial elites whose wealth grew exponentially. By the 1990s, the dot-com boom and subsequent bust demonstrated how speculative wealth could inflate and deflate without lifting the broader population. The 2000s brought another turning point. The housing bubble allowed millions to build equity, but the 2008 financial crisis wiped out $16.1 trillion in household wealth—a loss that took years to recover. The America population versus net worth 2017 snapshot reflected this volatility: while the top 1% saw their net worth increase by 11.9% from 2016 to 2017, the bottom 90% gained just 1.2%. The recovery had been uneven, with stock market gains benefiting those who owned assets while wages stagnated for service workers, teachers, and factory employees. Policy played a critical role. The Affordable Care Act expanded healthcare access but did little to address rising costs, while student loan debt ballooned to $1.4 trillion by 2017—68% of 2016 graduates left school with debt, yet salaries in education and public service remained flat. The America population versus net worth 2017 divide wasn’t just about money; it was about opportunity hoarding. Wealth begets wealth, and by 2017, the system was rigged to reward those who already had it.Core Mechanisms: How It Works
The America population versus net worth 2017 disparity functions through three primary mechanisms: asset ownership, inheritance, and policy leverage. The top 10% of households owned 84% of all stocks and mutual funds in 2017, meaning their wealth compounded through market gains while the majority relied on stagnant wages. Meanwhile, homeownership—historically the primary wealth-building tool—was out of reach for many. The median home price in 2017 was $318,000, yet the median household income was $61,372. Even with mortgage interest deductions, the down payment alone (typically 20%) required $63,600—a sum beyond the means of 60% of Americans. Inheritance amplified the gap. The America population versus net worth 2017 data showed that 64% of wealth transfers went to the top 10%, while the bottom 40% received less than 1%. This wasn’t just about money left in wills—it was about trust funds, family businesses, and real estate passed down through generations. The bottom 50% had no liquid assets to pass on, creating a wealth death spiral. Policy further tilted the scales. Tax reforms like the 2017 Tax Cuts and Jobs Act slashed corporate rates but offered limited relief to middle-class families. The capital gains tax remained low, rewarding long-term investors while payroll taxes (which fund Social Security and Medicare) fell disproportionately on workers. By 2017, the top 1% paid an effective federal tax rate of 24.3%, compared to 14.1% for the bottom 20%. The system wasn’t broken—it was designed to favor accumulation over distribution.Key Benefits and Crucial Impact
The America population versus net worth 2017 landscape had tangible consequences for economic mobility, political influence, and social stability. On one hand, a concentrated wealth base fueled innovation, venture capital, and philanthropy—sectors that drove technological advancement and cultural shifts. Silicon Valley’s billionaires, for instance, funded AI research, renewable energy, and education initiatives, even as their own wealth grew unchecked. Yet the downstream effects were destabilizing. Stagnant wages led to rising consumer debt, with credit card balances hitting $870 billion in 2017. Healthcare costs consumed 17.9% of personal consumption, outpacing inflation. The America population versus net worth 2017 gap also translated into political power: the top 0.1% spent $2.6 billion on lobbying in 2017, shaping policies that reinforced their advantages. Meanwhile, voter turnout among low-income groups remained 20% below that of high-income earners, creating a democratic feedback loop where wealth begets more wealth—and more influence."Wealth inequality is the mother’s milk of political quietism. When most people don’t feel they have a stake in the future, they stop showing up to vote." — Paul Pierson, Yale Political Scientist
Major Advantages
Despite the criticisms, the America population versus net worth 2017 structure conferred several structural advantages on the economy:- Capital infusion for high-growth sectors. Wealth concentration funded startups, R&D, and infrastructure, driving productivity gains in tech, biotech, and clean energy.
- Liquidity in financial markets. The top 1% held $24.4 trillion in liquid assets in 2017, providing stability during market volatility and enabling mergers, acquisitions, and expansion.
- Philanthropic leverage. Billionaires like Mark Zuckerberg and Warren Buffett redirected wealth into education, healthcare, and poverty alleviation, filling gaps left by government austerity.
- Global economic influence. The U.S. dollar’s dominance and Wall Street’s control over global capital flows were underpinned by domestic wealth concentration, maintaining America’s role as the world’s financial hub.
- Innovation ecosystems. Cities like San Francisco, Boston, and Austin thrived as magnets for venture capital, where $69 billion was invested in startups in 2017—a figure that would have been impossible without concentrated wealth.

Comparative Analysis
The America population versus net worth 2017 dynamic stood in stark contrast to other developed nations. While the U.S. led in GDP per capita ($60,200), its wealth Gini coefficient (0.856) was among the highest in the OECD—higher than Russia’s (0.830) and South Africa’s (0.631). Meanwhile, Nordic countries achieved lower inequality through progressive taxation, strong labor unions, and universal healthcare, ensuring that 80% of citizens owned at least 20% of national wealth.| Metric | United States (2017) | Germany (2017) | Sweden (2017) |
|---|---|---|---|
| Wealth Gini Coefficient | 0.856 (extreme inequality) | 0.720 (moderate) | 0.690 (low) |
| Top 1% Net Worth Share | 38.6% | 26.3% | 22.1% |
| Median Net Worth (Adjusted) | $97,300 | $115,000 (higher due to pension systems) | $120,000 (strong social safety nets) |
Future Trends and Innovations
By 2017, the America population versus net worth 2017 trajectory suggested three likely future scenarios. First, automation and AI threatened to erode middle-class jobs, pushing more workers into gig economy roles with no wealth accumulation. Second, student debt and healthcare costs would suppress homeownership rates, delaying wealth-building for younger generations. Third, policy shifts—such as universal basic income experiments or wealth taxes—could either narrow the gap or accelerate capital flight to offshore accounts. The tech sector’s influence would also grow. By 2017, FAANG stocks (Facebook, Apple, Amazon, Netflix, Google) accounted for $2.4 trillion in market cap, a figure larger than the GDP of all but 10 countries. As these companies reinvested profits into AI and automation, the wealth creation cycle would likely favor early adopters while marginalizing traditional labor. The America population versus net worth 2017 divide could thus widen further, unless new economic models—such as worker cooperatives or profit-sharing schemes—gained traction. One potential disruptor? Cryptocurrency and decentralized finance (DeFi). By 2017, Bitcoin’s market cap exceeded $20 billion, and initial coin offerings (ICOs) raised $3.7 billion—a figure that hinted at alternative wealth accumulation outside traditional banking. However, volatility and regulatory risks made this a double-edged sword: while it could democratize finance, it also risked creating new speculative bubbles that excluded the unbanked.
Conclusion
The America population versus net worth 2017 story was never just about numbers—it was about who controls the levers of economic power. The data from that year exposed a system where demographic growth coexisted with financial stagnation, where policy favored accumulation over redistribution, and where opportunity was not equally distributed. The consequences were visible in political polarization, urban displacement, and the rise of populist movements—all symptoms of a society where wealth and influence were increasingly concentrated. Yet the America population versus net worth 2017 snapshot also revealed points of intervention. Stronger labor protections, wealth taxes, and education reforms could reshape the trajectory. The question in 2017—and beyond—was whether democratic institutions would prioritize equitable growth over short-term efficiency. The answer would determine whether America’s population remained a statistic or became a force for sustainable prosperity.Comprehensive FAQs
Q: How did the America population versus net worth 2017 gap compare to previous decades?
The wealth-to-population ratio in 2017 was worse than in 1989 but less extreme than in 2007 (pre-crisis peak). The top 1%’s share of wealth rose from 23% in 1978 to 38.6% in 2017, a trend accelerated by deregulation, tax cuts, and financialization.
Q: Did America’s population growth in 2017 correlate with economic growth?
Not directly. While the population grew by 0.7% in 2017, real GDP grew by 2.3%, but wages grew by just 2.5%. The wealth gap widened because productivity gains flowed to capital owners, not labor. Immigrants, for example, boosted the workforce but often entered low-wage sectors with little path to asset accumulation.
Q: How did racial disparities factor into the America population versus net worth 2017 divide?
Racial wealth gaps were acute. The median white household net worth ($171,000 in 2016) was 13 times that of the median Black household ($13,000). Homeownership rates—a key wealth-builder—were 42% for Black families vs. 73% for white families. Inheritance and historical redlining played major roles, with Black families receiving just 1.5% of intergenerational wealth transfers.
Q: What role did student debt play in the America population versus net worth 2017 equation?
Student debt suppressed wealth accumulation for millennials. By 2017, $1.4 trillion in student loans weighed down 44 million borrowers, 68% of whom left school with debt. Graduates with loans had 40% less wealth than their debt-free peers. Unlike mortgages, student loans couldn’t be discharged in bankruptcy, trapping borrowers in low-paying service jobs while their peers invested in assets.
Q: How did tax policy in 2017 worsen the America population versus net worth imbalance?
The 2017 Tax Cuts and Jobs Act slashed corporate taxes to 21% but offered limited relief to middle-class families. The capital gains tax (15-20%) favored investors, while payroll taxes (15.3%) hit workers. The top 1% saw tax cuts of $166,000 per household, while the bottom 20% got $400. Estate tax exemptions also rose to $11.2 million per individual, allowing ultra-wealthy families to pass fortunes tax-free.
Q: Could automation in 2017 have predicted the future of America’s wealth distribution?
Yes. By 2017, AI and robotics were displacing mid-skill jobs in manufacturing, retail, and transportation. McKinsey estimated that up to 30% of U.S. tasks could be automated by 2030. Since wealth comes from owning capital (machines, algorithms, real estate), automation would likely increase inequality—unless worker ownership models (like ESOPs—Employee Stock Ownership Plans) gained ground. In 2017, only 10% of U.S. workers were in profit-sharing or co-op structures.
Q: What alternative economic models could have addressed the America population versus net worth 2017 crisis?
Several existed but were underutilized in 2017:
- Wealth taxes (e.g., Elizabeth Warren’s proposed 2% tax on net worth over $50M).
- Universal basic assets (e.g., giving every citizen a stake in public companies).
- Strong labor unions to negotiate profit-sharing.
- Public banking to compete with Wall Street on lending.
- Automated individual accounts (AIAs) to redirect Social Security surpluses into personal wealth-building tools.
