
Breaking Down the Numbers
The highest home prices in USA are concentrated in a handful of metros, but the factors pushing values upward vary by region. In San Francisco, it’s the tech boom and the city’s role as a global financial hub. In Miami, it’s the influx of Latin American capital and the allure of a tax-friendly haven. In New York, it’s the combination of legacy wealth, finite land, and the city’s status as the cultural capital of the U.S. These markets aren’t just expensive—they’re structurally expensive, with price-to-income ratios that would make economists wince. The median home in these areas often costs five or six times the annual income of a typical resident, a ratio that would be unthinkable in most of the country. What’s less discussed is how these prices distort local economies. In coastal cities, the highest home prices in USA have priced out service workers, teachers, and first responders—jobs that keep the economy running but can’t afford to live where they work. The result? Commutes that stretch hours, reliance on roommates or multigenerational households, and a brain drain as younger, mobile professionals flee to more affordable metros. The numbers don’t lie: in San Jose, for example, the average home price exceeds $1.5 million, while the median household income hovers around $140,000. That’s a 10:1 ratio—a figure that would have been unimaginable in past decades.The Verified Baseline
Public records confirm that the highest home prices in USA are clustered in three primary categories: urban luxury, waterfront exclusivity, and gated communities in secondary markets. The most expensive single-family homes on record—those with verified sales prices—tend to be in Manhattan, Malibu, and Palm Beach. A 2023 analysis of Zillow Premium Data and Redfin listings identified New York City as the undisputed leader, with Upper East Side co-ops consistently fetching $50 million to $100 million+ for properties under 10,000 square feet. These aren’t just homes; they’re status symbols, often purchased by ultra-high-net-worth individuals (UHNWIs) who treat them as liquid assets rather than primary residences. Outside of New York, California’s coastal elite dominate the charts. A 2022 Sotheby’s International Realty report highlighted Malibu as the gold standard for single-family luxury, where oceanfront estates have sold for $150 million to $200 million in recent years. The most expensive verified sale in U.S. history—a $238 million mansion in Bel Air—was a testament to the lengths to which buyers will go for privacy and prestige. Meanwhile, Florida’s Palm Beach has emerged as a dark horse, with waterfront estates commanding $30 million to $50 million, driven by a surge in international buyers, particularly from Latin America and the Middle East.What the Estimates Suggest
Beyond the verified sales, industry estimates suggest an even more opaque tier of the highest home prices in USA—properties that never hit the public record. Trust-law purchases, where buyers use LLCs or blind trusts to obscure ownership, are rampant in New York and Miami, where privacy is prized above all else. Mansion Global estimates that as much as 30% of high-end transactions in these markets are off-market, meaning the true median price for luxury homes could be 20% to 30% higher than reported. In Manhattan, for instance, a $100 million co-op might actually represent the lower end of what’s being paid in private deals. The estimates also point to emerging hotspots where the highest home prices in USA are still climbing. Austin, Texas, once a bastion of affordability, has seen luxury home values surge 40% in five years, driven by tech migration and a lack of zoning restrictions. Similarly, Nashville and Boise have experienced double-digit annual appreciation in high-end segments, as buyers flee coastal markets for perceived value. Yet these estimates carry caveats: appreciation rates can reverse quickly with a shift in migration patterns or interest rates. The highest home prices in USA aren’t just about current valuations—they’re a gamble on future demand, and that gamble is getting riskier.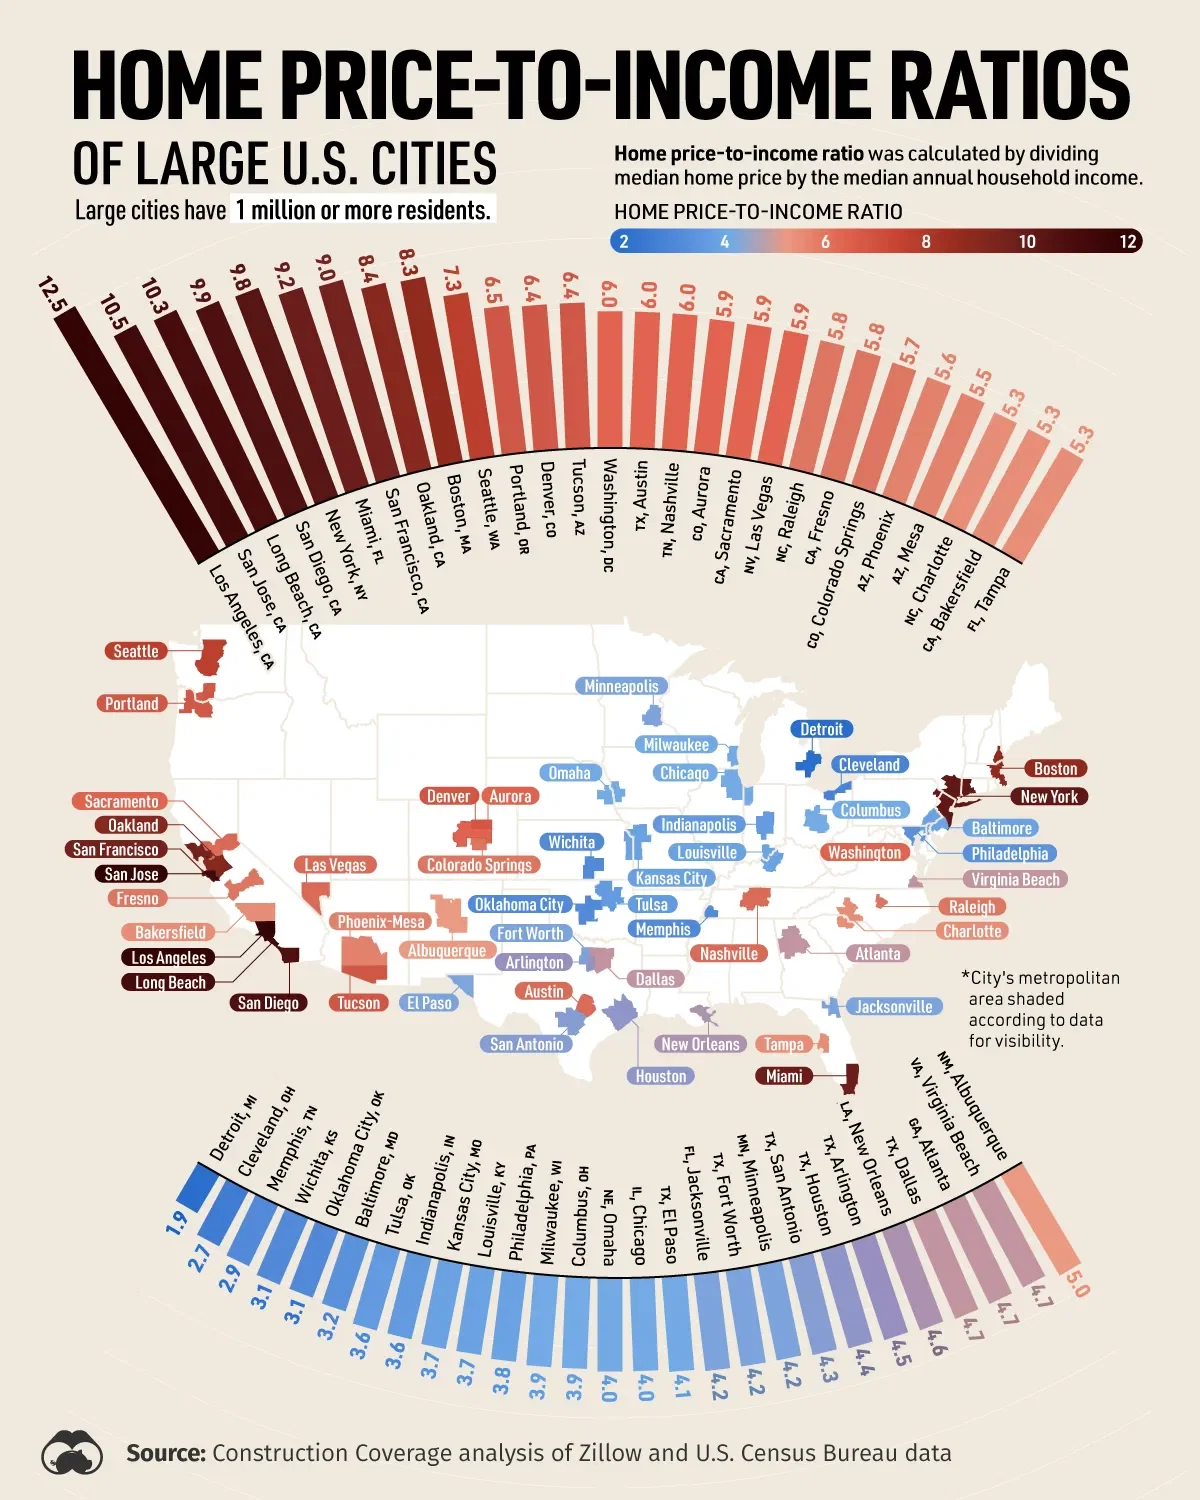
Case Study: A Closer Look
No market illustrates the highest home prices in USA better than Manhattan’s Upper East Side, where the intersection of wealth, history, and geography creates a feedback loop of escalating values. The most expensive co-ops—those in pre-war buildings with doormen, private terraces, and views of Central Park—have seen annual price increases of 8% to 12% over the past decade, outpacing inflation and wage growth. The 2023 record sale of a $137.5 million penthouse at 111 Central Park South wasn’t just a transaction; it was a statement. Buyers aren’t just paying for square footage—they’re investing in exclusivity, a neighborhood where the average resident’s net worth exceeds $10 million. What drives this? A table of key factors reveals the mechanics:| Factor | Estimated Impact |
|---|---|
| Limited Inventory | Only ~500 pre-war co-ops exist in the entire borough; no new supply is being added. |
| International Buyers | 30% to 40% of high-end purchases are made by foreign investors, particularly from China, Russia, and the Middle East. |
| Leverage & Financing | Wealthy buyers use private lending (6%–8% interest) to avoid bank scrutiny, inflating effective purchase prices. |
| Status & Networking | The neighborhood’s social capital—proximity to power brokers, galleries, and elite schools—adds 20%–30% to perceived value. |
"These aren’t just homes; they’re memberships. You’re not buying a building—you’re buying into a network. And in a world where trust is currency, that’s worth more than gold."The case of the Upper East Side also highlights a paradox: while prices soar, vacancy rates in luxury buildings hover around 5% to 7%, suggesting that many of these properties are investments, not homes. The highest home prices in USA, in this context, are less about shelter and more about asset preservation—a hedge against currency devaluation, political instability, or even existential risks like climate change.
What This Means Going Forward
The trajectory of the highest home prices in USA will be shaped by three wildcards: interest rates, migration trends, and regulatory changes. If the Federal Reserve keeps rates elevated, demand for luxury properties could stabilize or even dip, as buyers—especially those relying on leverage—pull back. Historically, high-end markets have proven resilient to downturns, but the 2008 crash revealed cracks: even billionaires’ mansions sat unsold for years. The difference today? Global capital is deeper and more mobile than ever, meaning any slowdown in the U.S. could redirect flows to London, Dubai, or Singapore—competitors that have been watching America’s real estate bubble with envy. Migration will also play a critical role. The Great Reshuffling of the past decade—where remote workers fled cities for affordability—has paused, but the underlying pressures remain. If tech layoffs persist, Silicon Valley’s luxury market could see a 10% to 15% correction, as buyers reconsider their exposure. Meanwhile, secondary markets like Austin and Nashville may see further appreciation if coastal buyers remain priced out. The highest home prices in USA are no longer just a coastal phenomenon; they’re spreading inland, creating new pockets of hyper-luxury where they once didn’t exist.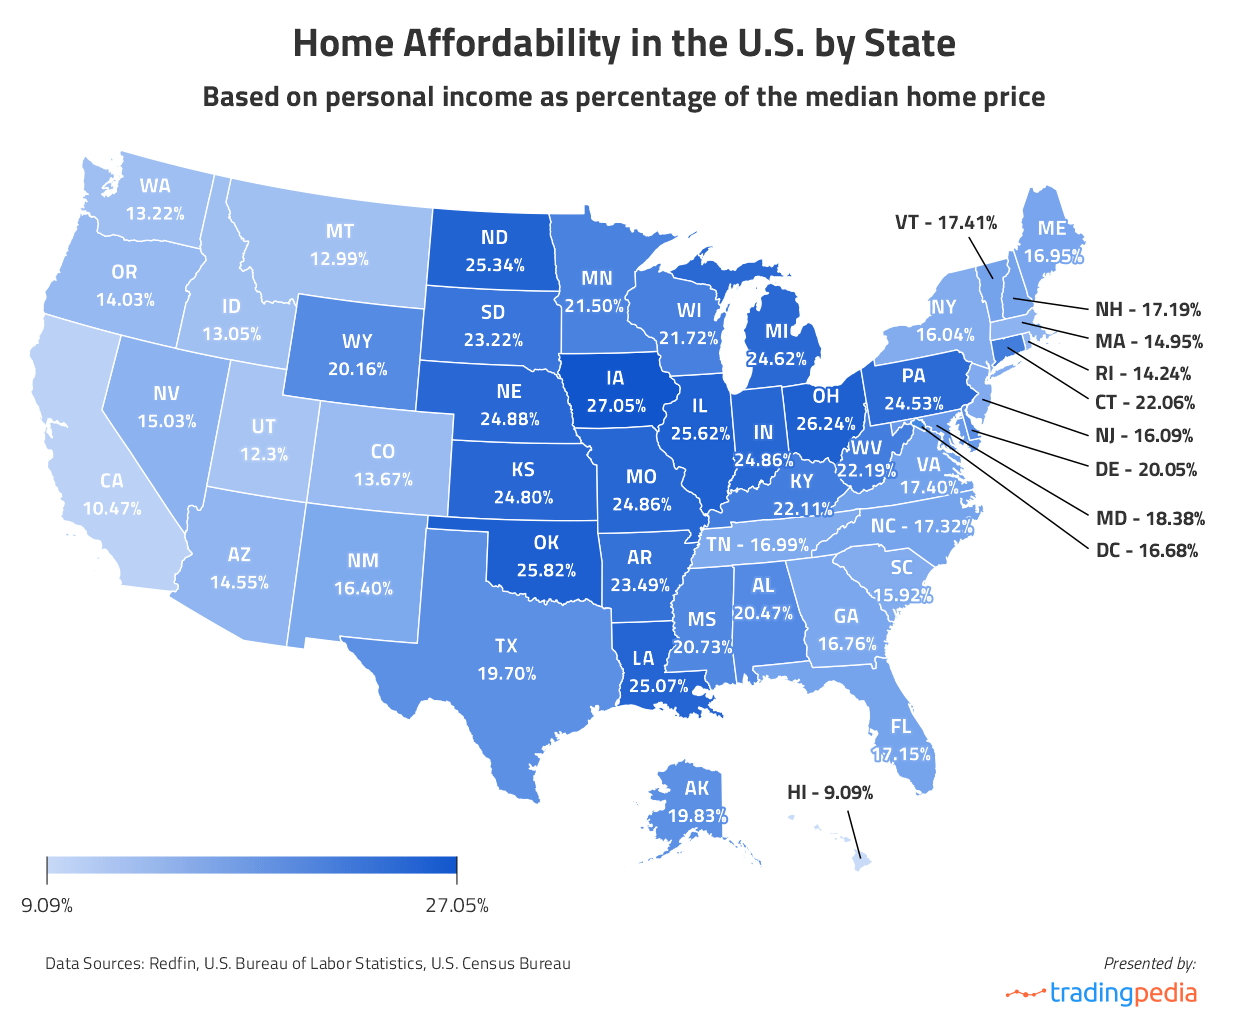
Conclusion
The highest home prices in USA are a symptom of a larger imbalance—one where wealth concentrates in fewer hands, and the cost of entry into the housing market becomes a barrier reserved for the ultra-wealthy. This isn’t just a real estate story; it’s a social and economic one. The fact that half of U.S. homeowners have no equity while a handful of zip codes command $100 million+ for a single property says everything about the polarized nature of modern America. Yet for those at the top, the highest home prices in USA remain a rational investment. In a world of volatile stocks, geopolitical uncertainty, and inflation, real estate—especially in prestige markets—offers tangible security. The question isn’t whether these prices will fall; it’s whether the underlying demand will ever wane. For now, the answer is no. The highest home prices in USA aren’t just holding steady—they’re redefining what wealth looks like in the 21st century.Comprehensive FAQs
Q: Which U.S. city has the highest average home price?
A: San Francisco and San Jose consistently rank at the top for average home values, with median prices exceeding $1.4 million in 2024. However, New York City holds the record for single highest sales, with co-op apartments frequently surpassing $100 million. The distinction depends on whether you’re measuring median prices (San Francisco) or outlier transactions (New York).
Q: Are the highest home prices in USA still rising?
A: Yes, but at a slower pace. In 2023–2024, luxury markets saw single-digit appreciation (3%–7%) compared to double-digit gains in 2021–2022. The Federal Reserve’s rate hikes have cooled demand, but international buyers and limited supply continue to support high valuations. Coastal cities remain the most resilient, while secondary markets like Austin and Boise are seeing accelerated growth as buyers seek alternatives.
Q: Can I buy a home in the highest-priced U.S. markets with a mortgage?
A: Technically yes, but with extreme conditions. Most banks cap loan-to-value (LTV) ratios at 60%–70% for luxury properties, meaning buyers must put down 30%–40% of the purchase price. Jumbo loans (over $726,200 in most areas) require excellent credit (740+ FICO) and high income verification. Many ultra-high-net-worth buyers use private lending (6%–10% interest) or all-cash deals to avoid mortgage restrictions entirely.
Q: Are there any U.S. markets where home prices are too high to be sustainable?
A: Yes, particularly in markets with:
- Extreme price-to-income ratios (e.g., San Jose’s 10:1 ratio).
- Over-reliance on international capital (e.g., Miami, NYC).
- Limited job growth (e.g., San Francisco, where tech layoffs have slowed appreciation).
Q: How do the highest home prices in USA compare to global luxury markets?
A: U.S. prices are competitive but not dominant. London’s Mayfair and Hong Kong’s Peak still command higher per-square-foot costs, but New York and Manhattan lead in total transaction values. For example, a $200 million penthouse in Central Park would be rare in global markets—most luxury buyers in Dubai or Monaco deal in $50 million to $100 million ranges. The U.S. wins on scale and prestige, but Asia and Europe often outpace in exclusivity and privacy protections.
Q: What’s the biggest risk to the highest home prices in USA?
A: A sustained high-interest-rate environment combined with a shift in buyer demographics. If tech wealth declines (due to layoffs or market corrections) and international capital retreats (due to geopolitical risks), the highest home prices in USA could face downward pressure. The biggest wild card? Regulatory changes—such as vacancy taxes (already in place in San Francisco) or foreign buyer restrictions—could further destabilize markets where speculation drives demand.
