The Complete Overview of Altria Group’s Net Worth
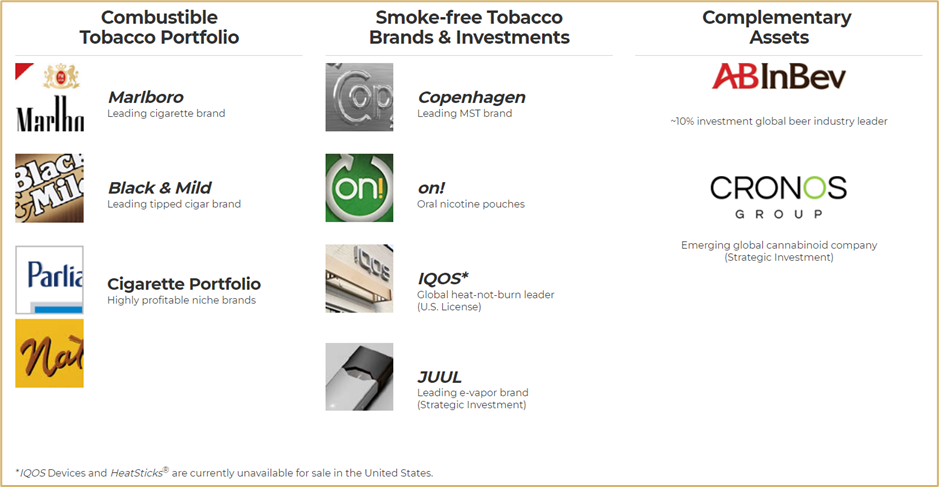
Altria Group’s net worth is a study in contrasts: a company built on decades of cigarette dominance now gambling on a future where smoking is increasingly taboo. As of recent filings, Altria’s total enterprise value—a measure that includes debt—hovers around $40 billion, though this figure is fluid, influenced by stock performance, acquisition costs, and the unpredictable regulatory environment. The company’s market capitalization has swung between $20 billion and $50 billion over the past five years, reflecting investor confidence in its ability to navigate the transition away from cigarettes. Unlike pure-play tobacco firms, Altria’s net worth is no longer solely tied to cigarette sales; it’s now a composite of legacy revenue, alternative product lines (like vaping and oral nicotine products), and strategic investments in companies like Juul, which it acquired for $12.8 billion in 2018—a deal that later became a liability as regulatory crackdowns and lawsuits mounted. What sets Altria apart is its dual revenue model: traditional tobacco still accounts for roughly 80% of its earnings, but the company has aggressively funneled capital into reduced-risk alternatives. The stakes are high. If Altria’s bet on vaping and nicotine pouches pays off, its net worth could stabilize or even grow. If not, the company risks becoming a relic of an industry in decline. The financial tightrope Altria walks is evident in its free cash flow, which has been deployed not just for dividends (a cornerstone of its investor appeal) but also for R&D and acquisitions. The challenge? Balancing shareholder returns with the heavy lifting required to transition to a non-combustible future.Historical Background and Evolution
Altria’s origins trace back to 1984, when it was spun off from Philip Morris Companies as a standalone entity focused on tobacco. At its peak in the early 2000s, Altria’s net worth was synonymous with Marlboro’s global dominance—a brand that accounted for nearly half of all cigarettes sold in the U.S. The company’s financial might was unassailable, with annual revenues exceeding $30 billion and a market cap that frequently topped $100 billion. However, the late 2000s marked the beginning of the end for the old model. Anti-smoking legislation, lawsuits from state attorneys general, and a cultural shift toward health consciousness began eroding Altria’s market share. By 2010, the company’s net worth had taken a hit, with stock prices reflecting the reality that the cigarette business was no longer a growth engine but a mature, declining industry. The turning point came in 2018, when Altria made its boldest move yet: acquiring a 35% stake in Juul for $12.8 billion. The deal was a gamble—one that initially boosted Altria’s net worth on paper but later became a cautionary tale. Juul’s rapid rise and subsequent fall (due to FDA scrutiny, lawsuits, and a backlash against youth vaping) exposed the risks of betting heavily on a single alternative product. Yet Altria’s strategy wasn’t abandoned; it was refined. The company doubled down on oral nicotine products (like Copenhagen and Skoal) and invested in its own vaping platform, NJOY. These moves were less about replacing cigarettes entirely and more about capturing smokers who might otherwise switch to unregulated or black-market alternatives. The result? Altria’s net worth remains volatile, but the company has positioned itself as a player in the broader nicotine market—not just tobacco.Core Mechanisms: How It Works
Altria’s financial model operates on three pillars: legacy revenue, alternative product growth, and capital discipline. The first pillar—traditional tobacco—remains the bedrock of its net worth, generating steady cash flow despite declining volumes. Marlboro alone contributes roughly 50% of Altria’s earnings, a testament to the brand’s enduring loyalty among adult smokers. However, this segment is under relentless pressure from excise taxes, which have risen sharply in recent years, and from a shrinking customer base. The second pillar, alternative products, is where Altria is placing its future bets. Vaping (via NJOY and its stake in Juul), nicotine pouches (like On!), and heated tobacco devices (like the IQOS partnership) are designed to appeal to smokers who want to reduce harm without quitting nicotine entirely. The third pillar is capital allocation: Altria has become adept at deploying free cash flow toward dividends (currently yielding around 8-10%), share buybacks, and strategic acquisitions—though the latter has proven hit-or-miss. What distinguishes Altria’s approach is its portfolio play. Rather than doubling down on a single alternative product, the company has diversified its risk by investing in multiple platforms. This strategy is evident in its partnerships with Philip Morris International (for IQOS in the U.S.) and its ownership stakes in companies like Steep Hill Labs, a cannabis-derived nicotine producer. The goal is clear: to ensure that as one product faces regulatory or market headwinds, others can compensate. Yet this diversification comes at a cost. Altria’s net worth is diluted by the high upfront investments required to develop and market these alternatives, and the timeline for profitability remains uncertain. The company’s ability to execute on this multi-pronged strategy will determine whether its net worth stabilizes—or continues to decline.Key Benefits and Crucial Impact
Altria’s net worth is more than a financial metric; it’s a reflection of the company’s ability to adapt in an industry under siege. For investors, the appeal lies in Altria’s dividend aristocrat status—a rare consistency in an era of corporate volatility. The company has paid dividends for over a century, and even as cigarette sales falter, Altria has maintained its payout, making it a staple in income-focused portfolios. For regulators, Altria’s net worth is a double-edged sword: while the company’s size gives it leverage in lobbying against restrictive tobacco policies, its financial dependence on smoking also makes it a target for public health advocates pushing for stricter controls. And for consumers, Altria’s transition to reduced-risk products—however imperfect—represents a potential path away from combustible cigarettes, even if the alternatives come with their own controversies. The company’s impact extends beyond its balance sheet. Altria’s net worth is a bellwether for the entire tobacco sector, signaling whether legacy firms can survive the shift toward harm reduction. Its acquisitions and partnerships have accelerated innovation in the nicotine space, albeit with mixed results. The Juul investment, for instance, highlighted the risks of moving too quickly into unproven markets, while its IQOS collaboration with PMI demonstrates the power of strategic alliances in navigating regulatory hurdles. As Altria’s net worth becomes increasingly tied to these alternatives, the company’s success—or failure—will shape the future of tobacco for years to come."Altria is caught between two worlds: the fading glory of cigarettes and the uncertain promise of alternatives. Its net worth is the scorecard for that tension." — Industry analyst, 2023
Major Advantages
- Brand dominance: Marlboro remains the most recognized cigarette brand globally, providing a steady revenue stream despite declining volumes.
- Diversified product pipeline: Investments in vaping, nicotine pouches, and heated tobacco create multiple revenue streams beyond cigarettes.
- Strong cash flow generation: Even in decline, traditional tobacco yields consistent free cash flow, funding dividends and R&D.
- Regulatory influence: As a major player, Altria has leverage in shaping tobacco policies, though this is increasingly contested.
- Partnership ecosystem: Collaborations with PMI (IQOS) and stakes in companies like Juul and Steep Hill Labs spread risk across multiple platforms.
- Investor resilience: Altria’s dividend track record and shareholder-friendly policies attract income-focused investors despite industry headwinds.

Comparative Analysis
| Metric | Altria Group | Philip Morris International (PMI) |
|---|---|---|
| Primary Business Focus | U.S.-centric tobacco + reduced-risk products | Global tobacco + IQOS leadership |
| Market Capitalization (2023) | ~$40 billion (volatile) | ~$150 billion (stable growth) |
| Dividend Yield | 8-10% | 4-5% |
| Alternative Product Revenue | Growing but <10% of total | IQOS drives ~20% of revenue |
| Regulatory Risk | High (U.S. anti-smoking laws) | Moderate (global diversification) |
Future Trends and Innovations
Altria’s net worth will be shaped by three critical trends in the coming years. First, the regulatory landscape will determine how quickly the company can pivot. Stricter FDA oversight on vaping, potential bans on menthol cigarettes, and state-level tax hikes could accelerate the decline of traditional tobacco while forcing Altria to accelerate its transition to alternatives. Second, consumer behavior will dictate the success of reduced-risk products. If smokers reject vaping and pouches in favor of quitting or turning to unregulated markets, Altria’s net worth could face further pressure. Conversely, if these products gain traction among harm-reduction seekers, they could become the backbone of the company’s future. Finally, competition will intensify as smaller players and international firms (like PMI) encroach on Altria’s U.S. dominance. The company’s ability to innovate and execute will be tested like never before. One area to watch is cannabis-derived nicotine. Altria’s investment in Steep Hill Labs positions it to explore THC-free cannabis products, which could offer a third path for smokers looking to reduce harm. Additionally, the company’s partnership with PMI on IQOS in the U.S. could prove pivotal if heated tobacco gains broader acceptance. However, the biggest wild card remains generational shift. Millennials and Gen Z are far less likely to smoke, and even if they use nicotine, they may prefer discreet, non-combustible formats. Altria’s net worth will ultimately hinge on whether it can appeal to these demographics—or if it becomes a relic of an era when smoking was still socially acceptable.
Conclusion
Altria Group’s net worth is a microcosm of the tobacco industry’s existential crisis. The company’s financial trajectory is no longer a straight line downward but a series of pivots, each more desperate than the last. What was once a monolithic force in American business is now a conglomerate balancing legacy revenue with high-risk bets on the future of nicotine. The numbers tell a story of resilience, but the underlying reality is stark: Altria’s net worth is being redefined by forces it cannot fully control—regulators, consumers, and competitors all pushing the industry toward an uncertain future. The question for Altria isn’t whether its net worth will decline further, but how it will adapt. The company’s leadership has shown a willingness to take bold risks, from the Juul acquisition to its IQOS partnership. Yet success is far from guaranteed. If Altria can execute its strategy—diversifying revenue, navigating regulation, and appealing to new users—its net worth could stabilize or even grow. If not, the company may face the fate of other tobacco giants: irrelevance in a world moving away from smoking. For now, Altria’s net worth remains a critical indicator of the industry’s ability to evolve—or fade into history.Comprehensive FAQs
Q: How much is Altria Group worth today?
As of recent estimates, Altria’s market capitalization fluctuates around $40 billion, though its enterprise value (including debt) is higher. The figure is volatile due to stock performance, regulatory risks, and the company’s transition to reduced-risk products.
Q: What percentage of Altria’s revenue comes from cigarettes?
Traditional cigarettes still account for roughly 80% of Altria’s earnings, though this share has been declining as the company invests in vaping, nicotine pouches, and heated tobacco. The goal is to reduce dependence on combustible products over time.
Q: Why did Altria buy Juul for $12.8 billion?
Altria acquired a 35% stake in Juul in 2018 as a strategic bet on vaping’s potential to replace cigarettes. The move was intended to position Altria as a leader in reduced-risk products, but Juul’s subsequent legal and regulatory troubles turned the investment into a liability, contributing to Altria’s net worth volatility.
Q: Does Altria still pay dividends?
Yes. Altria is a dividend aristocrat, meaning it has increased its payout for over 50 consecutive years. Even as cigarette sales decline, the company has maintained its dividend, currently yielding around 8-10%, making it attractive to income investors.
Q: How does Altria’s net worth compare to Philip Morris International (PMI)?
PMI’s market cap is significantly larger (~$150 billion) due to its global reach and stronger performance in reduced-risk products like IQOS. Altria, meanwhile, is more exposed to the U.S. market and its regulatory challenges, making its net worth more volatile.
Q: What are Altria’s biggest risks to its net worth?
The primary risks include regulatory crackdowns (e.g., FDA restrictions on vaping, menthol bans), declining cigarette sales, and competition from both legacy tobacco firms and disruptive startups. Additionally, the success of its alternative products remains unproven at scale.
Q: Could Altria’s net worth grow in the next decade?
It’s possible, but unlikely without major breakthroughs. Growth would depend on successful execution of its reduced-risk product strategy, regulatory stability, and its ability to attract younger nicotine users. If these factors align, Altria’s net worth could stabilize or even appreciate.
Q: What’s the biggest threat to Altria’s long-term survival?
The demographic shift away from smoking poses the greatest existential threat. If younger generations reject all forms of nicotine—or if Altria fails to develop appealing alternatives—the company’s net worth could erode to the point where it becomes unsustainable as a standalone entity.
