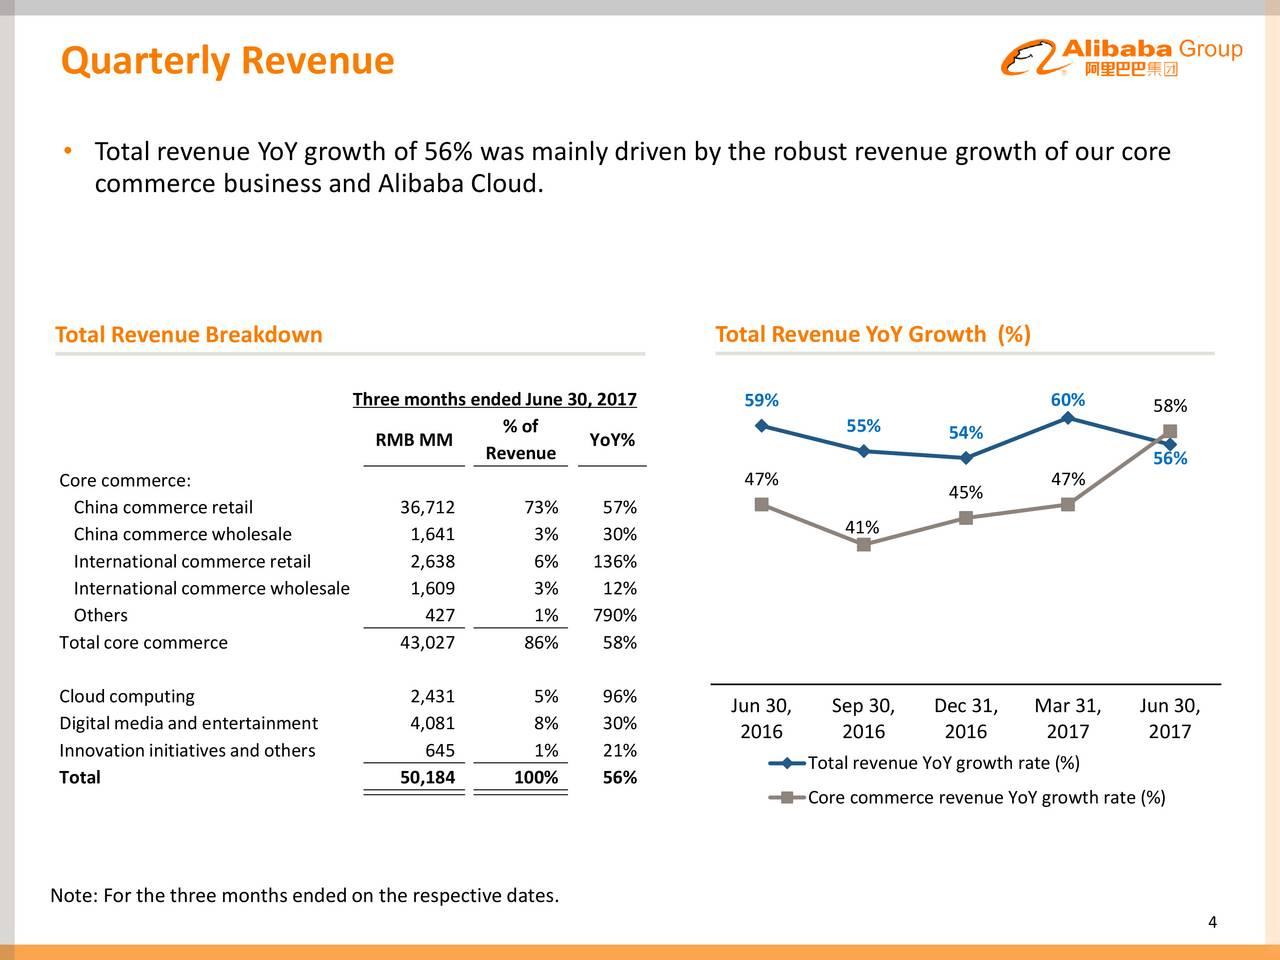
The first time the whispers started, they were quiet—just murmurs in boardrooms and among analysts. Alibaba’s numbers were growing too fast, too smoothly, for comfort. The company’s valuation, once a symbol of China’s digital revolution, had ballooned beyond what traditional metrics could justify. By 2014, the discrepancies between Alibaba’s reported earnings and its actual cash flow were noticeable enough to trigger internal audits. Yet, the narrative persisted: this was the future, unconstrained by old-world rules. Even as revenue figures climbed, questions lingered about how much of that growth was organic—and how much was being massaged to meet investor expectations.
Then came the IPO. In 2014, Alibaba’s $25 billion debut on the New York Stock Exchange was the largest in history, with a valuation that seemed to defy gravity. The company’s founders, including Jack Ma, became overnight billionaires, their net worth figures cited in headlines as proof of China’s tech ascendancy. But behind the scenes, red flags were appearing. Analysts noted inconsistencies in revenue recognition, particularly around its cloud computing segment, Alibaba Cloud. The company’s aggressive accounting—delaying revenue recognition until contracts were fully executed—meant earnings looked stronger than they were. By 2016, regulators in Hong Kong had begun probing whether Alibaba was
overstating its financial health to sustain its stock price.
The turning point arrived in 2018, when Alibaba’s revenue growth slowed for the first time in years. The stock price, which had soared post-IPO, began a steep decline. Short sellers, who had long questioned Alibaba’s earnings quality, gained traction. A report by the investment firm Citigroup accused the company of inflating its net income by as much as 20% through improper revenue recognition. The controversy forced Alibaba to restate its financials for the prior two years, admitting to errors in how it accounted for vendor subsidies and other one-time adjustments. The damage was done: investor confidence had eroded, and the narrative of Alibaba as an untouchable tech titan had cracked.

What followed was a pattern of financial adjustments, each more significant than the last. In 2020, Alibaba disclosed another restatement, this time affecting its 2019 results, after regulators flagged discrepancies in how it treated certain transaction costs. The company argued that these were isolated cases of miscommunication, not systemic fraud. Yet, the cumulative effect was undeniable: Alibaba’s
earnings and net worth claims had been systematically overstated for years, not by billions, but by enough to distort its true financial standing. The question was no longer whether Alibaba had overstated its numbers—but how much, and why it had taken so long to correct them.
Where It All Began
Alibaba’s origins trace back to 1999, when Jack Ma and a team of 18 founders launched the company out of a small apartment in Hangzhou. The early years were about survival: Ma’s relentless hustle, the late-night negotiations with suppliers, and the sheer audacity of selling to global markets before China’s e-commerce infrastructure existed. By 2004, Alibaba had gone public in Hong Kong, raising $1.3 billion—a modest sum compared to what was to come. The IPO was a triumph, but it also set a precedent: Alibaba’s financial disclosures would soon become a subject of both admiration and scrutiny.
The company’s rapid expansion in the mid-2000s relied on a mix of innovation and financial creativity. Alibaba pioneered the "village model," where it subsidized rural merchants to list on its platform, driving user growth. But this model also introduced accounting complexities. Revenue from these subsidies was sometimes recognized upfront, even though the actual sales would take years to materialize. Analysts at the time dismissed these practices as necessary growing pains. Yet, as Alibaba’s market cap surged past $200 billion, the gap between its reported earnings and cash flow widened. The first whispers of
Alibaba’s inflated financials emerged not from fraud allegations, but from the sheer scale of the discrepancies.
####
The Early Signs
By 2010, Alibaba’s revenue had crossed $4 billion, but its net income lagged behind expectations. The company attributed this to heavy investments in infrastructure and talent. What outsiders didn’t realize was that Alibaba was also using aggressive accounting tactics to smooth out its earnings. For example, it would defer certain costs to later periods, making current-year profits appear higher. This wasn’t illegal—yet—but it blurred the line between prudent financial management and manipulation.
The real inflection point came in 2012, when Alibaba’s cloud computing division, Alibaba Cloud, began reporting explosive growth. Analysts praised the segment as a high-margin gem, but questions arose about how quickly the business could scale. Cloud revenue recognition, in particular, became a flashpoint. Alibaba would sometimes recognize revenue from cloud services before contracts were fully executed, a practice that inflated short-term earnings. These early signs were ignored, overshadowed by the company’s broader narrative as a disruptor. But the seeds of distrust had been planted.
The Turning Point
The moment Alibaba’s financial practices became impossible to ignore was 2018. The company’s revenue growth, which had averaged 50% annually for a decade, slowed to just 53%. The stock, which had traded as high as $195 per share, plummeted to under $100. Short sellers, led by firms like Citigroup and Morgan Stanley, began publishing reports detailing what they called "earnings quality issues." Their argument was simple: Alibaba’s net income was being propped up by one-time adjustments and deferred revenue recognition.
The breaking point came when Alibaba restated its financials for 2016 and 2017, reducing its net income by $1.3 billion. The restatement wasn’t due to fraud, but to a misinterpretation of accounting rules around vendor subsidies. Yet, the damage was done. Investors who had bought into Alibaba’s story of unstoppable growth now saw a company that had
systematically overstated its earnings to maintain its valuation. The restatements were a rare admission of error, but they also exposed how deeply embedded these practices had become.
>
"Alibaba’s financial disclosures were never wrong—they were just optimistic. The problem wasn’t fraud; it was a culture where meeting expectations came before accuracy."
The Build-Up, Year by Year
|
Period | What Happened / What Changed |
|------------------|--------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|
| 2014–2015 | Alibaba’s U.S. IPO valued the company at $250 billion. Early reports noted aggressive revenue recognition in cloud services, but these were dismissed as growth pains. Net worth claims for founders like Jack Ma surged into the tens of billions. |
| 2016 | Revenue growth slowed to 49%. Analysts began questioning whether Alibaba’s earnings were sustainable. The company’s cash burn rate rose, raising concerns about its true profitability. |
| 2017 | Alibaba’s net income grew by 41%, but free cash flow lagged. Short sellers like Citigroup accused the company of inflating earnings through improper accounting. The first restatement occurred, though it was framed as a minor adjustment. |
| 2018 | Revenue growth dipped to 53%. Alibaba restated earnings for 2016–2017, cutting net income by $1.3 billion. The stock price collapsed, and skepticism over Alibaba’s net worth inflation reached a fever pitch. |
| 2020 | Another restatement affected 2019 results, this time due to misclassified transaction costs. The company argued these were accounting errors, not fraud—but the cumulative effect reinforced doubts about its financial transparency. |
####
Lessons From the Journey
- Revenue recognition was the biggest red flag. Alibaba’s practice of recognizing revenue early—especially in cloud services—created a misleading picture of profitability.
- Cash flow vs. net income. Even as net income climbed, Alibaba’s free cash flow often lagged, signaling that earnings were being propped up by accounting adjustments.
- Regulatory scrutiny forced corrections. Each restatement was triggered by external pressure, not internal initiative, suggesting a lack of proactive financial discipline.
- The IPO set unrealistic expectations. The 2014 valuation created a benchmark that Alibaba struggled to meet, leading to aggressive financial reporting to sustain investor confidence.
- Culture of growth over accuracy. From its founding, Alibaba prioritized expansion over rigorous financial controls, which later became a liability.
Where Things Stand Today
As of 2024, Alibaba remains one of the world’s most valuable companies, but its financial narrative has shifted. The restatements of the late 2010s forced the company to adopt stricter accounting practices, though skeptics argue these changes came too late. Today, Alibaba’s net worth and earnings are still scrutinized, but the focus has shifted from outright fraud to
whether the company has genuinely reformed its financial disclosures. The stock, though volatile, has stabilized around the $100–$150 range, a far cry from its 2014 peak.
The broader lesson is that Alibaba’s story is one of a company that grew too fast, too aggressively, and in doing so, blurred the lines between smart financial management and manipulation. While no evidence of criminal fraud has emerged, the repeated restatements have left a stain on its reputation. Investors now watch Alibaba’s earnings calls with a critical eye, dissecting every line item for signs of overstatement. The question lingering in boardrooms and among analysts isn’t whether Alibaba will overstate again—but when, and by how much.
Conclusion
Alibaba’s financial saga is a case study in how unchecked growth can lead to systemic overstatement. The company’s early years were defined by innovation and risk-taking, but as it scaled, so did the temptation to massage numbers to meet market expectations. The restatements of the past decade weren’t just accounting errors; they were symptoms of a culture where financial transparency took a backseat to maintaining a high-flying image.
Today, Alibaba operates under closer scrutiny than ever. Regulators, investors, and short sellers all demand greater transparency. Whether this has led to genuine reform or simply a more polished version of the same practices remains an open question. One thing is certain: the era of Alibaba’s unquestioned dominance is over. The company must now prove that its financials reflect reality—not just the version of reality it wants the world to see.
Comprehensive FAQs
#### Q: How much did Alibaba’s earnings get overstated?
A: Exact figures are debated, but industry estimates suggest Alibaba’s net income was inflated by hundreds of millions to over a billion dollars in certain periods due to improper revenue recognition and deferred costs. The 2018 restatement alone reduced reported earnings by $1.3 billion for two years.
#### Q: Did Jack Ma or other executives face consequences?
A: No. While Alibaba admitted to accounting errors, no executives were penalized. The restatements were framed as corrections rather than fraud, and regulators did not pursue legal action against individuals. Ma himself stepped down as executive chairman in 2019 but remains a significant shareholder.
#### Q: Are Alibaba’s financials reliable now?
A: More so than in the past, but skepticism persists. The company has tightened controls, and recent earnings reports show greater alignment between net income and cash flow. However, short sellers and some analysts still question whether Alibaba fully addressed the root causes of its past overstatements.
#### Q: How does Alibaba’s case compare to other tech companies?
A: Alibaba’s situation is unique in its scale but not in its kind. Many high-growth tech firms, including Amazon and Tesla, have faced scrutiny over aggressive revenue recognition or earnings management. However, Alibaba’s repeated restatements and the sheer size of its adjustments set it apart as a cautionary tale in financial transparency.
#### Q: What should investors look for now?
A: Investors should focus on three key metrics:
1. Free cash flow (not just net income) to gauge true profitability.
2. Revenue recognition timing—whether sales are being booked prematurely.
3. Regulatory filings for signs of further adjustments or audits.
The company’s ability to maintain consistent cash flow, rather than just earnings growth, will be the best indicator of whether it has truly cleaned up its act.